European VLSFO prices are worth watching
February 21, 2024
There are mixed signals driving the absolute price of oil at the moment, with a slightly more bullish push over the past two weeks. But, to put it in context, this recent uptick followed a sharp drop in prices at the end of January and into the first few days of February, when Brent crude fell from $82/bbl to $77/bbl. The ‘bullish’ push in the past two weeks has only brought Brent back to $82/bbl. Read More
Recent uptick in oil prices; but for temporary reasons
There are mixed signals driving the absolute price of oil at the moment, with a slightly more bullish push over the past two weeks. But, to put it in context, this recent uptick followed a sharp drop in prices at the end of January and into the first few days of February, when Brent crude fell from $82/bbl to $77/bbl. The ‘bullish’ push in the past two weeks has only brought Brent back to $82/bbl.
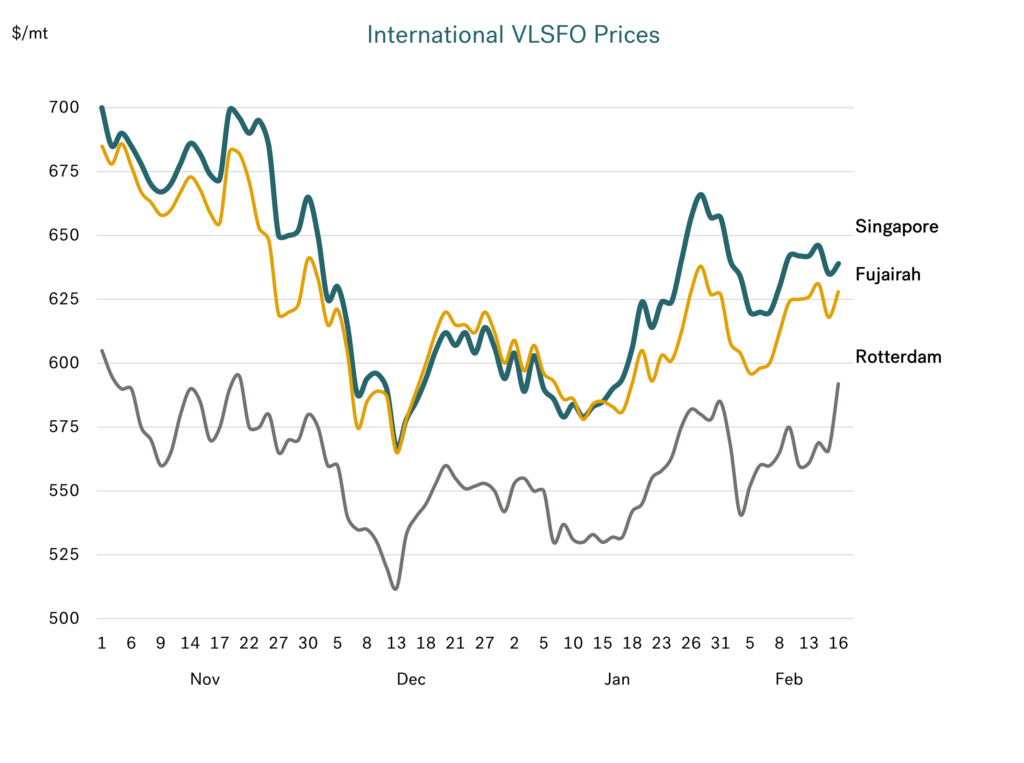
Looking at very low sulphur fuel oil (VLSFO) prices in Singapore and Fujairah, these have traded in a narrow $25/mt range so far this month and are still lower than their end January levels (and $35-40/mt lower than average November prices). This is not the case in Rotterdam.
 Source: Integr8 Fuels
Behind these price movements there have been some temporary bullish factors in the oil industry so far this year. Arctic weather conditions in North America shut in around 0.9 million b/d of oil production and halted around 1.7 million b/d refinery operations. At the same time, there have been planned, heavy maintenance programs in the Atlantic Basin refining industry running through January and into February. This again has restricted product availabilities and led to lower stock levels. But these are temporary issues!
On the bearish side, in recent reports we have focused on the weak prospects for oil demand this year, and this is still in play, especially when you look at the International Energy Agency’s (IEA) latest forecast for 2024. Also, gains in non-OPEC production look as though they will be high this year, and the recent cuts in OPEC+ production have been limited to only 0.2-0.3 million b/d from December levels. Therefore, the fundamentals for this year would indicate a ‘lid’ on prices. This, plus the ability of the industry to work around the attacks on Red Sea shipping, has so far superseded the heightened political events and risks in the Middle East region.
European VLSFO prices are ‘more exposed’
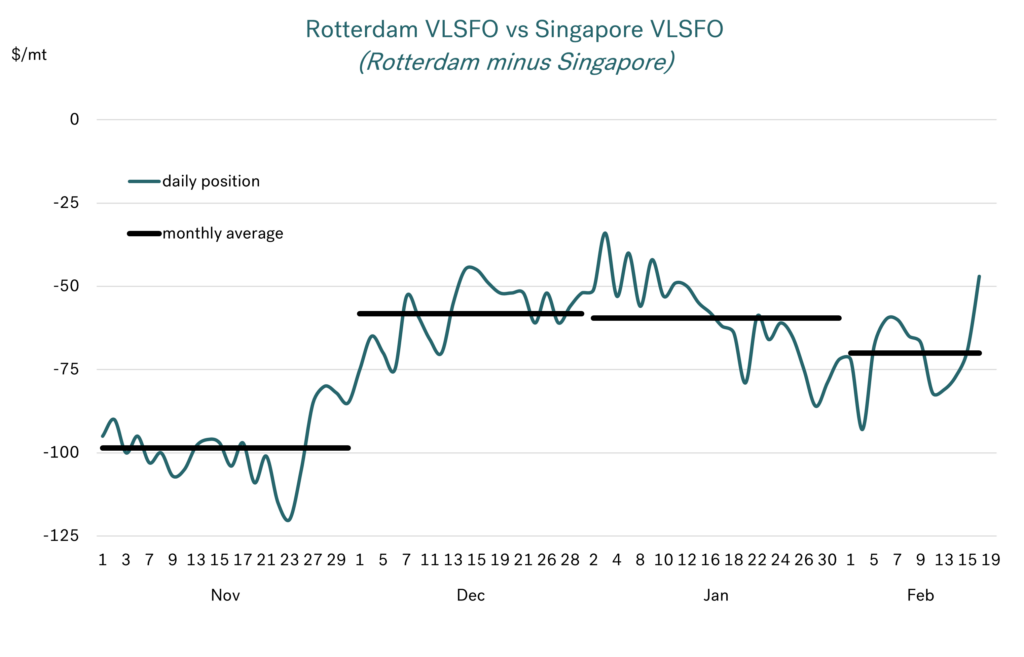
From the chart above, Rotterdam VLSFO prices have risen more steeply than in Singapore and Fujairah over the past two weeks. Rotterdam VLSFO prices are around $50/mt higher than in early February, and unlike the other major bunkering hubs, Rotterdam prices are higher than we have seen so far this year, and some $10/mt above their November average.
Back in November, Rotterdam VLSFO was priced at around $580/mt and Singapore at around $680/mt, i.e. a differential of $100/mt. Between then and now Singapore prices have fallen by $40, but Rotterdam prices have gone in the opposite direction and are around $10 higher. The net result is that the differential between the two markets has narrowed from $100- to $50/mt.
 Source: Integr8 Fuels
VLSFO pricing related to middle distillate pricing
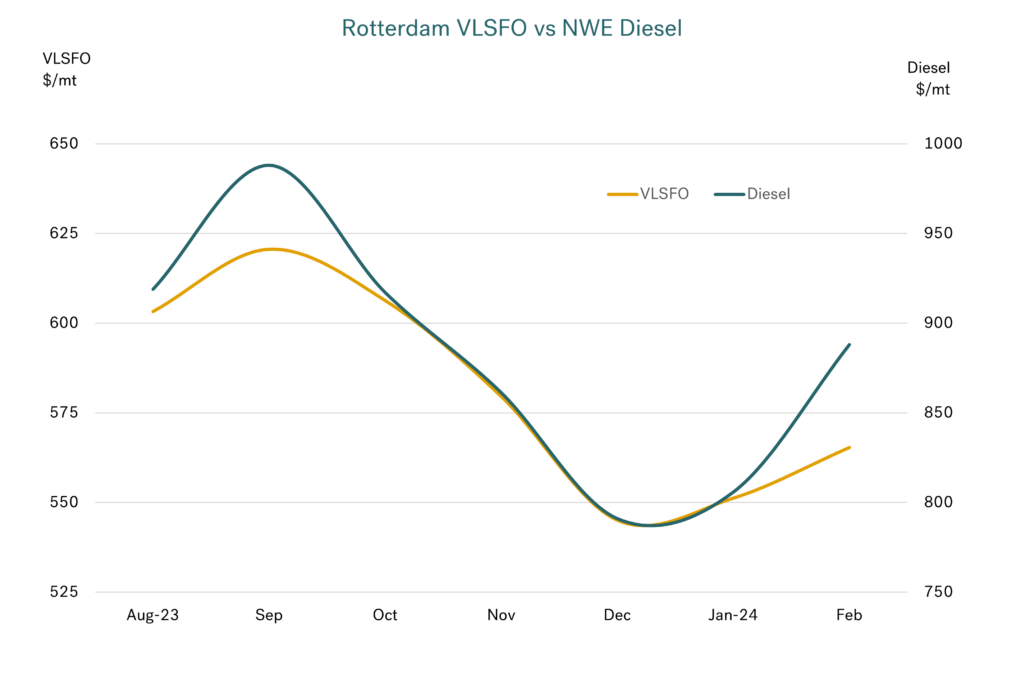
The nature of VLSFO means supply and price movements are closely related to what is happening in other products. The chart below shows the close relationship between Rotterdam VLSFO and NW European diesel prices.
 Source: Integr8 Fuels
The European VLSFO market looks like it will only get tighter
Europe is naturally short in the middle distillates of jet, diesel, and gasoil and so highly dependent on imports. The European sector had already been under pressure since the embargo on Russian supplies. However, the situation has tightened even further with the attacks on shipping in the Red Sea. These latest developments have hit diesel and jet shipments from the Middle East and India to Europe, with a leap in freight costs, longer voyage times via the Cape of Good Hope and tighter market conditions in Europe.
This loss of these supplies from east to west has partly been made up by an increase in diesel exports from the US to Europe. However, this may be short-lived as US refinery turnarounds in the first quarter cut availabilities and potentially limit diesel exports. Hence, European diesel (and so VLSFO) prices are likely to rise relative to VLSFO markets elsewhere in the world. To compound this even more, Ukraine drone attacks on Russian refineries may have affected operations and so diesel exports from the country. Although this will not have a direct impact on the European diesel position, there is an indirect consequence, with other buyers of Russian products left short and having to source supplies from elsewhere, which will be in direct competition with European buyers.
Add to this a number of major European refineries going into turnaround in the north and Med regions, and the market is potentially even tighter!
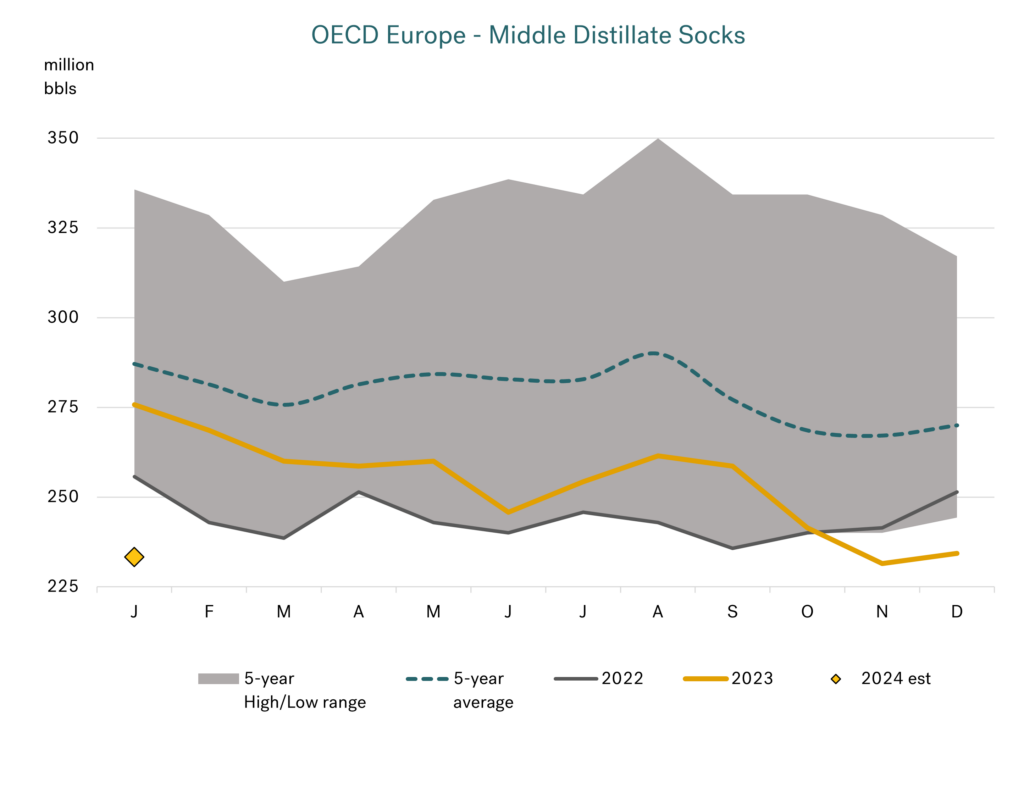
If this isn’t enough, then there is a further layer to add to the argument; and that is the current exceptionally low distillate stock levels in Europe. The graph below shows the five year high/low range for middle distillate stocks in Europe, and that for the past two years stocks have been well below their five year average. More importantly, over the past three months stocks have been below their previous five year lows, and this is at a stage when we expect the market to tighten even further.
 Source: Integr8 Fuels
Whatever happens, Rotterdam VLSFO prices are likely to be relatively high
All else being equal (it never is!), the fundamentals point towards a more bearish oil market, but with this relative strengthening in European VLSFO prices.
Beyond the fundamentals, the geopolitical risks at the moment clearly lie in the Israel/Gaza position and developments surrounding Iran. But there are also a number of elections this year that will contribute to more uncertainty, not least in the US.
However, as things pan out, the European distillate market does look tight going forward and this would mean relatively higher VLSFO prices in Rotterdam, and Europe generally.
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
What does the refining industry tell us about VLSFO for this year?
January 31, 2024
Bearish fundamentals and sentiment played out between mid-December and mid-January, with VLSFO prices on a downward slide. This was despite geopolitical tensions surrounding Houthi attacks on shipping in the Red Sea and the first US/UK air attack on Houthi targets on January 11th. Read More
Bunker prices had been falling, even with more attacks on Red Sea shipping
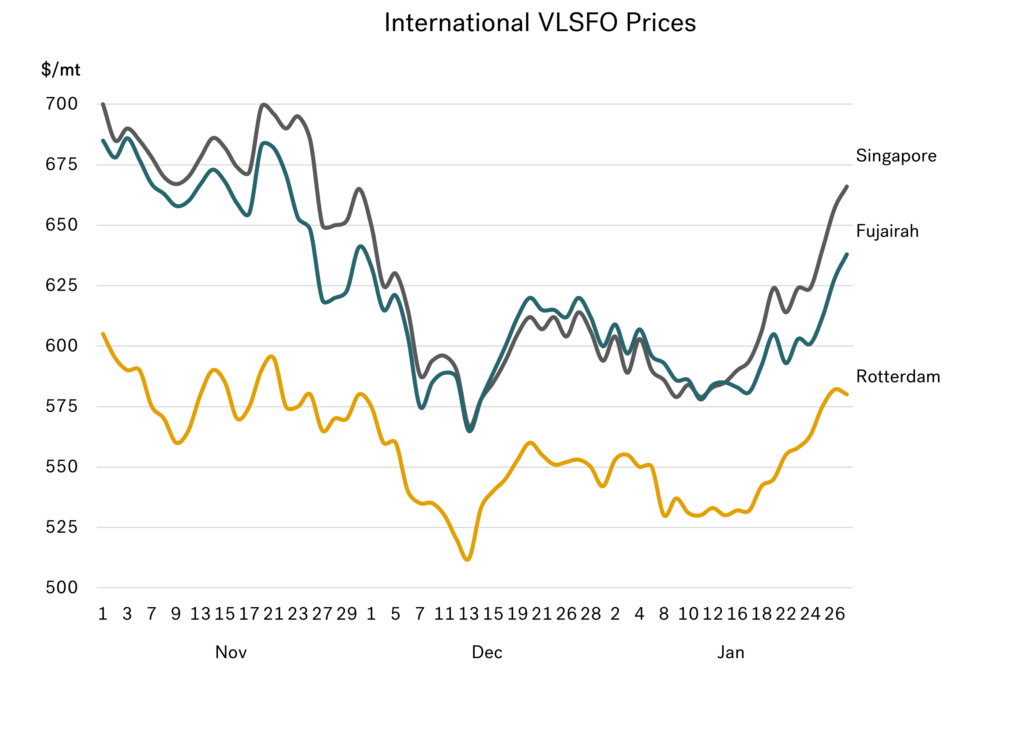
Bearish fundamentals and sentiment played out between mid-December and mid-January, with VLSFO prices on a downward slide. This was despite geopolitical tensions surrounding Houthi attacks on shipping in the Red Sea and the first US/UK air attack on Houthi targets on January 11th.
 Source: Integr8 Fuels
Something has changed, and prices are on the rise
However, over the past two weeks prices have increased, and are now back to early December levels. The main reasons behind the turning point have been:
- Stronger than expected economic growth in the US;
- More positive indications for growth in Chinese oil demand;
- Tighter product balances (because of disruptions to trade as ships re-route via the Cape of Good Hope and away from the Red Sea/Suez Canal*);
- Short-term crude production and refinery outages in the US because of cold weather.
*The main impact on oil markets so far on ships re-routing has been on diesel and jet trade from the Middle East/West Coast of India to Europe, and the naphtha and fuel oil trade from Europe to
It is these fundamental developments that have led prices higher, rather than a direct response to Houthi attacks. As a result, Rotterdam and Fujairah VLSFO prices are up by around $50/mt over the past two weeks, and Singapore VLSFO up by $80/mt.
The greater geopolitical risk now is any increased tensions/conflict between the US and Iran.
HSFO prices near ‘unchanged’
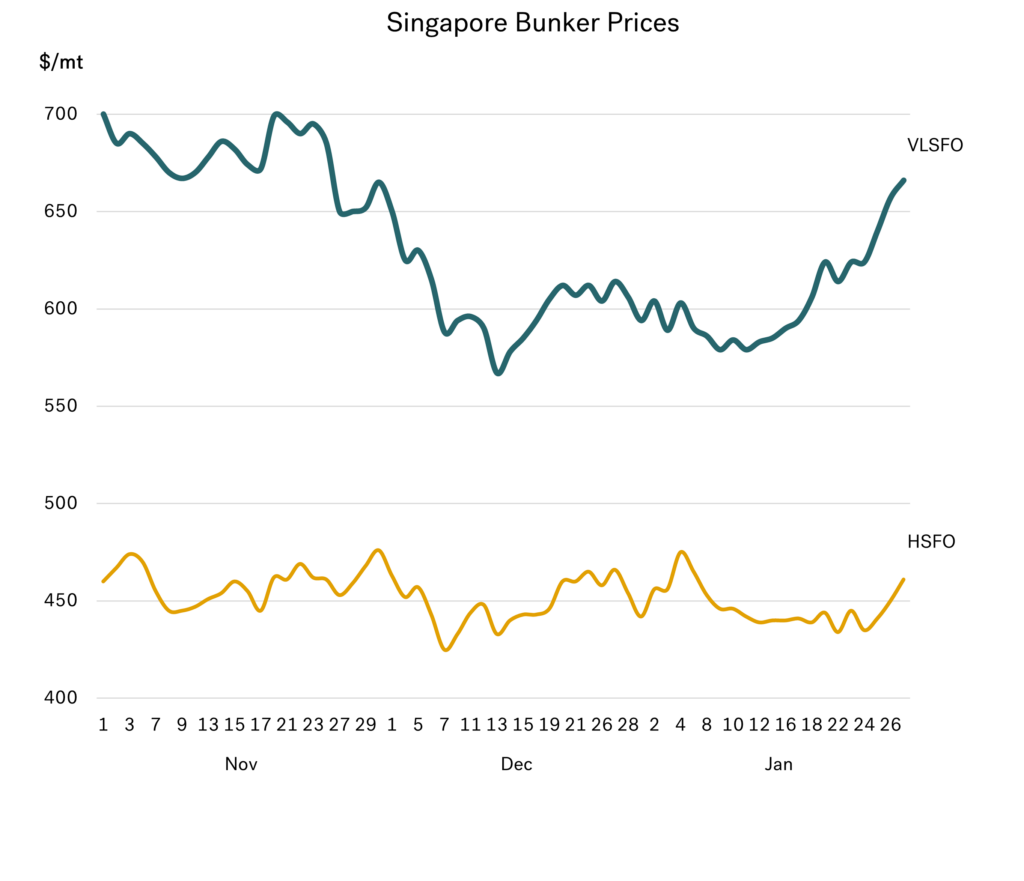
The same cannot be said for HSFO prices, which have only increased by around $20/mt in Rotterdam and Singapore over the past two weeks. An increase in heavy crude trade from the Middle East to Europe and a large-scale rise in HSFO exports from Kuwait to Asia has weakened the relative position of HSFO, in contrast to other products, including VLSFO. These price movements are shown in the graph below, with the net result that the Singapore VLSFO/HSFO spread has widened again to more than $200/mt (from $145/mt two weeks ago). This spread was last above $200/mt in late November.
 Source: Integr8 Fuels
Refinery crude throughputs will reach a record-high this year
Some of the price elements involved in today’s market are related to what is happening in the refining sector, and these influences are likely to be a continual feature this year.
Firstly, there have been a number of unplanned refinery outages, plus refinery maintenance programs are already higher than ‘normal’. Higher maintenance is expected to be a feature this year. This is because we have just been through two years of ‘light maintenance’ as margins have been so good; this year will be the time to ‘catch-up’.
Despite more maintenance, refinery crude throughput is still expected to hit a record high this year. New start-ups in Nigeria, China and Mexico, plus expansions and increased runs in the Middle East and India, will drive new capacity and throughputs much higher. These dynamics will have a significant impact on trade flows and volumes, and if the Red Sea/Suez Canal continues to be a ‘no-go’ zone, then disruptions and higher bunker demand may also be a continued feature of the market.
How big are the regional refining sectors?
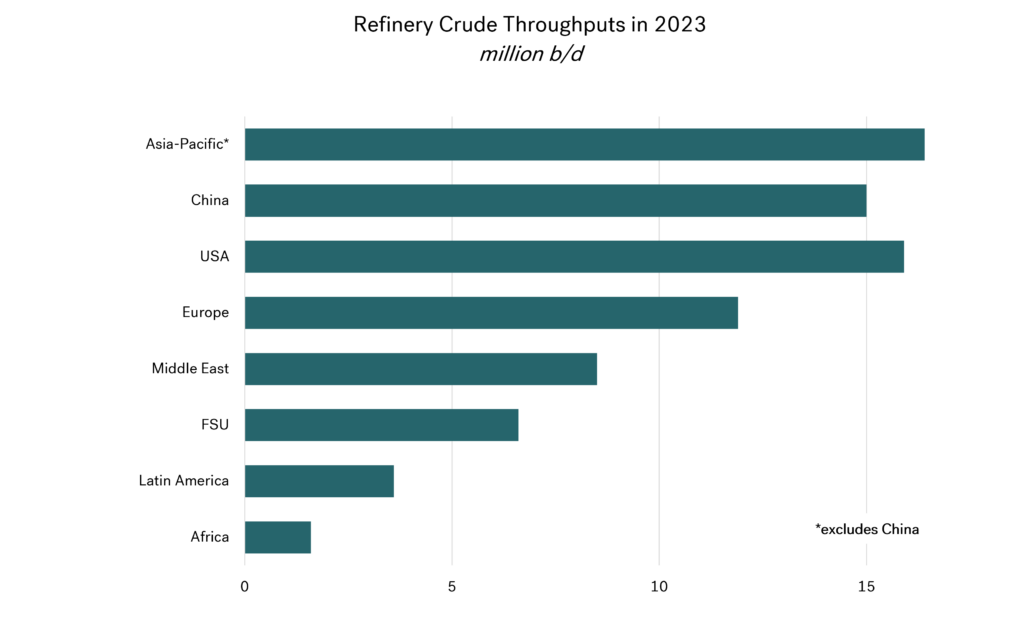
Putting some context on what is happening in each region, last year China’s refinery crude throughput averaged around 15 million b/d, with the rest of Asia-Pacific at a similar level. This puts refinery crude throughput in Asia-Pacific at 31 million b/d, and way above any other area.
 Source: Integr8 Fuels
Crude throughput in the US was close to 16 million b/d, and then volumes scale back to 12 million b/d in Europe, 6.5 million b/d in the FSU, down to only 1.6 million b/d in Africa.
Where are the big throughput gains going to happen this year?
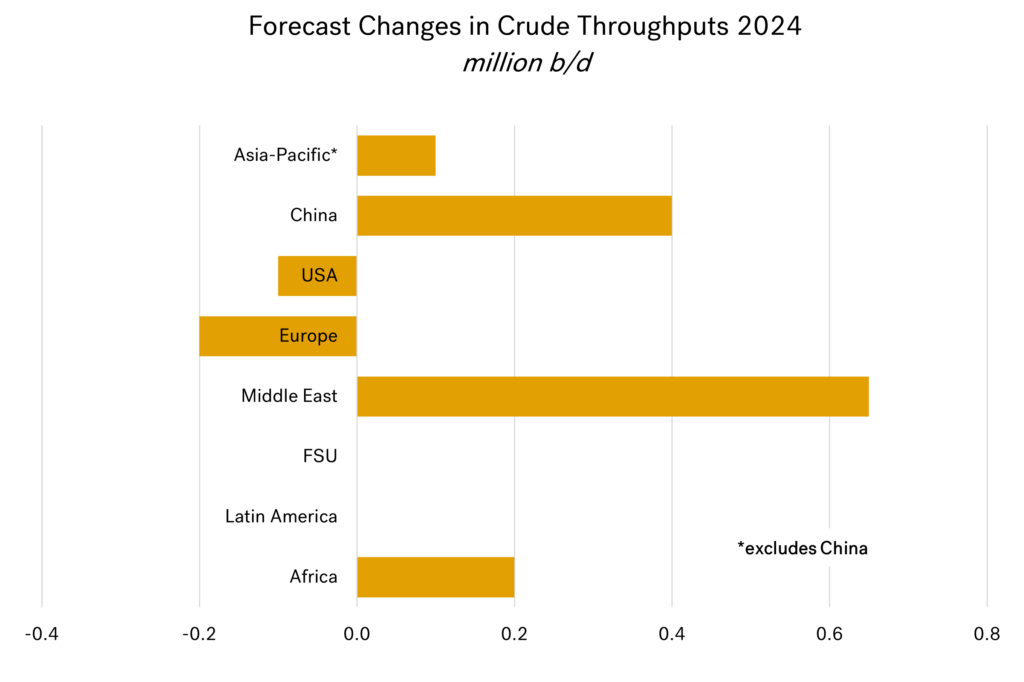
Firstly, the biggest increase in throughput this year is going to be in the Middle East, with gains in Kuwait, Saudi Arabia, Oman and Bahrain amounting to close to 0.7 million b/d more than 2023 levels (almost 8% higher).
Throughput in China is forecast to rise by around 0.4 million b/d, with the new 0.4 million b/d Yulong refinery expected to start up later this year and higher throughputs elsewhere. However, unlike other big refining centres, China has central control of crude imports and product exports, so there is always an upside and downside risk to throughput forecasts here.
Taking into account increases elsewhere, total crude throughputs in Asia-Pacific are projected to rise by some 0.5 million b/d this year (plus 2%).
 Source: Integr8 Fuels
There is a potential increase in African throughput, but this all hinges on the massive 650,000 b/d Dangote project in Nigeria. Like some other refinery projects, the start date has been pushed back numerous times. However, there are reports of crude oil moving into the site, which implies testing and commissioning of some units. Current expectations are for a start-up later this year, but this is one to watch closely as it will have significant implications for trade flows, potentially backing out gasoline from Europe to West Africa.
After this, the bigger story is possible declines in European and US refinery operations. Higher refinery maintenance programs and current outages in the US because of cold weather will impact throughputs. However, there are also ongoing threats of closures in both regions, and an extended period of weaker margins could trigger these.
Implications for product trade and VLSFO pricing
Bringing together increases in regional refinery throughputs and measuring these against regional increases in oil demand does offer a clear direction on trade flows and potential shifts in relative VLSFO pricing.
Two main pointers become clear. One is the increase in refinery runs in the Middle East this year will far exceed the gain in ‘local’ oil demand; runs up 0.65 million b/d and demand up 0.15 million b/d implies a rise of 0.5 million b/d in product exports.
At the same time, although refinery runs in Asia-Pacific are forecast to increase by 0.5 million b/d this year, oil demand is expected to be 1.0 million b/d higher. The implication is product imports into Asia need to increase by a net 0.5 million b/d this year.
Although the net imports into Asia match the forecast increase in Middle East exports, it doesn’t mean all incremental Middle East product exports will go east. Different products will have different surplus and deficit positions in all regions, so Middle East volumes will be pulled east and west; however, a bigger proportion of incremental Middle East exports are likely to go east.
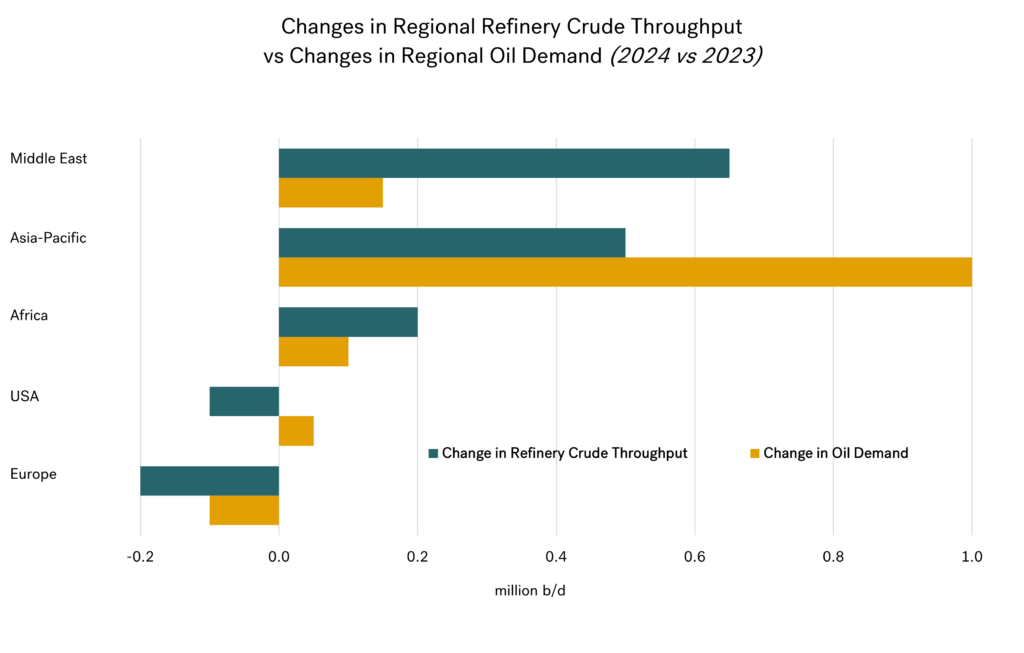 Source: Integr8 Fuels
As mentioned, the balance in Africa is highly dependent on the Dangote refinery project, but an increase in refinery throughput greater than the increase in regional demand would mean less product imports into the region and potentially product exports out.
Finally, oil demand in the OECD is ‘under threat’ and is at, or close to decline. At the same time, refinery operations in Europe and the US could also fall. It is then a question of which falls further, oil demand or refinery throughputs?
Based on this analysis, there could be an increase in demand for diesel and jet imports into Europe, which would have to be ‘pulled in’ from the Middle East/India. This is long haul trade, which could be made even longer if the situation in the Red Sea is not resolved.
In the US, the position is less clear, as both demand and refinery operations could go either way this year, although in the longer run both are expected to decline.
More product trade from the Middle East pulled east and west
Looking at the net product trade positions in the main bunkering centres of Singapore and Rotterdam, it seems both regions are going to need increased imports and that most of these volumes will have to come from the Middle East. This has implications for trade, delays, bunker demand, but importantly for us it implies no obvious oversupply or relative weakness in VLSFO pricing in either bunkering centre in 2024.
VLSFO is likely to trade at an increasing premium to crude oil in 2024. Watch crude, and then add a bit more!
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
Prices still look like falling, even after OPEC+ announce a 2.2 million b/d cut.
December 21, 2023
A month ago, we wrote about the oil fundamentals looking more bearish and that OPEC+ may cut production at their end November meeting to counter these views and support oil prices. Well, OPEC+ did come up with an agreement to cut output by 2.2 million b/d, but oil prices still fell! Read More
Oil prices are down, but Singapore VLSFO is DOWN.
A month ago, we wrote about the oil fundamentals looking more bearish and that OPEC+ may cut production at their end November meeting to counter these views and support oil prices. Well, OPEC+ did come up with an agreement to cut output by 2.2 million b/d, but oil prices still fell!
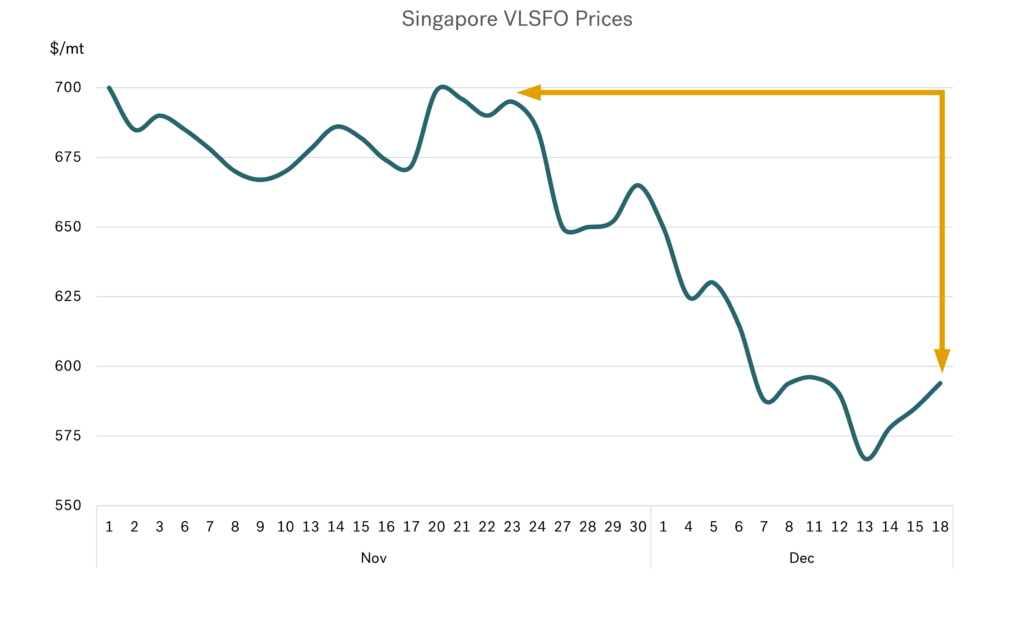
From the lead-up to the OPEC+ meeting to now, Brent crude is down by around $6/bbl, and Rotterdam VLSFO is down by around $50/mt. However, with tightness in the Singapore VLSFO market unwinding at the same time, bunker prices here have fallen by a massive $100/mt over the past four weeks (15%). All this is certainly welcome news for bunker buyers, but also shows the bearish nature of the market at the moment.
 Source: Integr8 Fuels
There are always three reasons for market moves!
The three key features why we are seeing much lower oil prices and the big drop in bunker prices are:
- There are more bearish signals for growth in world oil demand, predominantly because of weak global economic prospects and the knock-on effects.
- Increases in non-OPEC oil production are much bigger than most people expected, especially in the US, but also with output ramping up in Brazil and Guyana.
- Actual production cutbacks from OPEC+ will be much lower than the headline 2.2 million b/d figure that came out of the end November meeting, and could be even less than 0.5 million b/d.
Again, it is these fundamental features that are currently driving the market, and the fundamentals look weak.
US production has hit record highs – and it means lower oil prices
Until recently the main talk in the US shale sector was of limited new investments, constraints on equipment and labour, and a general slowdown in developments. Just six months ago the view was very much that US crude production was going to remain flat. Now the market is booming!
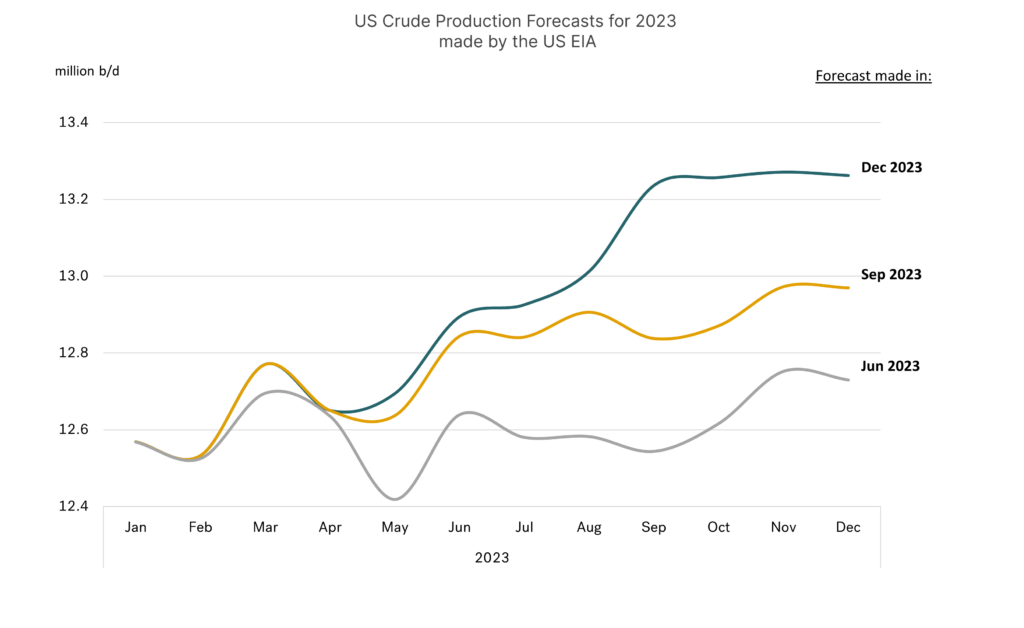
This turnaround in US shale output has come with gains in operating efficiencies and higher productivity at the wells. These moves have been far greater than people envisaged and have driven US oil output to a record high level. In the latest estimates by the US Energy Information Administration (EIA), December crude output is at close to 13.3 million b/d; three months ago, their December estimate was 13.0 million b/d and only 6 months ago it was at 12.7 million b/d.
 Source: EIA
So, over the past 6 months, the OPEC+ group has cut production by around 0.8 million b/d, but the US has seen an ‘unexpected’ increase of 0.6 million b/d. This has been a ‘surprise’ to the market, an additional challenge to OPEC+ and a blessing to those looking for lower bunker prices.
The challenge for OPEC+ to ‘manage the market’ is huge
Given the weaker prospects for growth in oil demand next year, and production gains in certain non-OPEC countries, the challenges facing the OPEC+ group going into their recent meeting were immense. The headline number of a 2.2 million b/d production cut by the group was, on the face of it, very impressive. However, it wasn’t enough to maintain prices you don’t have to dig very deep to see there are some optics in this figure.
Within these figures, Saudi Arabia has agreed again to extend its voluntary cutback of an additional 1 million b/d into the first quarter of next year. Before the OPEC+ meeting, the plan was for Saudi to end this voluntary arrangement at the end of this year. So, this is one of those cases where the ‘reduction’ is from ‘what would have otherwise happened’, not from current production levels.
In a similar development, Russia has announced that it will also rollover its 0.3 million b/d cut in crude/product exports into Q1 2024 and add a further 0.2 million b/d cut to this from January i.e. a theoretical cutback of 0.5 million b/d.
So, 1.3 million b/d of the announced 2.2 million b/d OPEC+ cutback comes from extending the Saudi and Russian voluntary cuts into Q1; it is not a cut from current production levels! There is a planned additional 0.2 million b/d cut from Russia, but there are questions about this.
Therefore, this only leaves an implied 0.7 million b/d actual cut in OPEC+ output from the start of next year. However, there is another twist, as some time ago it was agreed that the quota for the UAE will be increased by 0.2 million b/d from the start of 2024. This means the actual agreed OPEC+ cut from current levels is only 0.5 million b/d, and full adherence to this is questionable.
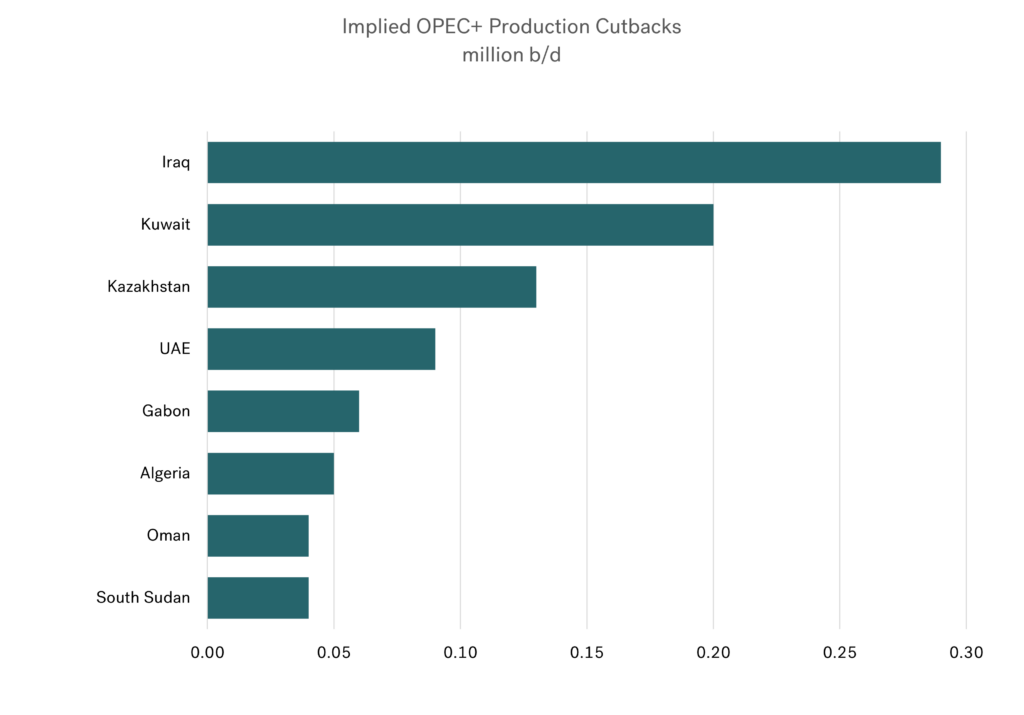
Based on the new quotas and that some OPEC+ members are producing more than their existing allocation, the chart below illustrates the countries that need to cut production and by how much to ‘fall in line’ with the new agreement starting in January.
Source: Integr8 Fuels
Focus is likely to be on the four biggest countries here, and a general view is that not all of these will be fully compliant. Also, the existing agreement excludes Iran and Venezuela, where there are potential increases in production. This means OPEC+ will be doing very well if they can reduce current production by even as much as 0.5 million b/d, despite the headline news of a 2.2 million b/d cutback.
The market still looks bearish
In summarising these reports, geopolitics are always the great unknown. But, based on the prospects for oil demand, increases in non-OPEC production and as we have outlined here, the reality/challenges to OPEC+, the market still looks bearish. The fundamentals are still pointing towards lower bunker prices.
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
Integr8 achieves ISCC EU certification to trade sustainable biofuels and help shipowners prove compliance.
December 19, 2023
Integr8 Fuels announces they have been awarded certification from the International Sustainability and Carbon Certification (ISCC) scheme for the trading of biofuels. Read More
Integr8 achieves ISCC EU certification to trade sustainable biofuels and help shipowners prove compliance with environmental regulations.
Integr8 Fuels has today announced they have been awarded certification from the International Sustainability and Carbon Certification (ISCC) scheme for the trading of biofuels. The news comes in advance of a raft of regulations from the EU designed to reduce greenhouse gas (GHG) emissions from shipping, which are due to come into effect in 2024 and 2025.
In order for shipowners to reduce their emissions exposure towards environmental regulations like the EU Emissions Trading System (EU ETS) and FuelEU Maritime, they will need to show that the low carbon fuels they consume are sustainable and meet the criteria defined in the EU’s Renewable Energy Directive (RED II).
As conventional ship engines can run on biofuels, they can have an edge over alternatives like LNG, which requires specialised engines. For biofuel suppliers, however, this market power comes with great responsibility. Biofuel suppliers and operators will have to provide a Proof of Sustainability (PoS) or similar documentation to verify the sustainability of feedstock and energy inputs.
ISCC is a global certification system that sets standards for sustainable production, sourcing and trade of all kinds of bio-based feedstocks and biofuels. A PoS follows a fuel batch throughout its whole supply chain with GHG estimates.
Integr8’s Bunker Quality and Claims Manager, Chris Turner, asserts why certification and documentation of this nature will be paramount in the evolving alternative fuels regime.
“Shipowners are turning to alternative fuels with significantly lower emissions than fossil fuels to trim the greenhouse gas emissions from their vessels. Alternative fuel suppliers must show that the bio-components in their fuels are sustainable and provide proof of that to their customers.
With ISCC EU certification, we are demonstrating our capability and commitment to trading biofuels that have been produced by ethical and sustainable practices, and importantly, we can provide the Proof of Sustainability that clients need to verify this with regulators. It provides an additional layer of trust and reassurance for our customers.
Without this documentation, then the biofuels, which are generally bought at premiums to conventional fuels, would not be counted in any emissions saving, counting the same as mineral fuels.”
Ultimately, the benefit of requiring documentation is twofold:
“Not only will certification ensure we are making meaningful strides towards decarbonising the industry, but it will also bring enhanced transparency and accountability to a historically opaque sector. I am hopeful that we will emerge a better and more professional industry as a result,” Chris explains.
Integr8’s ISCC EU certificate will enable the international bunker trading firm to pass on PoS for liquid and gaseous biofuels, including fatty acid methyl ester (FAME), hydrotreated vegetable oil (HVO) and liquefied biomethane (LBM).
Press Contact: Angela Freeth
Email: angela.f@integr8fuels.com
Tel: +44 (0) 207 467 5877
To see how we can assist you with your fuel procurement requirements, visit our Contact Us page.
A look at the fundamentals and what analysts say for prices next year
November 22, 2023
A month ago, we illustrated how movements in VLSFO prices very closely tracked changes in Brent crude on a short-term basis. Read More
VLSFO prices are tracking crude, so just follow crude!
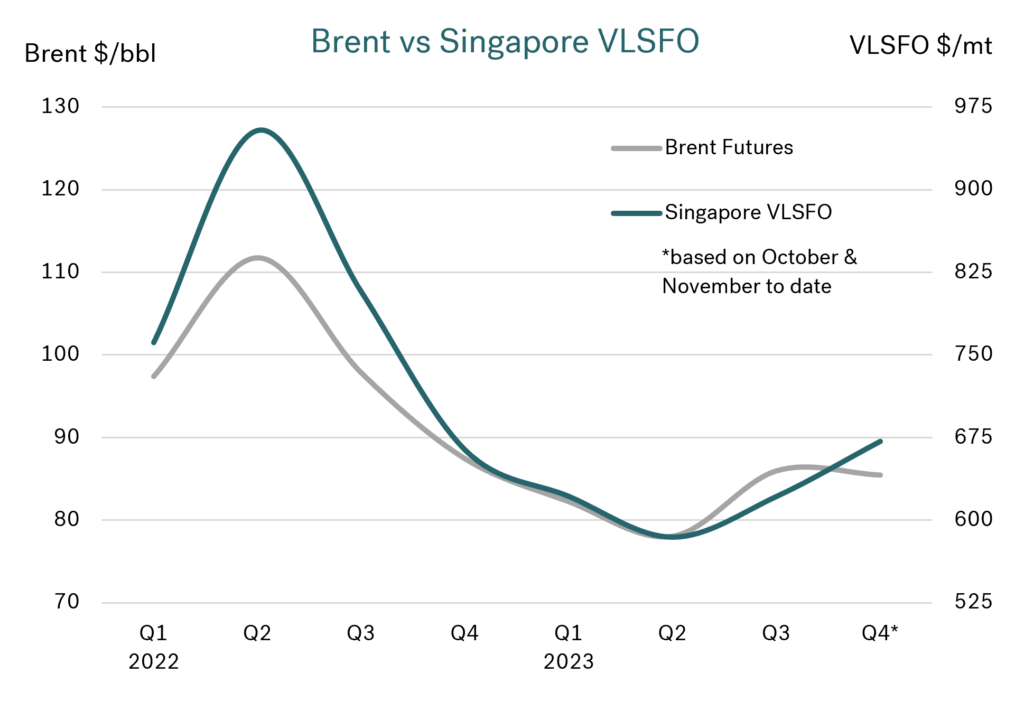
A month ago, we illustrated how movements in VLSFO prices very closely tracked changes in Brent crude on a short-term basis. Here we are extending the analysis back to 2022 and using it as the starting point to look at what analysts are saying about the fundamentals for next year and where this could take Brent and VLSFO prices in 2024.
Source: Integr8 Fuels
Back in Q2 and Q3 last year there was an extreme price premium for VLSFO over crude, but this was when products markets were exceptionally tight and refining margins at historic highs. Since then, VLSFO pricing has closely tracked Brent crude, with quarterly average prices for Brent in the $80-90/bbl range and Singapore VLSFO $600-675/mt.
Current expectations are that there will be sufficient product supplies going forward and that VLSFO will continue to follow movements in crude oil prices. Now comes the difficult part, what are the analysts saying for the fundamentals and crude prices next year?
Different analysts equals different demand outlooks
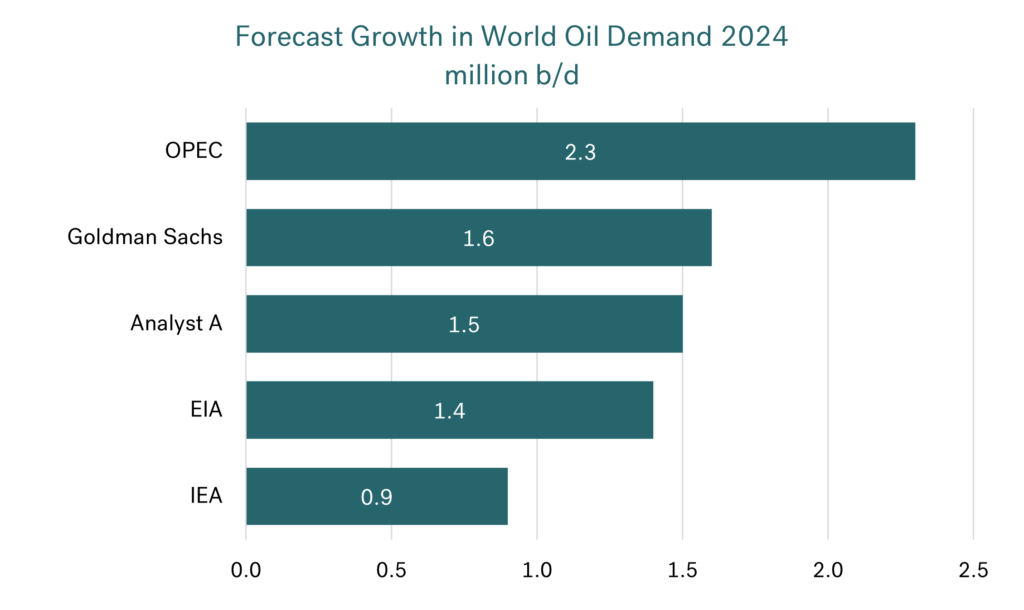
A month ago, Brent prices were in the $90s, with fears about the Middle East driving prices up. Today, Brent is in the low $80s and the general talk on oil prices again centres on the fundamentals. Looking at what various analysts are saying, the first thing to note is there are widely differing views for next year. Usually forecasts of growth in world oil demand tend to converge around the same levels, but this isn’t the case today. Some analysts are looking at a ‘typical’ underlying increase in demand of around 1.4-1.5 million b/d next year. However, there are more extreme cases being put forward, with OPEC the most bullish and indicating a very strong demand increase of 2.3 million b/d and suggesting the current negative sentiment is exaggerated. At the other end of the spectrum, the IEA is far more conservative with a growth projection around 0.9 million b/d for 2024.
 Source: Integr8 Fuels
These differences in demand not only have an impact on the fundamentals for the oil market, but also a forceful influence on market psychology. It would seem a ‘typical’ increase of 1.4-1.5 million b/d is more price neutral, but confirmation of a lower demand increase is likely to send more bearish tremors through the market.
The most important single aspect of demand next year is what happens in China. Here forecast increases range from around 0.4 million b/d up to 0.7 million b/d growth. By definition, signs of weaker economic prospects in China are likely to damage demand and send oil prices lower!
However, another factor will be what happens in the US and Europe. Here the focus will be on the shift towards electric vehicles (EVs) and the potential declines in oil demand in these regions. The IEA is currently indicating total US oil demand falling by 0.2 million b/d next year, and Europe down by 0.1 million b/d. OPEC is forecasting continued increases in US and European oil demand next year (each up by 0.1 million b/d), and the US EIA is showing US oil demand up by 0.2 million b/d and Europe down by 0.1 million b/d.
This ‘mixed bag’ of forecasts for the US and Europe does have an impact on the overall growth in world oil demand next year and will impact on sentiment. It will also set the scene for how quickly oil demand in the OECD countries can be reversed through switching to EVs.
Oil supply highly dependent on Saudi Arabia and OPEC+ policy
Since July, Saudi Arabia has made an additional, voluntary production cutback of 1 million b/d, which has been extended to the end of this year. However, with current more bearish talk, there have been some market suggestions and hints that Saudi Arabia will make a further extension of this cutback, through to the first or second quarter of next year (but nothing official has yet been announced).
Other suggestions are that the OPEC+ group will make further cutbacks at its upcoming meeting on 26th November. However, with many members not able to reach their current quota allocation, any reduction in quotas will have to be closely inspected against current production levels, to assess any real impact on world oil supplies.
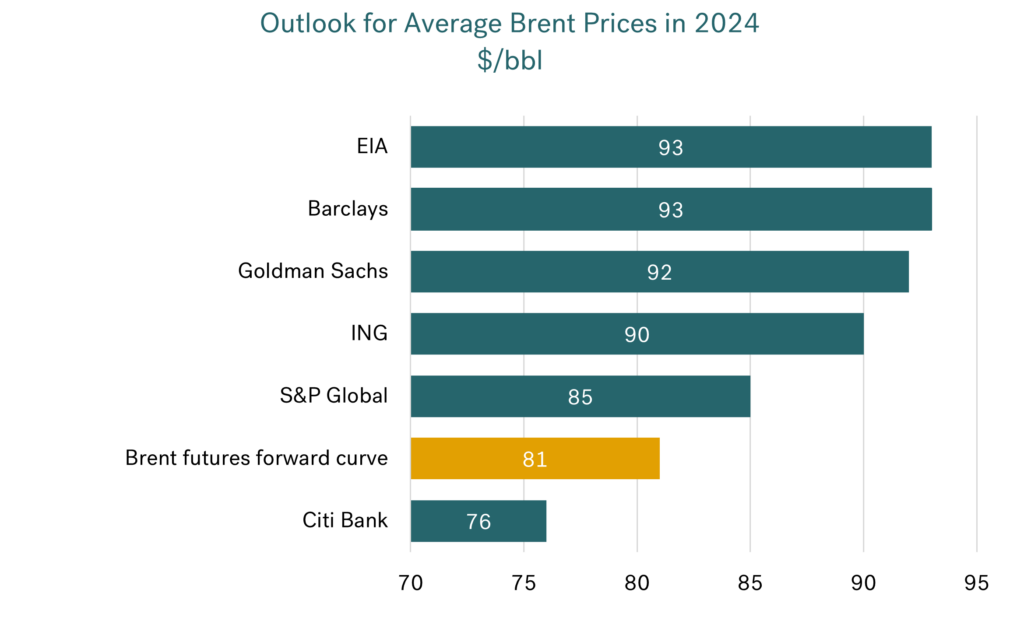
Most price forecasts for 2024 are higher than today!
Taking the ‘mid-case’ view on growth in world oil demand at 1.4-1.5 million b/d, the price forecasts appear to incorporate a Saudi extension of their voluntary cutback into 2024, and possibly even further cutbacks by OPEC+ collectively; the numbers don’t stack up if Saudi Arabia adds 1 million b/d to production at the start of next year.
Source: Integr8 Fuels
Citi Bank is the only analyst here with a ‘lower than current’ price prediction for next year. The bank has been typically known as a more bearish forecaster of oil prices and that is clearly the case here. However, if Saudi Arabia and OPEC+ don’t make moves to lower output going into 2024, then the Citi Bank view is highly credible.
What does this mean for VLSFO prices next year?
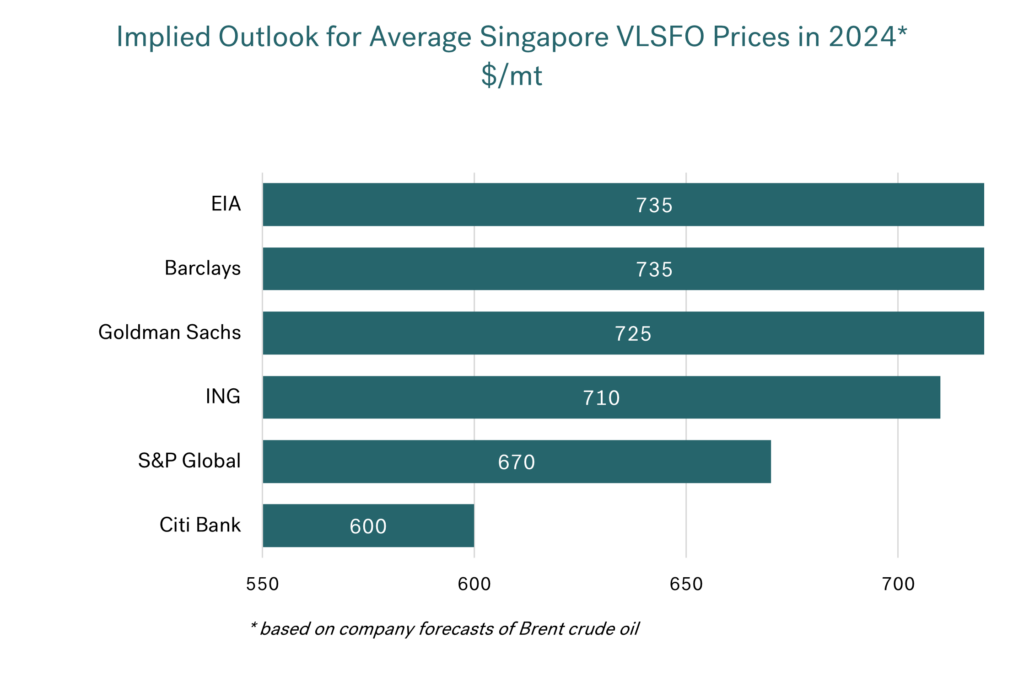
Taking the straight relationship between VLSFO prices and Brent crude prices that we have seen since Q4 last year, and extending this through 2024, the following chart illustrates the implied average pricing for Singapore VLSFO based on the company predictions for Brent crude. Again, most are above today’s levels, with Citi Bank considerably lower at around $600/mt.
 Source: Integr8 Fuels
Wrapping up
The bottom line is there is an increasing pressure in the market towards lower oil prices. However, many analysts are betting on Saudi Arabia responding to these pressures and extending (or even increasing) their additional voluntary 1 million b/d cutback beyond December and into next year.
An announcement is expected at the OPEC+ meeting on 26th November. If they do extend, then in the short term, prices are likely to be at least maintained in the $80s for Brent and Singapore
VLSFO somewhere close to $700; if they don’t, then we should be looking at lower Brent crude prices and so lower bunker prices. For the very short term, all eyes are on Saudi Arabia and its willingness to continue ‘carrying the can’ supporting higher oil prices.
But there is a long way to go, even before we get to 2024. For next year’s outlook people will also
be looking at oil demand in China, coupled with the potential declines in oil demand in the US
and Europe.
These supply and demand stories are likely to be very persuasive arguments in oil and bunker price direction. Geopolitics aside, at the moment the fundamentals for next year still look more bearish than bullish.
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
Shipping navigates towards transparency amidst rise in alternative fuels
November 20, 2023
The opacity and uncertainty that plagues the maritime industry may finally start to shift thanks to the requirement for Proof of Sustainability (PoS) in alternative fuels. Read More
The shipping sector has come under increased scrutiny due to its environmental impact and lack of transparency in recent years. But it may “finally shift from the opacity (and endemic mistrust) of the past to a more professional, transparent and traceable future,” Integr8 Fuels bunker quality and claims manager Chris Turner writes in the company’s latest bunker quality report.
Need for change
Shipowners are turning to alternative fuels with significantly lower emissions than fossil fuels to reduce the greenhouse gas (GHG) emissions of their vessels. As technology advances, ships may eventually run on fuels with zero-emission potential such as ammonia or methanol.
For now though, biofuels and liquefied natural gas (LNG) are the most promising conventional fuel alternatives to meet upcoming emission intensity-reduction targets in the European Union’s FuelEU Maritime regulation and the International Maritime Organisations’ (IMO) revised GHG strategy. As conventional diesel engines do not require any modifications to run on biofuels, they have a competitive edge over LNG. For biofuel suppliers, however, this power comes with great responsibility.
Encouraging a culture of responsibility
With the EU’s Emissions Trading System including shipping from next year, and with FuelEU Maritime coming into effect from 2025, shipowners will have to report their fleets’ verified emissions to, from and between EU ports. Turner explains that alternative fuel suppliers must show that the bio-components in their fuels are sustainable and provide proof of that to their customers.
“If this is not possible then the alternative fuels, which are generally bought at premiums to conventional fuels, would not be counted in any emissions saving, counting the same as mineral fuels,” he says.
As a result, alternative fuel bunker buyers – especially biofuel consumers – will pay close attention to the feedstocks and well-to-wake emissions associated with these fuels. This is likely to compel suppliers to maintain and encourage transparency and traceability through their product supply chain.
“Of course, not all suppliers will embrace alternative fuels or mandatory mass flow meters (as recently announced in Rotterdam, Antwerp and Brugge ports),” Turner argues, “but those who do will quickly realise their tried and tested practices will be challenged by the end users who will demand they demonstrate and certify sustainability.”
Navigating towards transparency
Documentation will be paramount in the evolving alternative fuels regime, Turner argues.
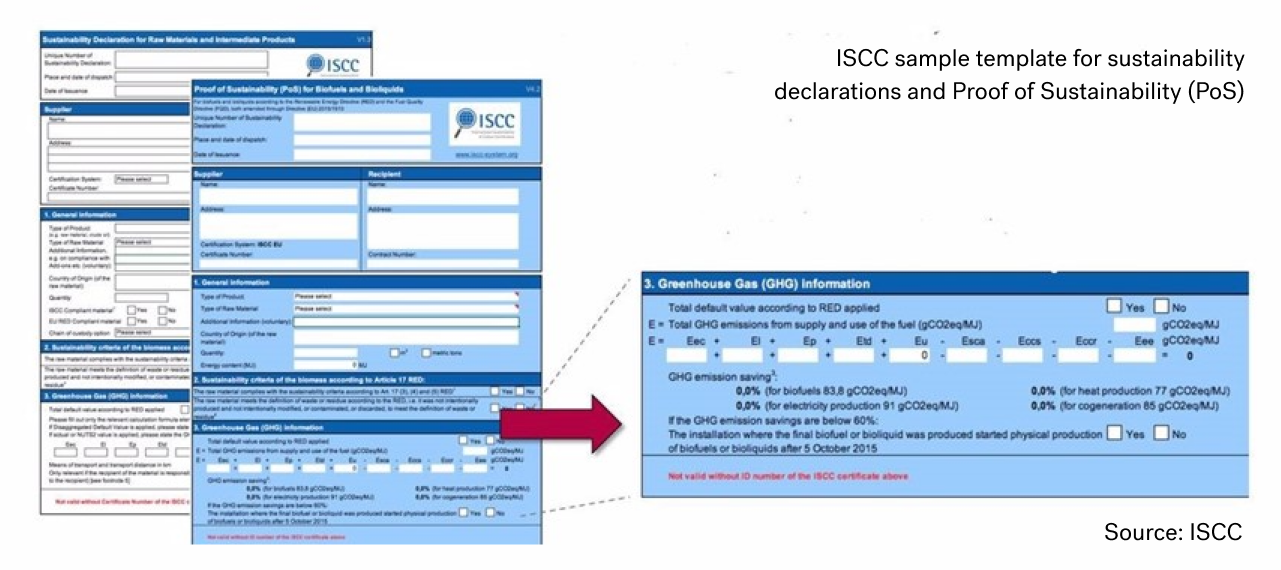
The Bunker Delivery Note (BDN) issued by the marine fuel supplier must include the alternative fuel product and grade. For biofuels, bunker suppliers and operators will have to provide PoS or similar documentation to verify the sustainability of feedstock and energy inputs. The International Sustainability & Carbon Certification (ISCC) is globally recognised as an approved sustainability certificate.
ISCC is a global certification system that sets standards for sustainable production, sourcing and trade of all kinds of bio-based feedstocks and biofuels. A PoS will be passed on throughout the whole supply chain – from initial producer to end consumer. It evaluates the sourcing of raw materials, supply chain management, land use, GHG emissions and social aspects of various companies’ activities.
This could all lead to a “changing of the guard” in the bunker industry, Turner suggests. Stakeholders “from barge deck hand to buyer, and beyond” will need to be retrained to avoid ambiguity on the BDN for the verifier, according to Turner.
Unlike IMO 2020, which was an overnight shift to mostly low-sulphur fuels, the gradual shift to alternative fuels will give suppliers time to realign their efforts to meet evolving industry standards for transparency and sustainability.
Turner discusses this subject, and assesses trends related to biofuels and all conventional grades of marine fuels in the free Bunker Quality Trends Report (Q3-2023).
Press Contact: Angela Freeth
Email: Angela.f@integr8fuels.com
Tel: +44 207 467 5877
Bunker Quality Trends Report November 2023
November 7, 2023
Integr8 Fuels’ third bi-annual report analyses data from 120 million metric tons of supply, to reveal key trends relating to fuel quality and availability. In this issue, we add biofuels data into the mix. Read More
Integr8 Fuels’ Bunker Quality Trends Report November 2023
Integr8 Fuels’ third bi-annual report analyses data from 120 million metric tons of supply, to reveal key trends relating to fuel quality and availability. In this issue, we add biofuels data into the mix.
This report covers the previous six months of supplies globally where we dissect and compare the likelihood of hidden losses and off specification issues across all commercial grades of bunkers and key ports.
Finally, given the context of the incoming changes we will consider some of the challenges that decarbonisation and verification of emissions will bring to the industry.
Topics covered include:
- The supply landscape as it relates to availability and specifications
- Biofuel quality and distribution
- Off-specification trends and problematic parameters
- Geographical variances and “hot spots”
- ISO 8217:2024 and the importance of incorporating new specifications
- MARPOL & SOLAS compliance challenges
- The risk of non-homogenous VLSFO blends and the impact to the end user
Download the report (PDF) (Recommended for mobile) >>
About the Author:
Chris Turner, Technical Manager
Chris joined Integr8 Fuels in 2017, spending several years in Singapore before relocating to Dubai. With over 35 years in oil and shipping, he has held roles in laboratory management, physical supply, broking, and trading. More recently, he has focused on technical supervision of exclusive buying and helped develop quality systems for biofuel purchasing, leading to Integr8’s ISCC certification.
An active IBIA Technical Working Group member, Chris is also a regular speaker and panellist at major bunkering conferences worldwide.
Integr8 Fuels launches Brazil office to service an increasingly dynamic South American market
October 26, 2023
Global marine fuel trading company, Integr8 Fuels, has this week opened a new office in Rio de Janeiro, Brazil. Integr8, which previously serviced South America from its US offices, says now is an ideal time to establish a local trading desk as the market is becoming increasingly dynamic following the sale of state-owned refineries in recent years. Read More
Integr8 Fuels has this week opened a new office in Rio de Janeiro, Brazil. Integr8, which previously serviced South America from its US offices, says now is an ideal time to establish a local trading desk as the market is becoming increasingly dynamic following the sale of state-owned refineries in recent years.
Until two years ago, Petrobras owned the largest and almost all other local refineries in Brazil. It was the only physical bunker fuel oil supplier in the country, alongside other players that supplied the market exclusively with Marine Gas Oil (MGO).
The market has since evolved, and a year ago the first non-Petrobras bunker fuel oil delivery was made. Several physical bunker suppliers have made recent entries and brought fresh dynamism, more pricing opportunities and greater delivery flexibility to Brazil’s bunker market.
A more diverse field of fuel producers and bunker suppliers has unlocked new opportunities that buyers in the know stand to benefit from. The types of fuels available has expanded to include most of the top fuel oil and gasoil grades, and a selection of lower-carbon products. These supply chain developments are expected to help Brazilian ports compete with long-established bunkering ports worldwide.
Integr8 Fuels’ new trading desk is led by Lucas Oliveira, a Brazilian industrial engineer with a background in marine sales, trading, fuels distribution, new business development, and the commercial aviation market. With an MBA degree in Oil and Gas Management from Fundação Getulio Vargas and representing the 4th generation in his family to work in shipping, Lucas is excited to witness the latest developments in the sector.
“We are pleased to be closer to our clients in South America, offering on the ground support as they navigate a more complex and vibrant supply chain. With Integr8’s local and international market intelligence and expertise alongside them, clients will be well-supported to make the best of these new opportunities. And as the landscape continues to evolve, we’ll be strengthening both new and existing supplier relationships.” Lucas said.
In addition to providing access to all the main fuel grades, Integr8 continues to establish itself in the alternative fuels space.
“We’re geared up to assist clients in the move to lower carbon options and are strengthening our network coverage of lower carbon fuels such as biofuels and LNG.” Lucas added.
Interested parties are invited to reach out to Lucas directly.
Contact Lucas Costa de Oliveira:
Email: lucas.c@integr8fuels.com
Mobile: +55 (21) 9 7183 1991
Address: Rio de Janeiro/RJ – Brasil, Rua Visconde de Inhaúma, 37 Sala 801 – Centro
Geopolitics have a huge bearing on our market, but something different is happening in HSFO bunker pricing.
October 26, 2023
It is often said that the more dramatic movements in oil prices are usually driven by world events, and that the bunker market is no different to any other part of the crude and products markets. Read More
We are in a global, geopolitical market
It is often said that the more dramatic movements in oil prices are usually driven by world events, and that the bunker market is no different to any other part of the crude and products markets.
This is exactly what has happened in October. Crude prices were falling in the first week of the month on the back of weaker economic indications for China and Europe. Even though Saudi Arabia and Russia stated they would maintain their voluntary production cutbacks through to the end of the year, this had little impact on the market and oil prices continued their bearish slide.
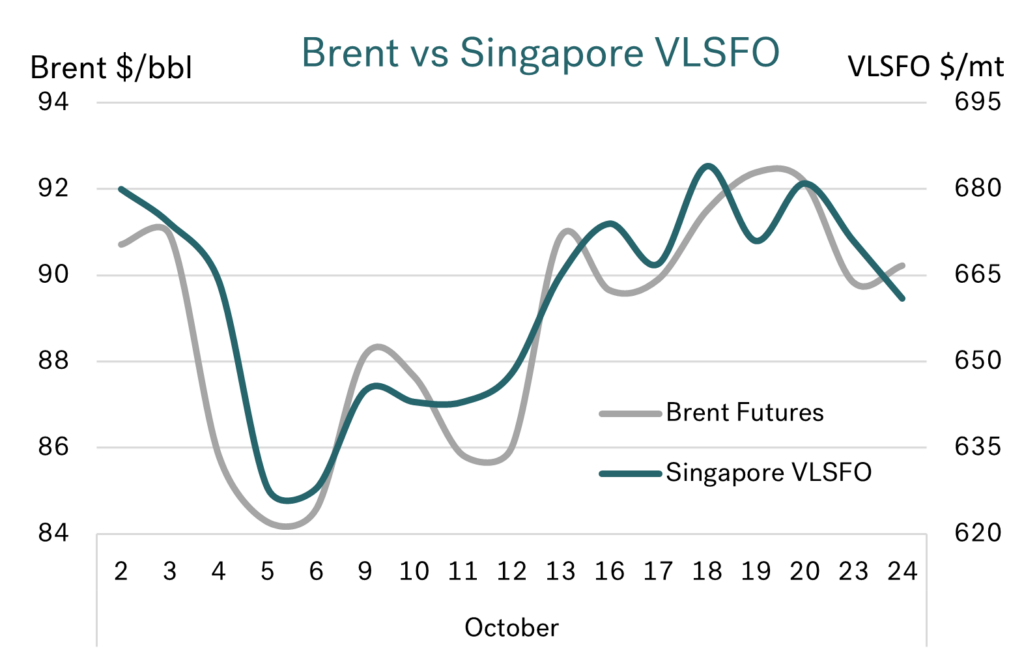
Over this first week of October Brent futures were down $7/bbl, Singapore VLSFO down $50/mt and Rotterdam VLSFO down by almost $40/mt.
Shortly thereafter, the extreme events in the Middle East took hold. Oil prices rebounded with the news, wiping out the declines seen in the previous week; Brent futures moved back up to the low $90s, Singapore VLSFO returned to around $680/mt, and Rotterdam VLSFO hit $625/mt.
These “down and up” price developments and the close relationship between Brent crude and VLSFO are shown clearly in the chart below.
Source: Integr8 Fuels
Prices have eased at the time of writing, as people wait to see where the Middle East conflict goes and weaker economic indicators out of Europe come to the forefront.
Crude price direction is usually a very good guide for VLSFO
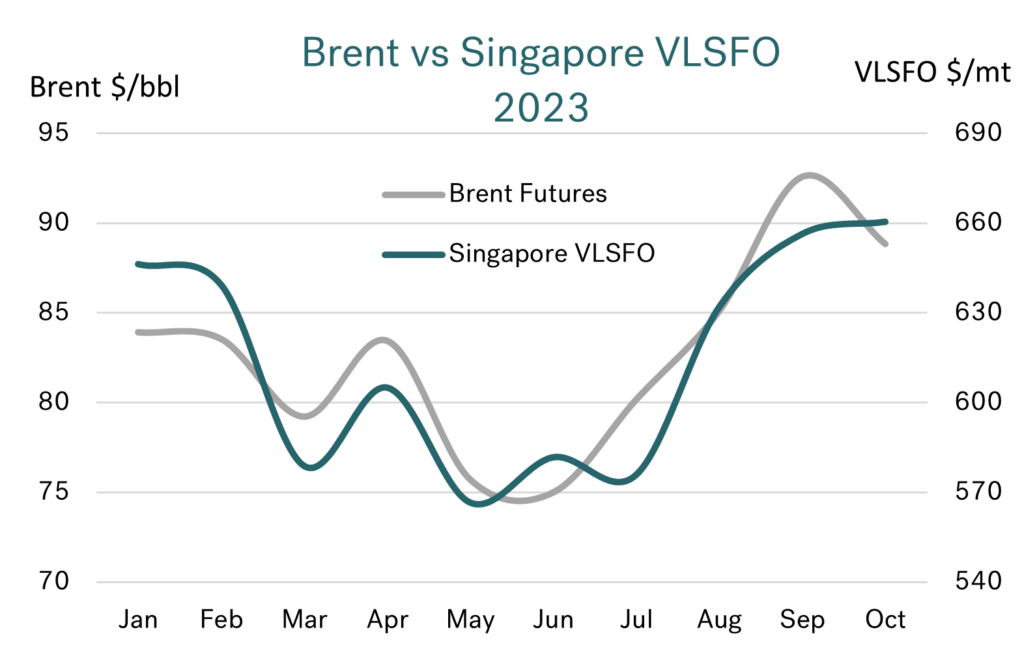
Putting some longer-term context into the Singapore VLSFO versus Brent relationship, the chart below illustrates monthly average price developments for these two commodities so far this year. It shows their very strong correlation and the range in pricing. When Brent crude was around $75/bbl, Singapore VLSFO was close to $575/mt. With recent crude prices rising to their highest levels so far this year and Brent in the low $90s, so monthly average Singapore VLSFO prices are at $660/mt and almost $100/mt above their mid-year lows.
 Source: Integr8 Fuels
In the near term, a lot of the movement in crude oil prices will be linked to what is happening in the Middle East, and so VLSFO price direction will be derived from these events. However, there are still nuances within the bunker market that we continue to monitor, not least the differences between VLSFO and HSFO.
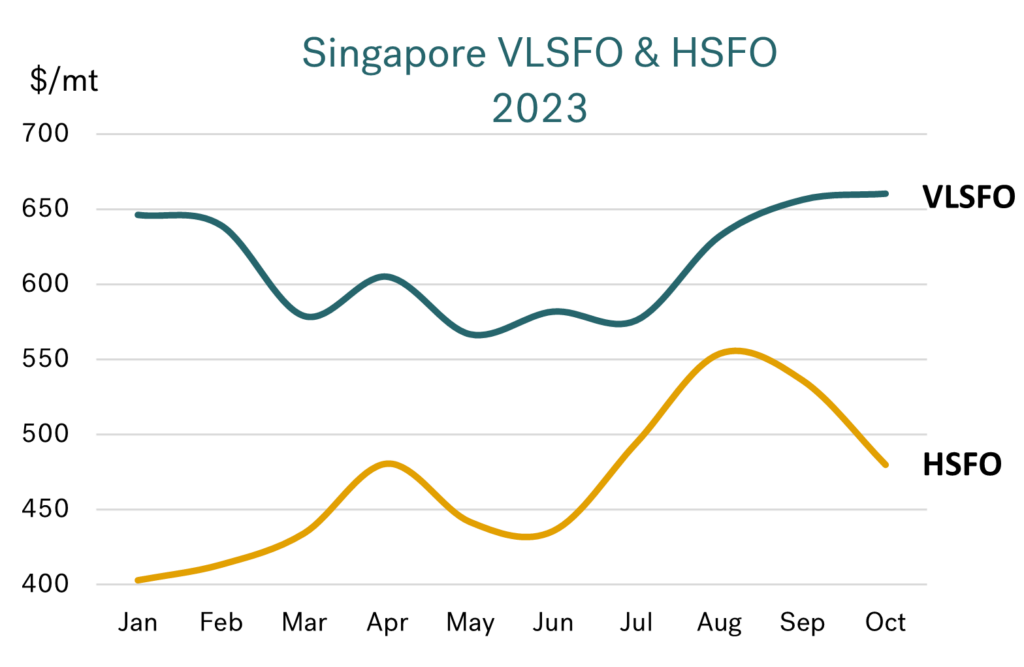
In complete contrast to VLSFO, average prices for HSFO have fallen!
Unlike VLSFO prices closely tracking crude and moving higher over recent months, there has been a turning point in the HSFO market and prices have actually fallen. Whereas monthly average Singapore VLSFO prices are now $30/mt higher than in August, Singapore HSFO prices are $70/mt lower!
Source: Integr8 Fuels
VLSFO and HSFO go in different directions
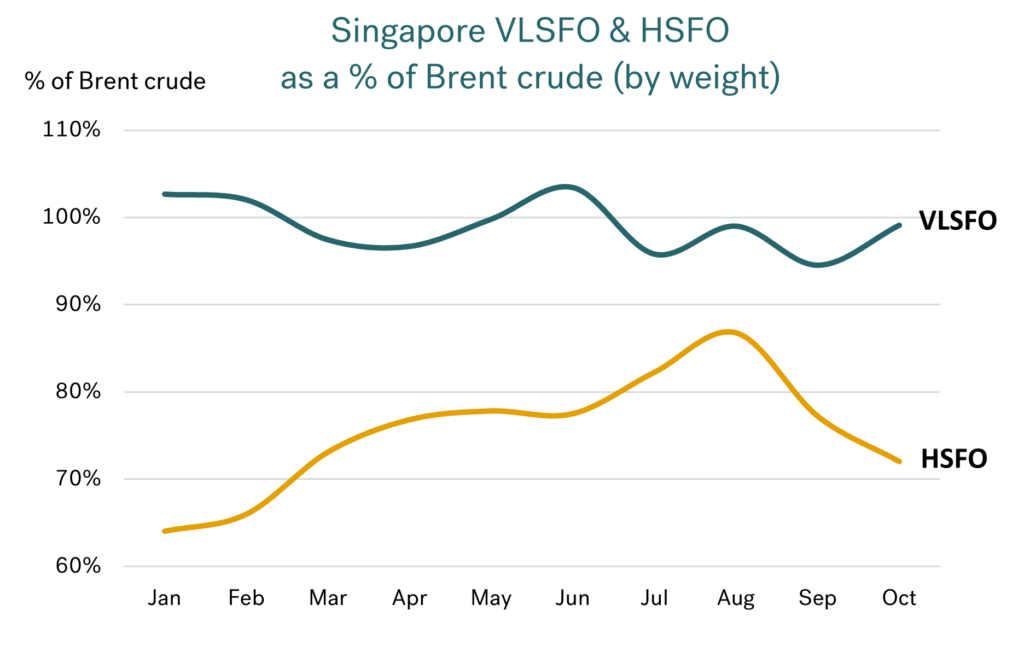
From the initial analysis, Singapore VLSFO closely tracks crude, so it is no surprise that the price relationship between these two are consistent. In fact, Singapore VLSFO is priced at close to 100% of Brent (on a weight basis) and this year has only varied within a very narrow range of 95-103%. If you go back three years, the relationship has been consistently tight and VLSFO has been within the 95-108% range of Brent in all but three months.
Source: Integr8 Fuels
This is in complete contrast to HSFO pricing versus crude. Taking Singapore HSFO as a benchmark, its percentage of Brent shifted from around 65% at the start of the year to close to 80% by mid-year. It is no surprise that the HSFO/Brent relationship strengthened even further in July and August to close to 90%, as Saudi Arabia and Russia made additional, voluntary cuts in crude production/exports totalling 1.5 million b/d (all of which are medium and heavy grades). Consequently, HSFO supply was always going to be squeezed and its relative price likely to rise.
With statements that the Saudi (and Russian) production cuts would run through to the end of this year, it might have been the case that HSFO prices would continue to be supported, at least going into the fourth quarter. This hasn’t happened, and HSFO prices have already fallen sharply despite the Saudi Arabia and Russia strategy and heightened geopolitical risks in the Middle East.
Why has HSFO fallen relative to Brent?
HSFO pricing was always expected to weaken versus Brent, not least in anticipation of the rise in Saudi and Russian crude exports from January. However, the shift has been ‘early’ and the key trigger for the turnaround has centred on the Middle East and a recent substantial increase in HSFO exports.
HSFO is used in a number of power-generating plants in the Middle East and demand is high in the region during the summer months to meet air conditioning demand. As temperatures eased in October, ‘local’ demand for HSFO fell back. Consequently, HSFO exports from the UAE moved from virtually nothing in September, to indications of around 3 million bbls going to Singapore in the middle two weeks of October. On this basis we could expect the seasonal pattern of continued HSFO exports from the UAE until power-generating demand increases again Q2 next year.
In addition to this seasonal shift, there has also been a structural change in HSFO exports from Kuwait. Like the UAE, Kuwait has been burning HSFO in its power generating sector, with supplies coming from their domestic refineries as well as imported volumes. However, with the phased introduction of the massive, 615,000 b/d Al Zour refinery from late last year, it was always planned that the country would switch to using lower sulphur fuel oil as part of its Environmental Fuel Project (EFP). This is now in place and the agreement is for Al Zour to supply up to 225,000 b/d of low-sulphur material to the Kuwait Ministry of Electricity as part of their cleaner energy program.
This has therefore ‘freed-up’ Kuwaiti HSFO for export and also removed them as a buyer of HSFO from the international market on a permanent basis. These ‘additional’ HSFO volumes are moving to Asia and are another contributing factor to a weakening HSFO price.
It all means a widening VLSFO – HSFO price differential
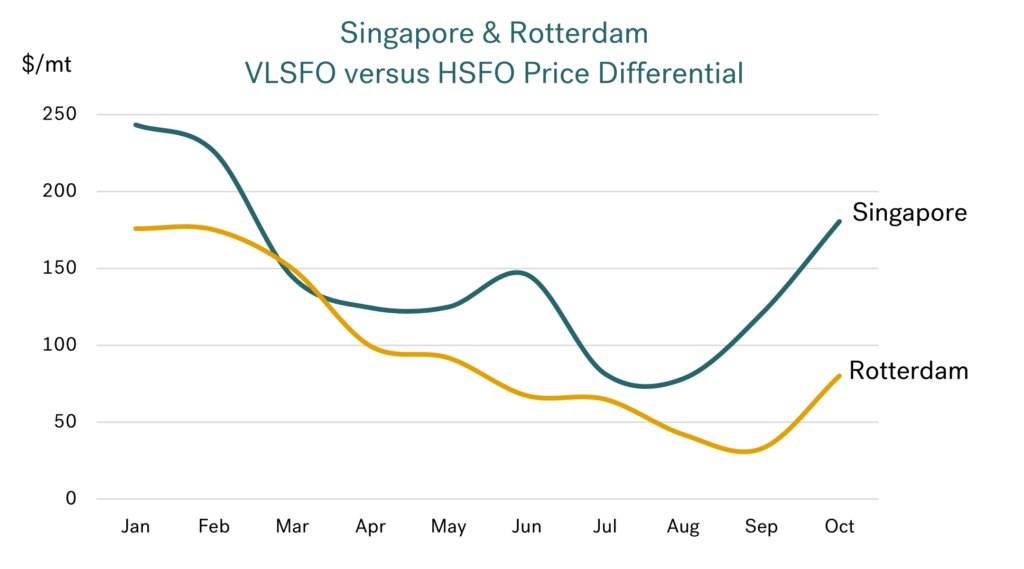
Looking at the VLSFO and HSFO markets, it is clear the price spread between the two products has widened. With ‘incremental’ HSFO volumes available in the Middle East and moving into Singapore, the widening has been greater in these two bunker regions.
This has meant the VLSFO – HSFO spread in Singapore has shifted from an extreme low of only $80/mt in July and August to an average of $180/mt in October. This is still not back to levels seen at the start of this year, but the advantages for scrubber-fitted ships are clearly far better than they have been since March.
Source: Integr8 Fuels
The price spread in Fujairah is very close to the Singapore differential, at around $175/mt in October. However, since the Russian invasion of Ukraine and the resulting ban on Russian products entering Europe (halting a substantial flow of HSFO), the VLSFO – HSFO price spread in Europe has typically been far smaller than in the Middle East and Asia. So, although the spread in Europe has widened, in Rotterdam it has only moved out to $80/mt in October, $100/mt less than in Singapore!
What next?
With the shifts in the HSFO pricing and additional heavier crudes expected to enter the market from the start of next year as Saudi Arabia and Russia remove their voluntary production cutbacks, we can expect ongoing relative downwards pressures on HSFO prices. In the near term, it remains to see what the geopolitical risk is on crude prices, which in turn will largely determine VLSFO pricing. Now the VLSFO – HSFO spread is far more attractive for owners of scrubber-fitted ships in the Middle East and Asia.
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
Robust regulation and licensing key to ensuring ARA’s mass flow meter mandate is a success
October 24, 2023
On 19 October, the Port of Rotterdam and Antwerp-Bruges Port Authority officially confirmed that Mass Flow Metres (MFM) will become compulsory in Rotterdam, Antwerp and Brugge ports from January 2026. International bunker trading company Integr8 Fuels welcomed the announcement but emphasised that robust regulatory and enforcement protocols will prove critical in order to build confidence in the system. Read More
The initiative is a positive step towards much needed transparency, but scepticism remains without clarification of enforcement protocols.
On 19 October, the Port of Rotterdam and Antwerp-Bruges Port Authority officially confirmed that Mass Flow Metres (MFM) will become compulsory in Rotterdam, Antwerp and Brugge ports from January 2026. International bunker trading company Integr8 Fuels welcomed the announcement but emphasised that robust regulatory and enforcement protocols will prove critical in order to build confidence in the system.
A report from IBIA and BIMCO in May 22 showed that while strong support exists for licencing schemes, mass flow metering, and the transparency this brings between suppliers and receivers, only 80% of those surveyed trusted a correctly installed, certified, and used MFM.
Chris Turner, Bunker Quality & Claims Manager for Integr8 explained “The announcement is great news, but we must also commit to a transparent model strictly aligned to ISO 22192, with the ability to appropriately enforce and sanction. Without this, even with Mass Flow Meters being mandatory in these ports, endemic mistrust will remain, and the opaque nature of supply will persist in the eyes of many.”
Singapore – The Gold Standard
Singapore’s MFM roll-out could serve as a model for the ARA, Chris points out. The best practices achieved in Singapore was a result of an industry-wide initiative and has been underpinned by government support and regulatory enforcement.
Singapore’s approach has been to strive for best practice and deal with poor performance. Its MFM system reduces the chance of manipulation through the following measures:
• A robust Maritime and Port Authority of Singapore approval process
• Application of the SS 524:2021 quality management standard
• Sampling at the vessel manifold
• Traceable calibration
• Consistent documentation
Supported by robust enforcement, the model encourages dispute reporting and performance reviews, with demerit points and possible loss of licenses as penalties for non-compliance.
Licensing Benefits – Improved Compliance
Integr8 data shows that in the last 180 days there were significantly fewer quantity claims in Singapore than the global average (0.9% of Singapore volume vs 1.6% globally).
Chris continued: “Let’s not forget, many of the alternative fuels will be even more expensive, exacerbating potential hidden losses. With carbon taxes and emission trading schemes approaching, it’s even more important for fuel users to have reliable data and the use of MFMs contribute to that.”
Not only do MFMs significantly reduce the likelihood of hidden loses, but the numbers continue to support licenced MFMs when it comes to VLSFO sulphur compliance. Data available to Integr8 shows that Singapore’s system appears to go a long way in lowering the chance of sulphur over 0.50% being reported (a x6 reduction compared to ARA), and allegations of sulphur breaching the carriage ban (also a x6 reduction compared to ARA).
All this suggests that if a commitment is taken to drive the quality systems to the right level, MFMs and licencing can have a significant benefit to disputes, hidden losses and quality issues, including critical MARPOL non-compliance.
“We have a super chance to make a lasting difference in the supply landscape, let’s seize it.” Chris concluded.
Contact Chris Turner:
Email: chris.t@integr8fuels.com
Dubai Tel: +971 4424 0700
Dubai Address: 2901 Silver Tower, Cluster I P.O. Box 214434, Jumeirah Lake Towers, Dubai