A Wild Ride for Oil Prices—Biden, Trump, and What Comes Next
November 20, 2024
View this article as a PDF » Singapore VLSFO 20% lower than 12 months ago Singapore VLSFO prices have fallen even further over the past month, to their lowest levels since last June. The driving force behind this continual slide in prices is the bearish fundamentals… Read More
Singapore VLSFO 20% lower than 12 months ago
Singapore VLSFO prices have fallen even further over the past month, to their lowest levels since last June.
The driving force behind this continual slide in prices is the bearish fundamentals in the oil market. There have been short-term ‘interruptions’ in this decline, largely from war-related developments in Ukraine/Russia and Gaza. Though the market has continually come back to focus on the bearish oil fundamentals outlined for this year and next year, especially by the IEA.
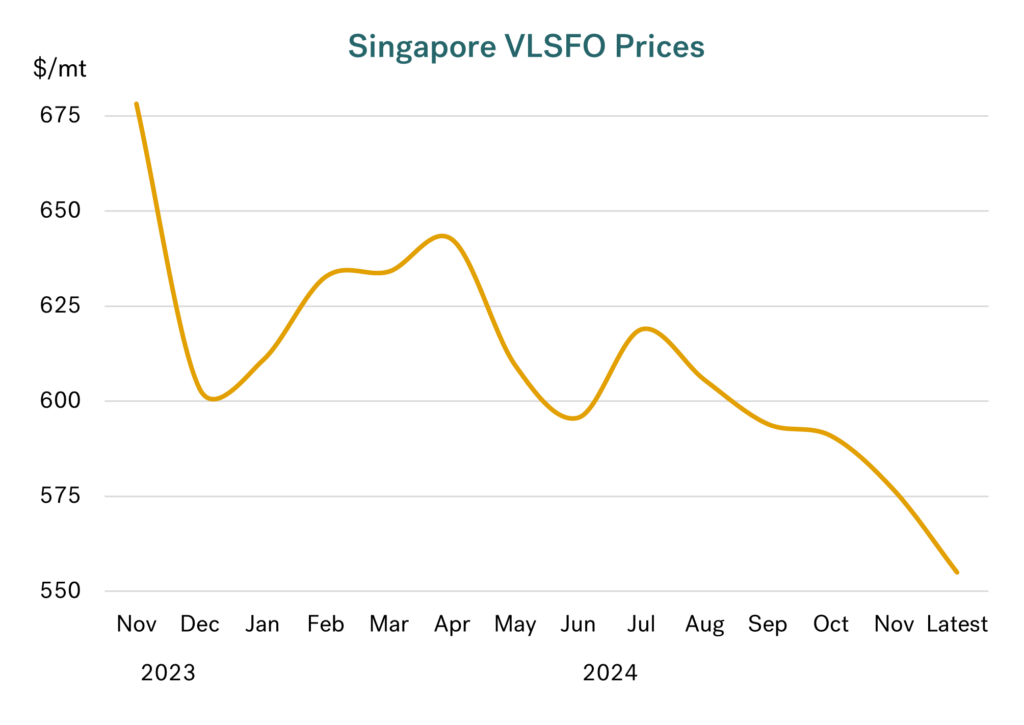 Source: Integr8 Fuels
Developments in the Russia/Ukraine war have not (so far) been enough to reverse the fall in prices. Hence Singapore VLSFO is $50/mt lower than 3months ago, and has fallen by around $125/mt (close to 20%) over the past 12 months.
Rotterdam prices also lower
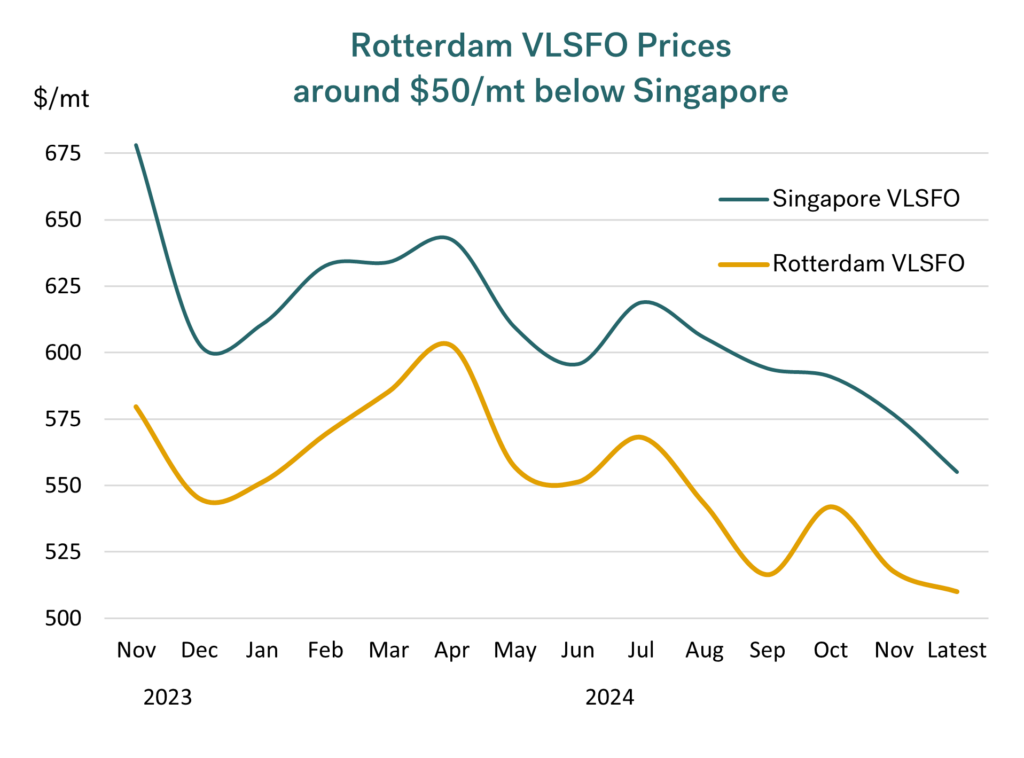
The same price movements have been seen across the bunker world, and in other product markets as well. The graph below illustrates VLSFO prices in Rotterdam, which generally follow the same trend as in Singapore (apart from in September, when there was tightness in the Singapore market). Consequently, Rotterdam VLSFO prices are now just above $500/mt, and back to around $50/mt below those in Singapore.
 Source: Integr8 Fuels
It all comes back to crude
Everything ultimately comes back to the crude oil price, and the benchmark references we all use are Brent and WTI futures prices; the whole industry feeds off these prices. So, the starting point for us is Brent, and the graph below is more-or-less the same illustration we have highlighted for VLSFO above; there are of course important nuances in bunker prices, but here we are just focusing on the bigger picture.
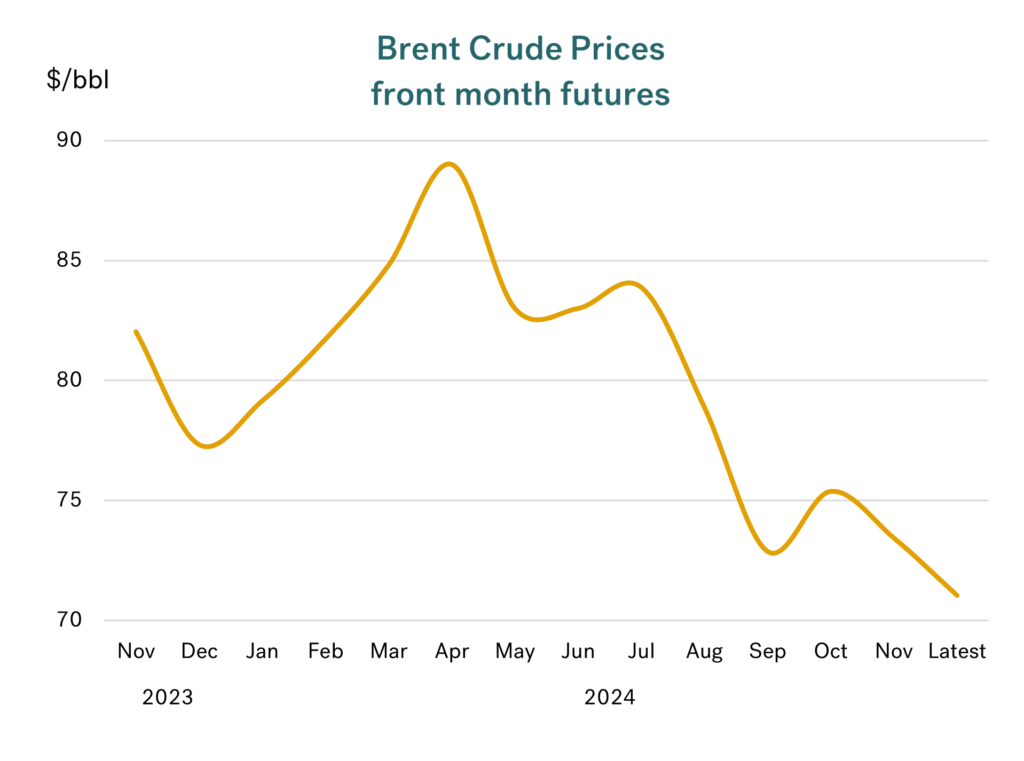 Source: Integr8 Fuels
There are always three things to assess!
Two big things to look at now are the Russia/Ukraine war, and anything that OPEC+ does. But we must also include any significant changes that newly elected President Trump implements, including bringing the Russia/Ukraine war to an end and possible higher trade tariffs against China.
However, before Trump is inaugurated, it seems President Biden is potentially making one last big move for Ukraine, with the provision of long-range missiles able to strike well into the Russian interior. This may also be a trigger for European allies to offer ‘more-powerful’ weapons to Ukraine. These comments have already pushed oil prices a little higher.
What will it take to push bunker prices even lower?
So, if long-range missiles are available to Ukraine, it is likely to mean oil prices go higher; but a Trump ‘solution’ to the war will mean prices go lower. At this stage no one knows where this will go, but it won’t be difficult to follow, it will be all over the front pages!
We can only sit and wait to see what happens in Russia/Ukraine, but we can look more closely at the situation for OPEC+, and what that might mean for oil prices and us in the bunker market.
OPEC+ is in a difficult position in that it has planned to gradually unwind at least 2 million b/d of additional voluntary cutbacks, but has said this is dependent on market conditions. With oil prices falling, the market conditions for OPEC+ ‘have not been met’, so they have continually deferred any decision to increase production, despite some individual members pushing to raise output. The latest decision is to potentially start ramping up production in January, adding around 180,000 b/d each month.
There is already strong growth in non-OPEC+ production projected for next year. Therefore, if OPEC+ does go ahead and unwind their production cuts, world oil supply could increase by more than 3 million b/d in 2025. This is against a projected increase in oil demand of only 1.0 million (by the IEA). The graph below illustrates the massive difference between the supply and demand increases next year, with the implication of a much weaker oil market and even lower oil and bunker prices.
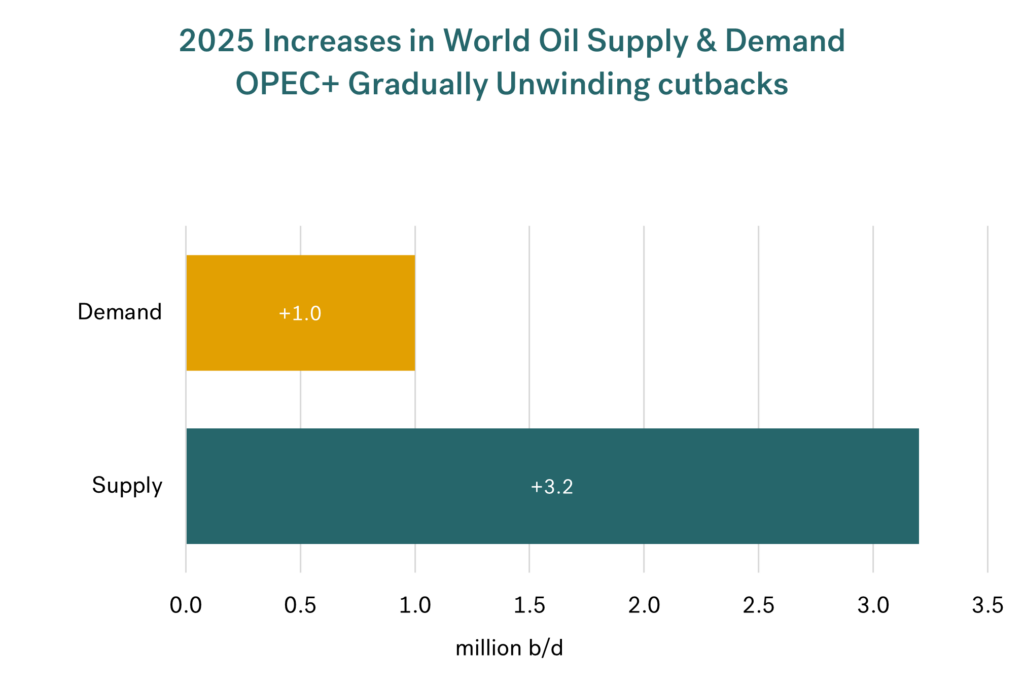 Source: Integr8 Fuels
The IEA is at the lower end of demand forecasts for next year, but even looking at the US EIA and OPEC themselves, they only indicate a demand growth of 1.2 million b/d and 1.5 million b/d respectively. So even here, it still shows a large imbalance and infers weaker bunker prices.
Even if OPEC+ does continue to defer any decision to unwind the cutbacks for the whole of next year, it still suggests that world oil supply will increase by 2 million b/d. Again, taking any of the main forecasters’ views on demand for 2025, it still implies ‘too much oil’, and a potential further fall in bunker prices.
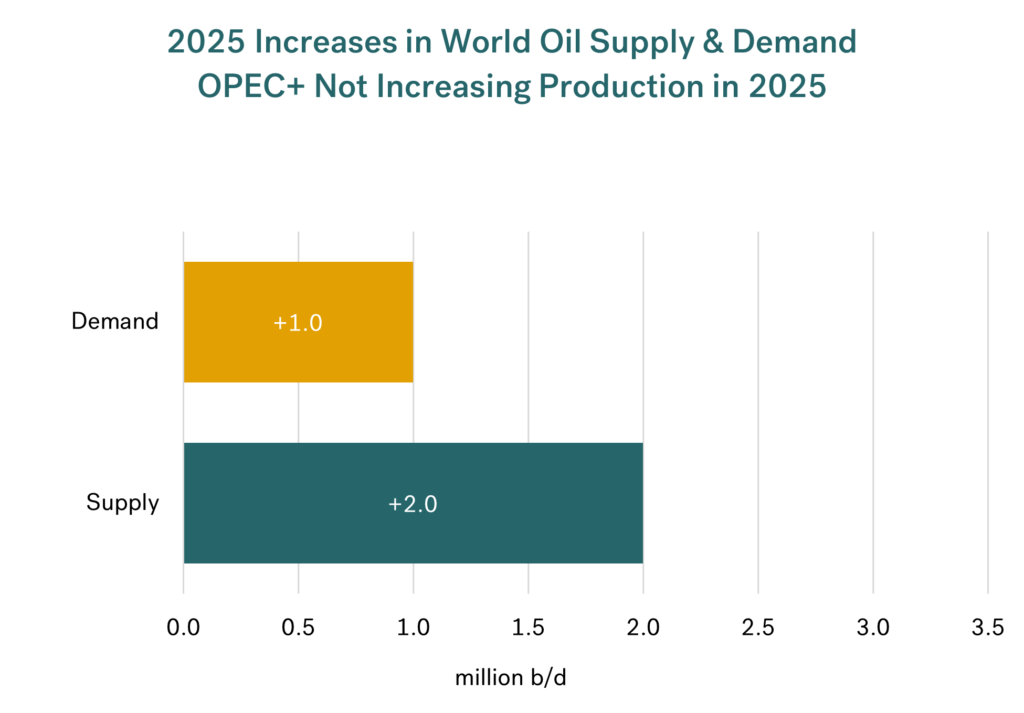 Source: Integr8 Fuels
Looking at the fundamentals, the only ‘balanced’ outlook for next year is if OPEC+ make a further production cutback of around 1 million b/d!
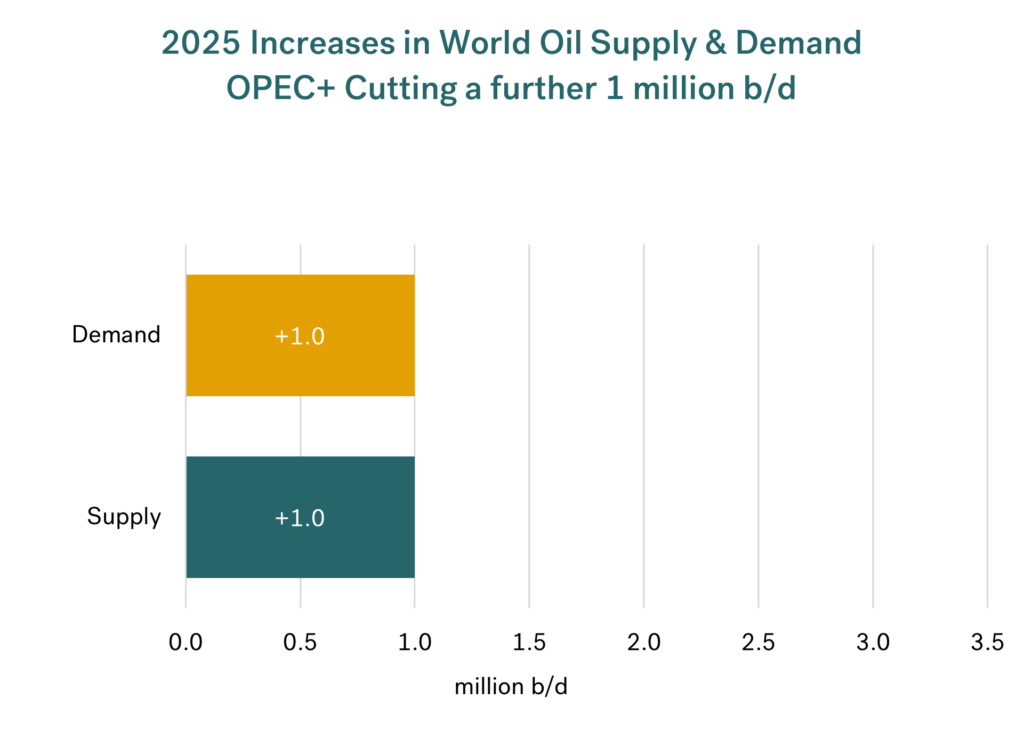 Source: Integr8 Fuels
Given that OPEC+ is talking about increasing production, at this stage it seems highly unlikely they will make a quick decision to impose further cuts.
The fundamentals & Trump could mean even lower bunker prices in 2025
So, from a purely fundamental view, everything points to sustained ‘low’ prices next year, and if OPEC+ is not prepared to make further cuts then there is every indication that oil and bunker prices could be even lower in 2025.
BUT we are not in a purely fundamental market, and in geopolitical terms it is Russia/Ukraine that is at the forefront. If Biden’s latest move on long-range missiles is carried out, then prices are likely to rise, even if its in anticipation of an escalation in the war. However, from the early part of next year we may see far more unpredictable outcomes under President Trump. If the war does come to an end, and OPEC+ increase, or even maintain output, then VLSFO prices in the $500s may look high!
Let’s watch Biden, Trump, and OPEC+ to see what happens.
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
The IEA’s latest long term energy report shows a potentially bigger bunker market going forward
October 23, 2024
View this article as a PDF » The IEA report is another influential study for us to consider Three months ago, we highlighted BP’s analysis of the longer-term oil industry and the implications for the bunker market, taken from their ‘Energy Outlook’ report to 2050. Last… Read More
The IEA report is another influential study for us to consider
Three months ago, we highlighted BP’s analysis of the longer-term oil industry and the implications for the bunker market, taken from their ‘Energy Outlook’ report to 2050. Last week the IEA published their long term ‘World Energy Outlook’ to 2050, taking another look at how things could pan out under three different scenarios.
Here we take a dive into what this could mean for the oil industry, and then specifically what they are saying about shipping and the potential impacts on our markets for bunkers.
We know major changes will happen
There is a clear global direction away from oil (and other fossil fuels). The IEA report highlights this, plus the ongoing electrification of the overall energy system, and that clean electricity is the future.
Coming down to the more micro-level of shipping (and aviation), the IEA recognises that we are in a difficult industry to eliminate hydrocarbons. The phrase they use is that we are in a “hard to abate” sector.
Two scenarios showing a possible range, and a case to get to net zero by 2050
The three IEA scenarios are labelled as follows:
Stated Policy case – The course we are on based on policies and technologies currently in place.
Announced Pledges case – If all government/industry pledges and targets are met in full and on time.
Net Zero by 2050 – A path that would achieve net zero by 2050, limiting global warming to 1.50C
Oil is in decline: other energy forms (and efficiencies) will take over
There are a whole host of challenges to meet environmental targets, but the starting point is the world still ‘wants’ more energy. Economic growth in the developing and emerging economies, and the global population forecast to grow from 8.1 billion now, to 9.7 billion by 2050 (up 20%) are a testament to this.
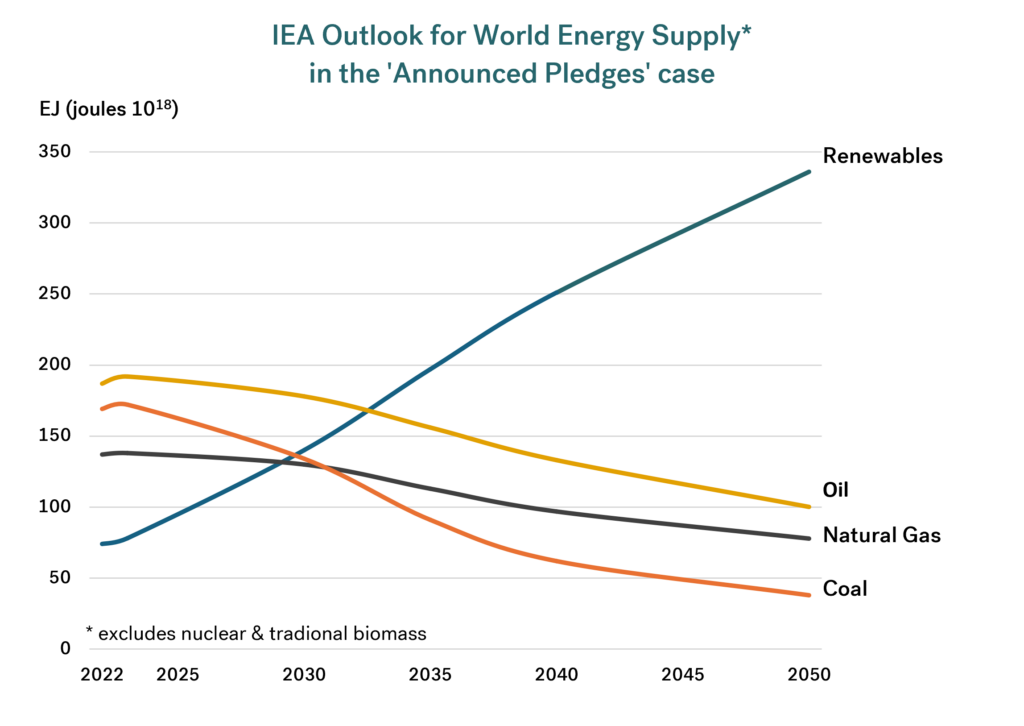
However, by the next decade this growth will be ‘fuelled’ without using more oil, natural gas, or coal, i.e. we only 6-7 years away from peak fossil fuel demand. Renewables (largely to produce electricity) and energy efficiency will be the new bywords in energy demand. The graph below illustrates the scale of these changes from fossil fuels to renewables and electricity under the IEA’s ‘Announced Pledges’ case.
 Source: Integr8 Fuels
What is happening to oil demand?
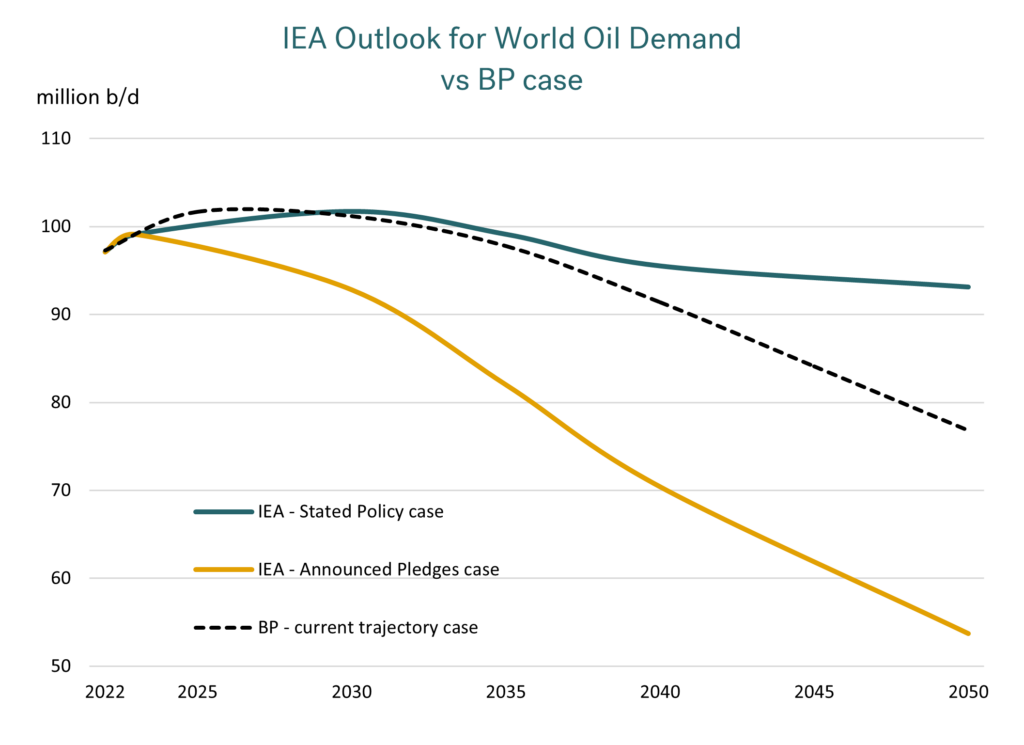
In the IEA’s ‘Stated Policy’ case, world oil demand remains just above 100 million b/d through to the early 2030s, and then only falls to around 93 million b/d by 2050. In terms of the discussion, this is likely to be at the very high end of oil demand forecasts. There is an expectation that more governments, industries, companies, and individuals will move towards greater environmental commitments, not least as the cost structure of new technologies is reduced.
The IEA’s second scenario, the ‘Announced Pledges’ case, reflects everyone actually doing what they have said they will do, and doing it on time. This illustrates a case where oil demand would fall to around 50 million b/d by 2050, half the size it is today and clearly a radical change in the market.
A ‘reality’ case may be somewhere between the two lines shown by the IEA, and this is where BP put their ‘Current Trajectory’ case three months ago (see graph below).
 Source: Integr8 Fuels
What would net zero by 2050 mean for oil?
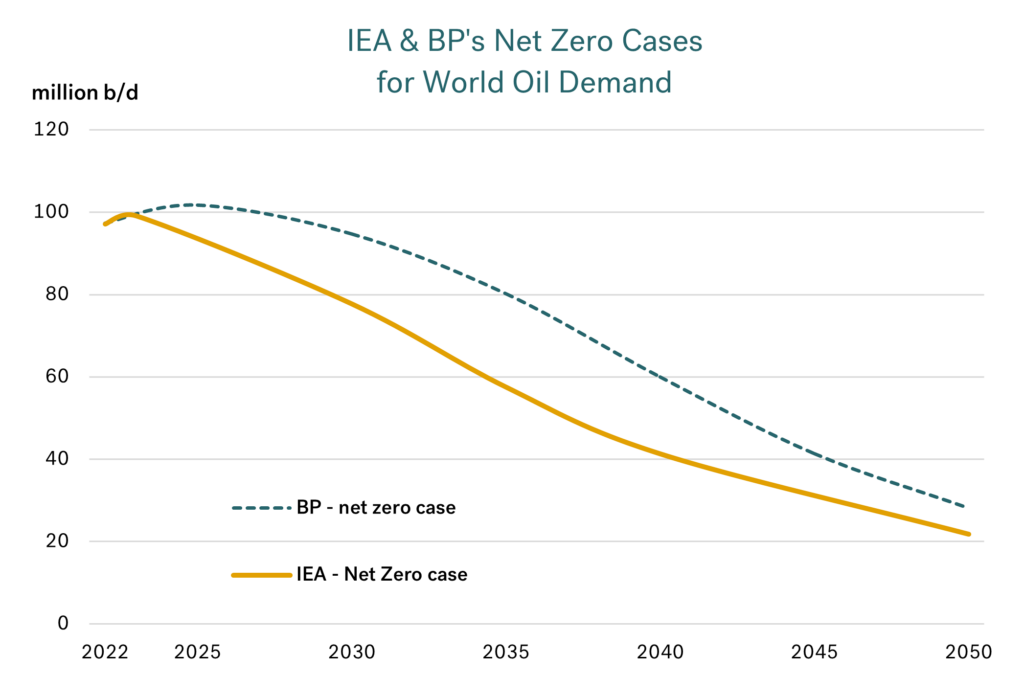
The ‘Net Zero’ case put forward by the IEA (and by BP) illustrate the kind of ‘oil world’ we would have to be in to achieve net zero by 2050. These are not forecasts, and at this stage seem highly unlikely to be achieved by 2050.
 Source: Integr8 Fuels
However, they still show the very credible implications for the oil industry at some stage in the future, based on the global moves away from fossil fuels. In both the IEA and BP scenarios we get to an oil industry of only 20-25 million b/d in a ‘Net Zero’ world. This is not a viable market size to maintain scaled-up oil infrastructure across the globe, and illustrates the direction the oil industry, and the oil bunker markets are going in the longer term. It just re-iterates the case that we must gear up for change.
We are in one of the ‘more difficult’ oil sectors
In all of this analysis, electrification is a key means of reducing CO2 emissions, and will play an enormous role in industry, buildings, and road transportation. However, for us in shipping (and in aviation) there is no obvious, easy, or low cost means of using electricity to power our needs. The IEA states that we are in “hard to abate” sectors, and that hydrocarbons will continue to play the leading role. However, they also state that we will go through significant policy changes (through the IMO and the EU) to decarbonise our market and this is assumed to be through biofuels, ammonia, methanol, hydrogen and hydrogen-based fuels, other low emission fuels, plus greater efficiencies being imposed.
Now for the good news!
There is a huge amount of analysis that goes into this IEA report, starting with economic forecasts and moving all the way through government/institutional policy, industry and consumer responses and ultimately ending up with a demand figure for distinct types of energy in each of the sectors.
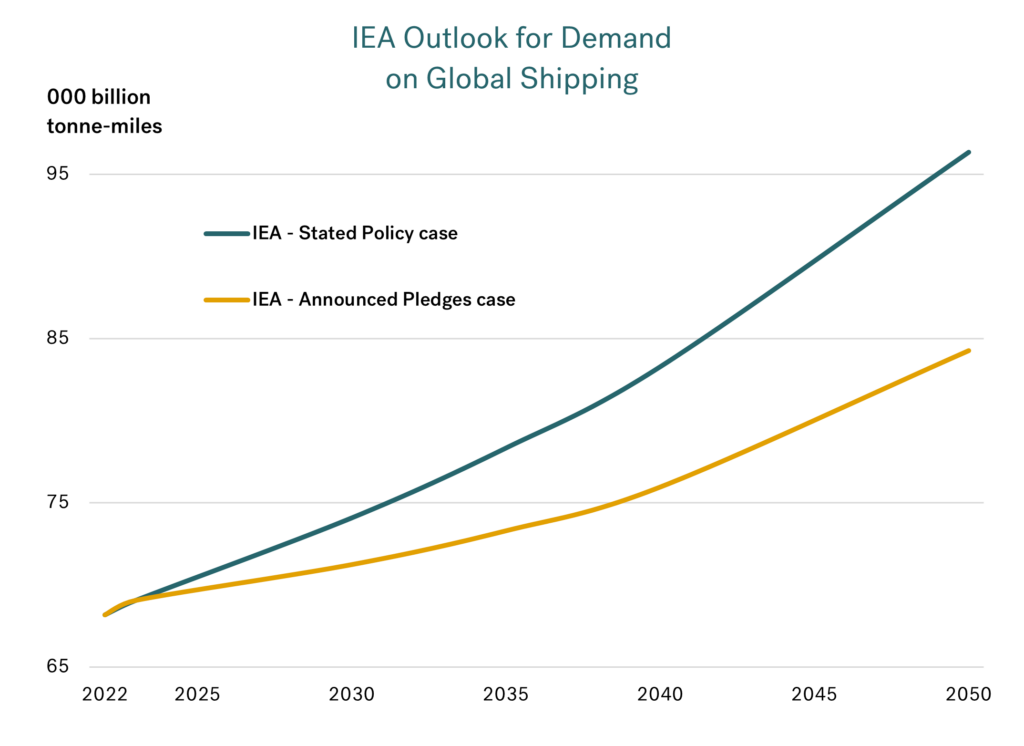
Within this work the IEA calculates the demand on shipping under their three different cases, and put a tonne-mile (or tonne-kilometre) figure on this. The graph below illustrates their tonne-mile demand for shipping in the ‘Stated Policy’ and ‘Announced Policy’ cases (the ‘Net Zero’ case being highly unlikely in the time-frame to 2050).
 Source: Integr8 Fuels
The IEA’s ‘Stated Policy’ case shows the tonne-mile demand for shipping rising by more than 35% by 2050. In their ‘Announced Policy’ scenario they show a gain of 20%. Working off a single, ‘credible’ case somewhere between these two scenarios would indicate a rising shipping requirement of around 25-30% over the next 25 years.
Although growth in the bunker market is likely to be less than this, with efficiency gains, we are still likely to be in a growth sector!
Conclusions are: Adapt, Change, and move into a bigger market!
We are in an industry where it is harder to use the existing technologies of electrification to achieve decarbonisation, but we will be pushed along decarbonising policies; we must adapt. And if the size of our market is getting bigger, then there could be more opportunities for us and other players/investors to get involved.
We have to continue to watch what is happening out there, in terms of fuels, technologies, developments and what people are doing. We can also have an influence. In this way we can be best prepared for the opportunities that will be there in a new, and potentially bigger bunker market.
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
We are at a 3 year low in prices, but not for VLSFO in Singapore!
September 25, 2024
View this article as a PDF » Crude prices have fallen to 3-year lows In the monthly reports this year we have often highlighted the bearish fundamentals within the oil industry, especially those from the IEA. The IEA has for some time been forecasting very low… Read More
Crude prices have fallen to 3-year lows
In the monthly reports this year we have often highlighted the bearish fundamentals within the oil industry, especially those from the IEA. The IEA has for some time been forecasting very low growth in global oil demand for this year. Last month we also emphasised the shift in analysts’ views from a bullish to a bearish outlook on prices for 2024/25. These bearish fundamental views are certainly being fulfilled at the moment.
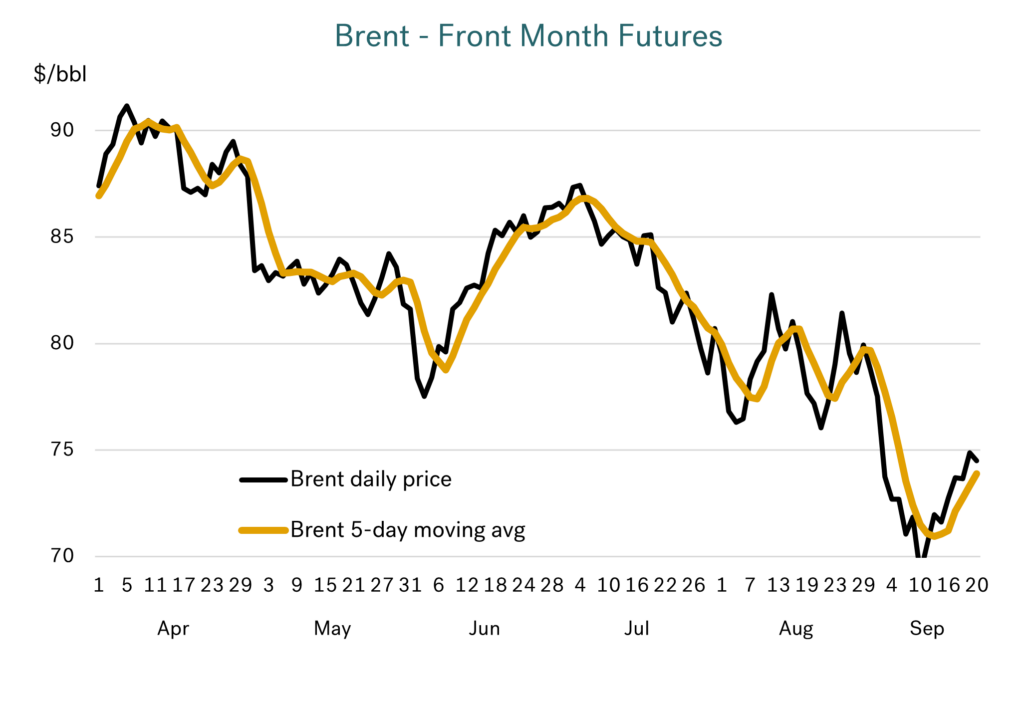
The graph below illustrates the downward moves in Brent crude prices over the past 6 months, falling from:
- around $90/bbl in April;
- to the $80s in May, June and July;
- to just below $80/bbl in August;
- and now into the low $70s (after falling to just below $70/bbl, its lowest since December 2021 – almost 3 years).
 Source: Integr8 Fuels
This equates to a 20% fall in crude prices since April and has taken place despite heightened tensions in the Middle East, relatively low oil stocks and OPEC+ recently deferring any increase in production by at least 2 months, until December.
The bearish fundamental signals are currently dominating the market and are clearly strong enough to overcome all the other political, war-related and OPEC+ factors!
Rotterdam VLSFO prices have tracked crude
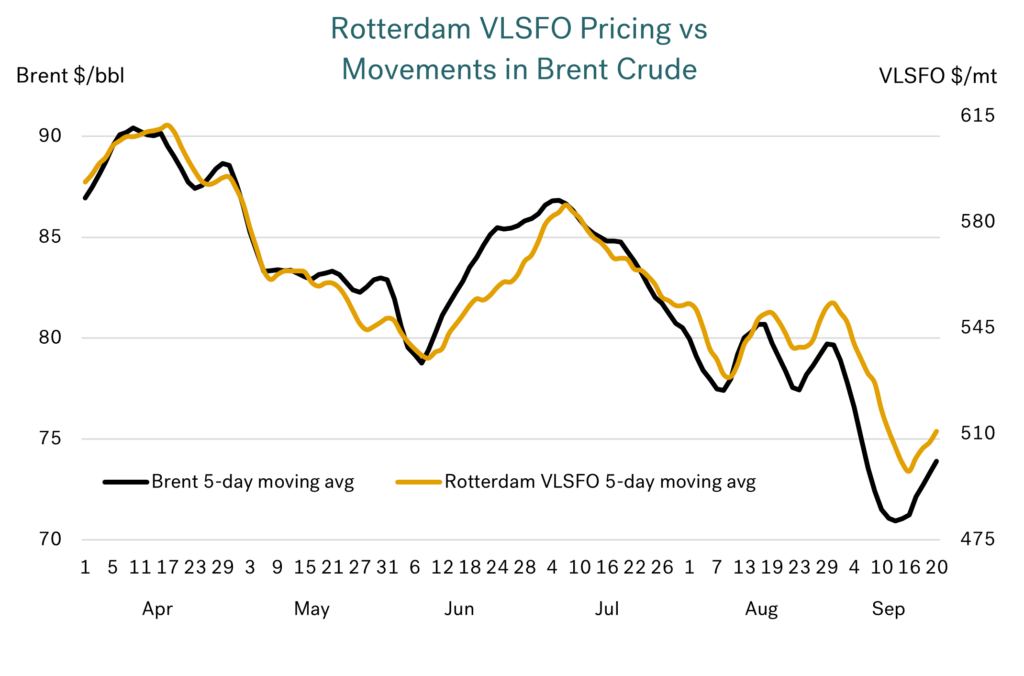
For us, the focus is what is happening to bunker prices, and the ‘easiest’ analysis is in the Rotterdam VLSFO market. Here, these bunker prices have closely tracked the developments in Brent crude, such that earlier this month Rotterdam VLSFO prices dipped below $500/mt and have been at their lowest for some 3 years. Current prices are slightly higher, at around $520/mt, but are still tracking the bearish sentiment of the crude market.
 Source: Integr8 Fuels
Singapore VLSFO prices have bucked the trend
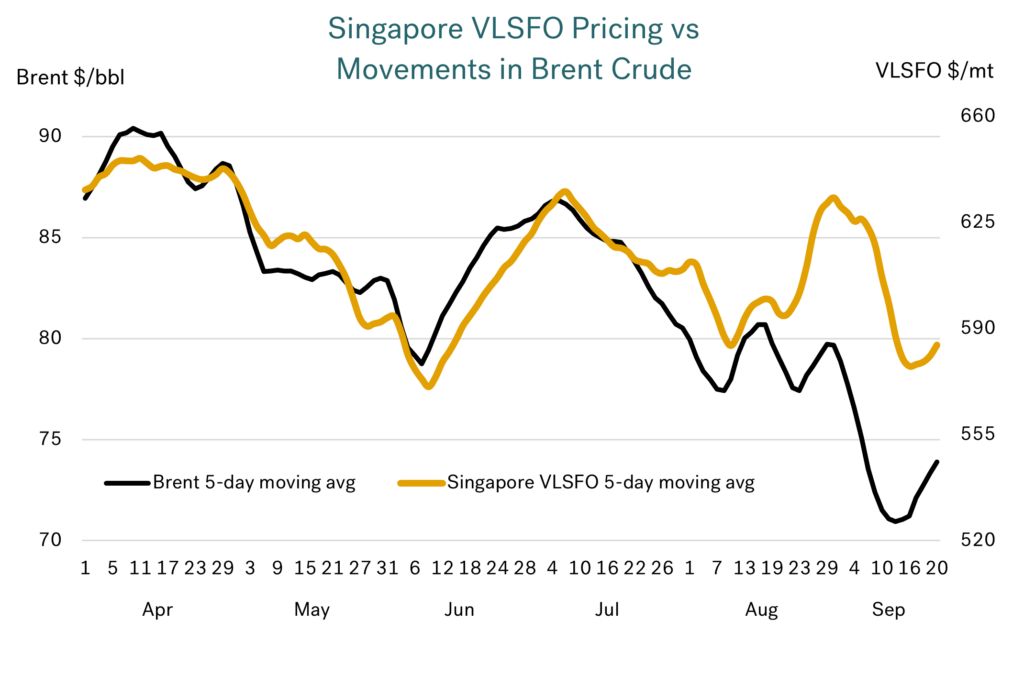
There is a different story when it comes to the VLSFO market in Singapore. Here prices were tracking crude between April and early August, but Singapore VLSFO prices have not followed the recent drop in crude and Rotterdam VLSFO prices to their 3-year lows. In fact, Singapore VLSFO has remained either side of $600/mt since May. Ordinarily, if Singapore VLSFO prices had tracked crude (as in Rotterdam), then we may have expected a more recent drop of some $50/mt, towards $550/mt. It never happened and it’s never that simple!
 Source: Integr8 Fuels
As outlined in our weekly market updates, VLSFO supply has been very tight in Singapore, with strong backwardation in prices and lead times of 10-13 days. This has meant Singapore VLSFO prices have been well supported and moved to a strong premium versus crude (and other products).
Any rebalancing in the Singapore VLSFO market should see prices re-align with crude and other product prices. If this takes place whilst oil prices generally remain under downwards pressures, then we could expect a substantial drop in Singapore VLSFO prices.
Looking at the bigger picture: It is China
As always, it is worth understanding what is driving the market at any given time; in this case it is China.
Economic growth in China over the second quarter this year is assessed at 4.7%, which is slightly lower than the official 5% target rate.
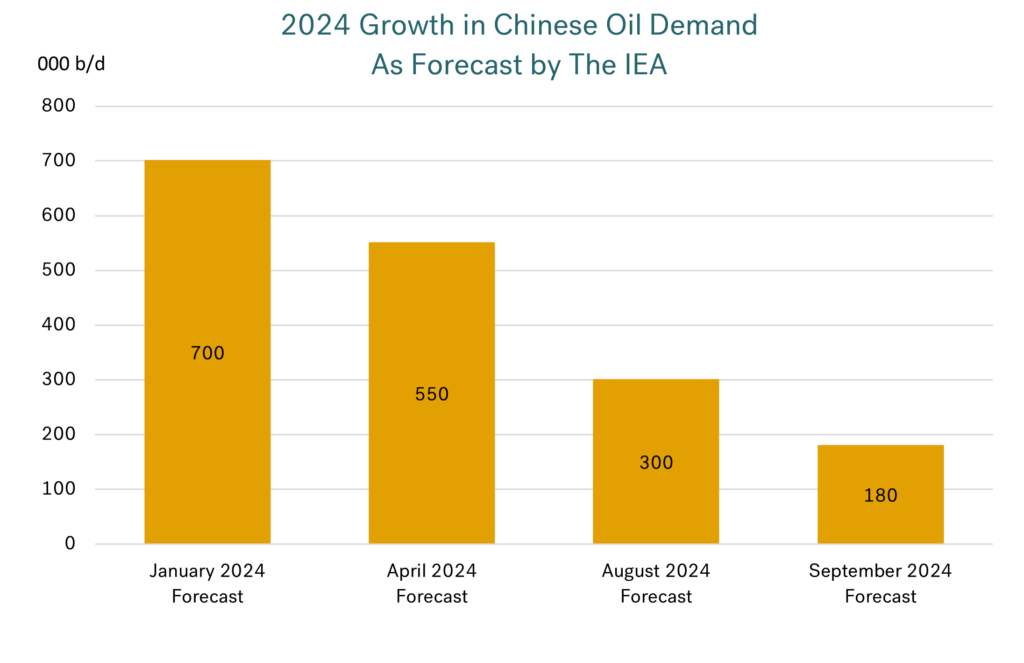
However, there have been massive downwards revisions to forecast growth in Chinese oil demand this year. Back in January the IEA forecast an increase of 700,000 b/d in Chinese oil demand for 2024. By April, expectations had dropped to a growth of 550,000 b/d this year, and by August growth in Chinese oil demand for 2024 was set at only 300,000 b/d. Though there has been another downwards revision this month, and the IEA now sees Chinese oil demand growing by just 180,000 b/d this year; massively different to expectations at the start of this year.
 Source: Integr8 Fuels
These ever-reducing expectations for oil demand growth in China is one of the key signals behind the current bearish sentiment and recent drop in global oil prices, to 3-year lows.
Getting more granular, the big changes in Chinese demand expectations have taken place in the naphtha and the gas/diesel oil sectors. Growth in Chinese naphtha demand is still positive, but has slowed, with delays in new petrochemical capacity coming onstream. However, Chinese gas/diesel is the most impacted product, with demand actually expected to fall this year. This is unheard of in the context of China’s meteoric rise as an economic powerhouse.
This decline in gas/diesel demand comes with weaker economic projections for the Chinese economy, major concerns about the property market and a greater use of alternative fuels in commercial road trucks.
The prospects for Chinese demand next year are equally low
Growth in Chinese oil demand next year looks equally constrained, with a forecast increase of around 250,000 b/d. Apart from higher volumes of LPG, ethane and naphtha going into the petrochemical sector, demand for all other main products looks like remaining near flat with 2024 levels. EVs already account for the majority of new car sales in China, along with an increasing number of ‘alternative’ trucks. This, plus the rapid expansion of an electrified high speed rail network (‘taking’ demand from domestic air travel), will limit any increase in the demand for gasoline, jet fuel and diesel in the next few years.
Looking further ahead, there are potential declines of close to 3% p.a. in the Chinese gasoline and diesel markets over the next 5 years, as the economy matures and the number of EVs continues
to increase.
Global fundamentals show no signs of higher oil prices
In the broader picture, cuts in global interest rates may signal some support and stimulate an element of growth in world oil demand; we did see a slight price hike when the US Fed cut interest rates for the first time in four years, by 0.5%. However, we are in a world where oil demand is flat-to-declining in the OECD countries, and growth is far less than it used to be in China.
Against these muted prospects for world oil demand, next year we are expecting strong increases in non-OPEC+ production and potential increases in OPEC+ production. These gains in supply are likely to be more than enough to put a cap on higher oil prices, even if oil demand is higher than expected.
Weak fundamentals versus threats of war
Today the risk of higher prices comes from heightened political tensions or war. It is this balance between weak fundamentals and the ‘war situations’ in the Middle East and Ukraine/Russia that the market is closely watching.
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
VLSFO prices are close to recent lows and could be even lower next year.
August 21, 2024
View this article as a PDF » VLSFO prices have rebounded though they are still close to recent lows. Since February, Singapore VLSFO prices have traded within the range $570-650/mt, and now are closer to the low of this range. Rotterdam prices have followed a very… Read More
VLSFO prices have rebounded though they are still close to recent lows.
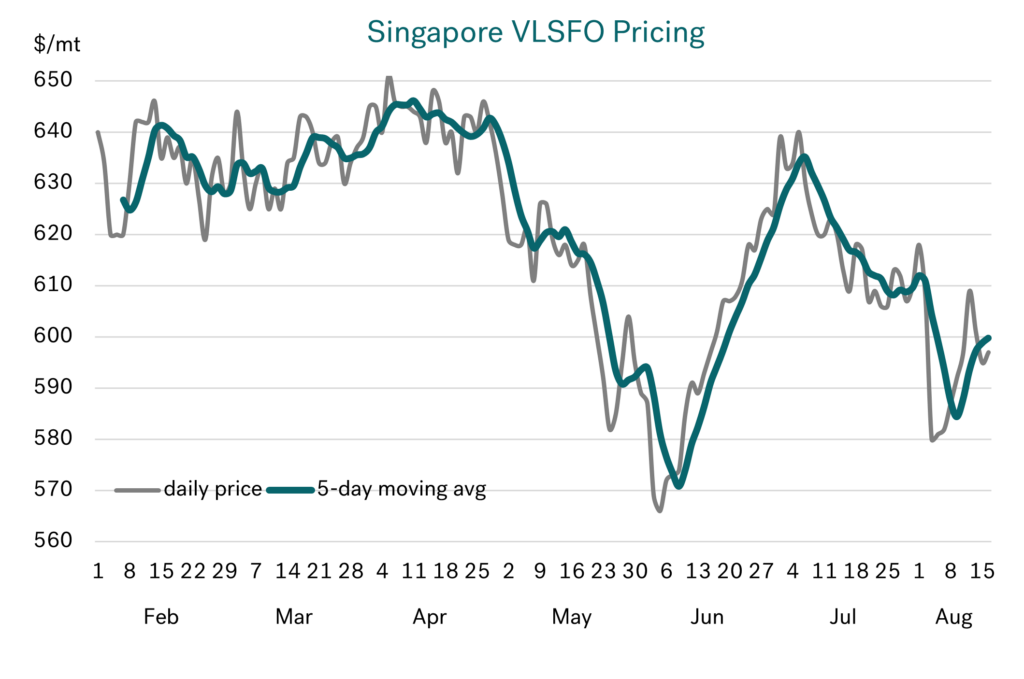
Since February, Singapore VLSFO prices have traded within the range $570-650/mt, and now are closer to the low of this range. Rotterdam prices have followed a very similar trend, but at around $50/mt below Singapore.
 Source: Integr8 Fuels
What have been the key recent developments?
We have previously highlighted the main driving forces behind these big changes in oil and bunker prices, with:
- The collapse in oil prices in May down to concerns about economic growth and weaker oil demand (especially in Europe), along with rising oil stock levels;
- The rise in June/July oil prices as ‘speculators’ aggressively bought back into the market after heavily unwinding positions in the previous month.
Since early July, prices have fallen back towards the lower end of the recent price range, as concerns about the US economy (based on unexpectedly weak employment data) triggered a sharp drop in global stock markets. However, these signals seem to have eased and stock markets and oil prices have rebounded over the past 1-2 weeks.
Crude prices are where we start
The starting point for all oil prices is ‘what is happening to crude’. For these reasons we always have to come back to the crude price, and in particular Brent and WTI futures on ICE and Nymex.
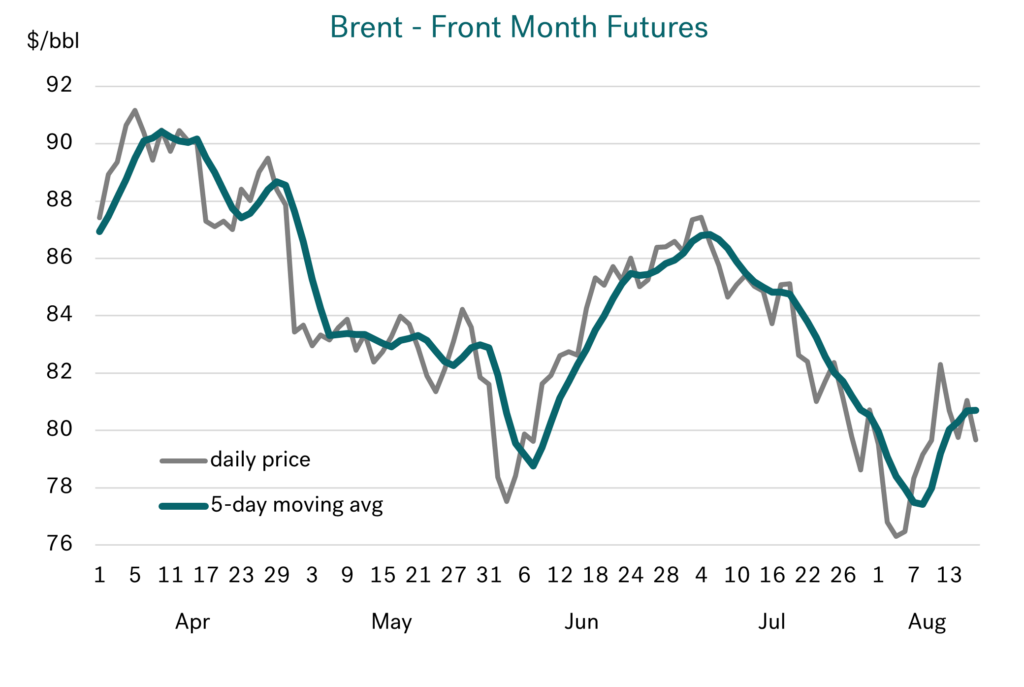
Over the past four and a half months, Brent front month futures have traded in the range $76-91/bbl, again with current prices just above recent lows and close to $80/bbl.
 Source: Integr8 Fuels
From the two graphs, the VLSFO price has closely tracked the same peaks and troughs as the Brent price.
What are the issues to look for going forward?
There are a lot of factors that can drive oil and bunker prices over the short term. Current geopolitical developments in the Middle East could push prices in either direction (ceasefire/continued war); at the time of writing there is more positive talk about a potential ceasefire between Hamas and Israel.
Similarly, the situation in Russia and Ukraine has the propensity to shift the market, although currently this seems to have taken a ‘back-seat’ in terms of oil prices.
Add to this the escalating rhetoric surrounding the November US presidential election, which is likely to create more noise in markets and prices.
However, it is often economic sentiment that can have a huge short-term bearing on prices, as we have just seen with US employment data triggering a bearish domino effect on to stock markets and commodity prices. Although prices have rebounded off these lows, there is still a nervousness about weak economic prospects in the US and China, which are the powerhouses behind global sentiment.
Given this, what are the prospects for oil demand next year?
There are variations in oil demand forecasts for next year, with the IEA forecast for growth at the low end of the range, at less than 1 million b/d. The US EIA forecast is higher, with 2025 demand growth at 1.6 million b/d, and OPEC’s forecast is even higher, at 1.8 million b/d.
Taking a ‘representative’ average of these bullish and bearish cases and looking at the year-on-year quarterly developments, this shows a stronger growth pattern through the second half of this year and into the first quarter of next year. However, even then, it only hits 1.4-1.6 million b/d. From the second quarter next year onwards, year-on-year demand growth is less and only forecast at just above 1 million b/d.
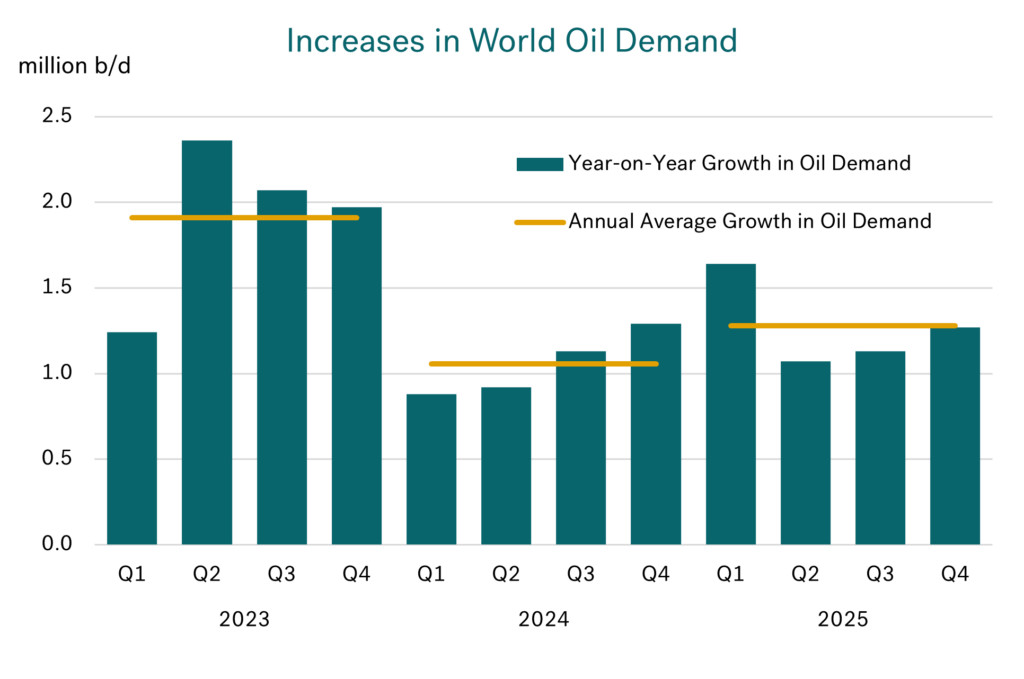 Source: Integr8 Fuels
Against this backdrop, non-OPEC+ production is forecast to increase by more than 2 million b/d through to the end of next year. This means that even if OPEC+ maintain their current voluntary and agreed production cutbacks through to the end of next year, the oil fundamentals will still weaken. If they start to unwind the cutbacks from October this year as planned, the fundamentals will be even weaker!
What does OPEC+ do in the circumstances?
A big question for the oil market is on OPEC+, and the ‘will they/won’t they’ question about starting to unwind their voluntary and agreed production cutbacks. This will clearly have a direct impact on oil and bunker prices.
The current plan was agreed in June and is for the 2.2 million b/d voluntary cutbacks to start unwinding in October, with the process continuing over the following 12 months through to September next year. If they go ahead, it will add 1.6 million b/d more oil from the Middle East, almost all of which are all high sulphur grades.
OPEC+ has stated that any unwinding of the cutbacks will be dependent on market conditions, and so if they are looking to at least maintain prices as close to current levels as possible, an extension of the current agreement well into next year would seem the outcome.
However, this is a collective OPEC+ agreement and so internal politics also play a role. If oil prices are falling and national revenues are ‘lost’, one way out is to produce more!
The question of market share also arises; with Saudi Arabia recently trying to defend its market by heavily reducing its formula prices for European buyers and making much smaller increases than expected for Asian buyers.
If OPEC+ does go ahead and raise production in October, this would send a very bearish signal to the market and oil prices are highly likely to fall.
All awaits OPEC+ on their decision, which could come next month, ahead of their next formal meeting on October 8th.
What are the crude price views for next year?
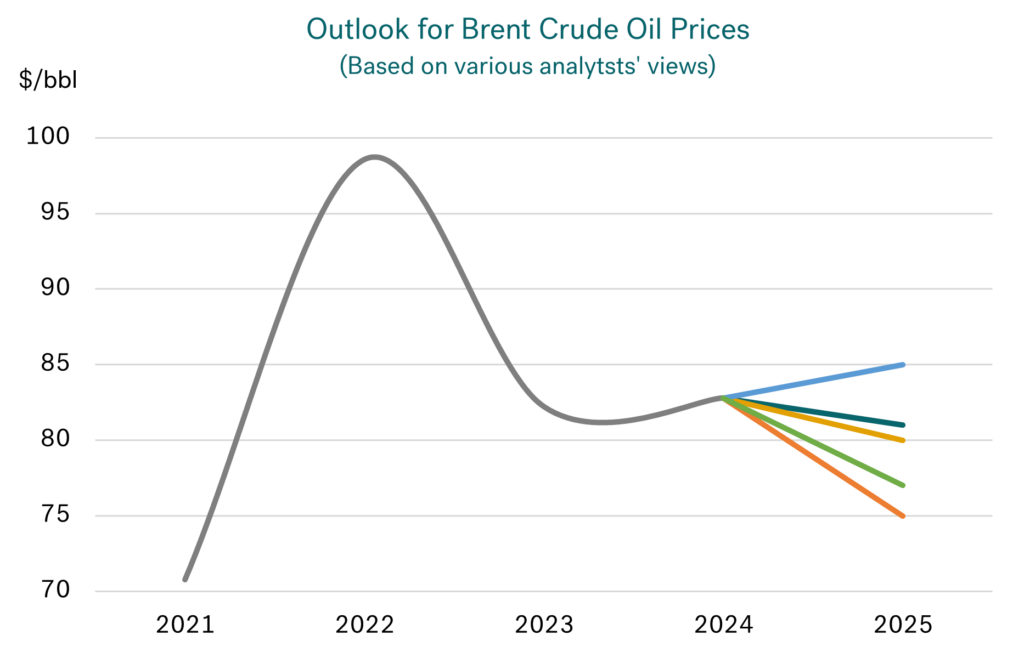
Given all these developments, most analysts have reversed their views from April this year, when they were typically forecasting a rising market in 2024 and Brent prices in the $85-90/bbl range. Now, four months later, most analysts are indicating lower expectations for this year, with Brent averaging $83-84/bbl, and a falling market in 2025, with Brent prices in the range $75-81/bbl. The US EIA is an exception, indicating a Brent price of $85/bbl for next year (but this is still only slightly higher than today).
 Source: Integr8 Fuels
Finally, what does this mean for bunker prices in 2025?
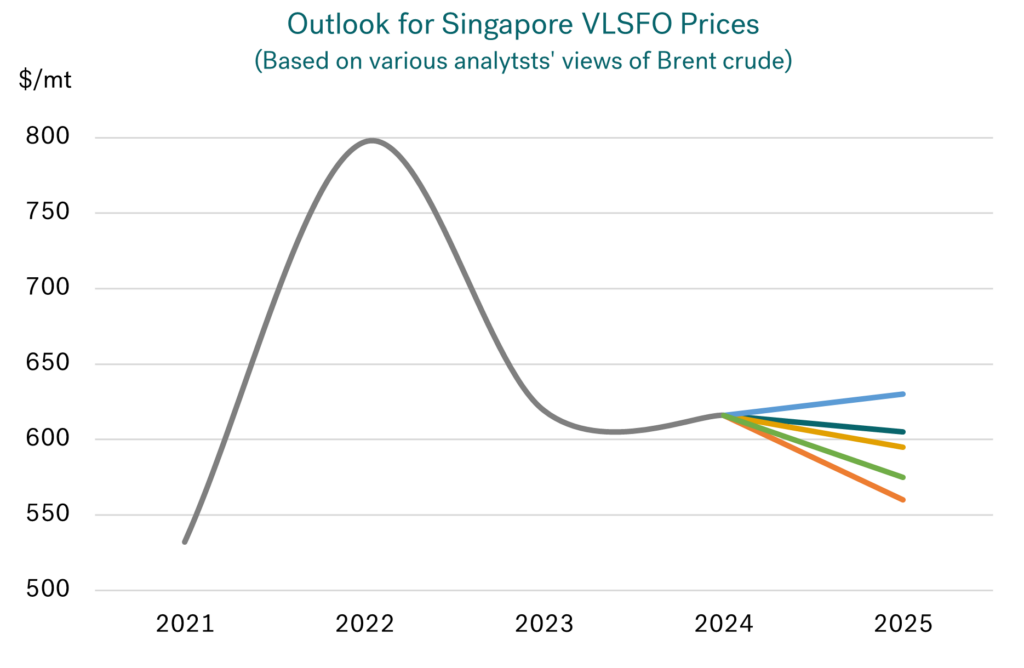
If (and this is a big IF) the analysts are right in their Brent forecasts, and VLSFO broadly tracks the price of Brent, then we are looking at lower bunker prices next year, with Singapore VLSFO in the $550-600/mt range.
 Source: Integr8 Fuels
Let’s keep watching and see what happens.
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
We may be in an oil-dominated bunker market for at least another 10 years; but we cannot stand still!
July 24, 2024
View this article as a PDF » BP’s latest analysis looking at the energy sector to 2050 BP has just published its annual ‘Energy Outlook’ looking at two scenarios going through to 2050. These are not forecasts, but illustrate two cases, the first reflecting what it… Read More
BP’s latest analysis looking at the energy sector to 2050
BP has just published its annual ‘Energy Outlook’ looking at two scenarios going through to 2050. These are not forecasts, but illustrate two cases, the first reflecting what it would take to reach ‘net zero’ by 2050, and the second showing a scenario if the world continues on its ‘current trajectory’ of policies and timings towards environmental measures.
A picture paints a thousand words!
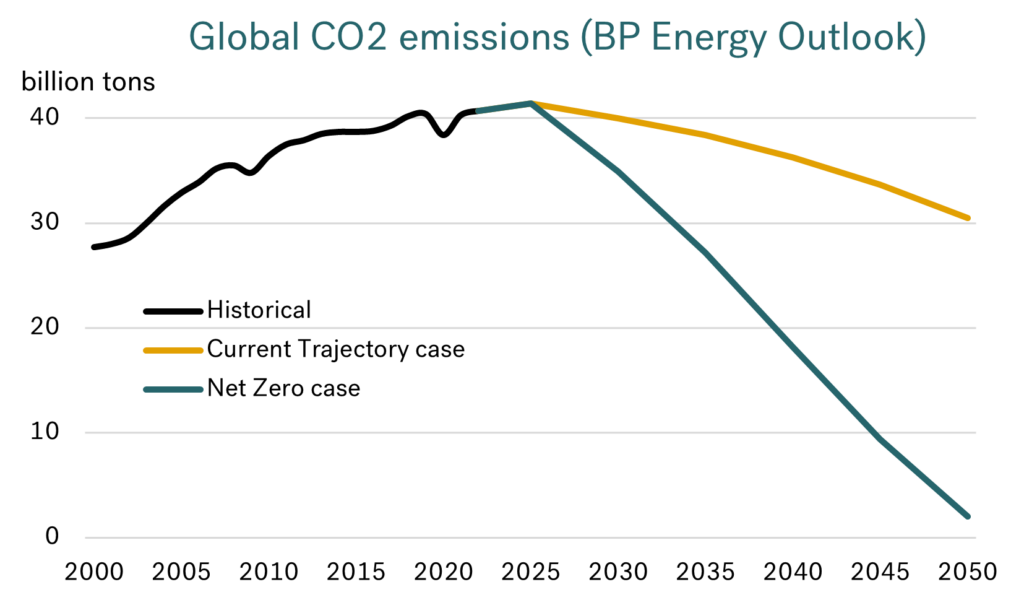
Historically, the graph below shows how CO2 emissions have risen since 2000 and that the environmental measures taken so far have not been enough to stop increases in global CO2.
 Source: BP
Looking to the future, the net zero case highlights the extreme challenges the world faces to achieve this target by 2050. It is literally the ‘bottom line’ for any scenario looking at the future for energy, and a 95% decline in CO2 emissions would clearly have an inconceivable impact on almost all industries, including our own.
Even BP’s ‘current trajectory’ case indicates a turning point and a 25% decline in CO2 emissions by 2050. This is still a major shift from where we are today and would require significant changes in bunker fuels to take place (as is shown later in this report).
A focus on BP’s oil and shipping analysis
In their outlook BP cover oil, gas, coal, power, and low carbon hydrogen. However, in this report we focus on BP’s scenarios for the oil sector and their cases for marine fuels.
The first main point is that in both scenarios there is a forecast major increase in seaborne trade; a 70% gain in the current trajectory and a 30% gain in the net zero case by 2050. Despite this, with greater efficiencies and shifts they see no net gain in energy demand for shipping under the current trajectory case, and a 20% decline in net zero.
The common theme in both cases is that BP see a move away from oil as a bunker fuel and a shift to what are currently viewed as ‘alternative fuels’. This is through the delivery of new ships capable of running on alternative fuels and the retro-fitting of older ships to use these alternative fuels. In this way, biofuels and low carbon hydrogen are potentially the biggest elements of the bunker market going forward, especially moving towards a ‘net zero’ world.
What is the outlook for oil demand in the two BP scenarios?
Electrification is going to be the major shift in the energy balance. The ever-falling cost structure of wind and solar power is accelerating this transition. For oil markets, there is already a seismic shift underway in the electrification of road transport markets, away from gasoline and diesel towards EVs (and electric trucks sometime in the future).
Although shipping is generally a ‘hard to electrify’ industry, we are not immune to what is happening elsewhere in the oil sector. The loss in gasoline and diesel demand could have a major knock-on effect on refining.
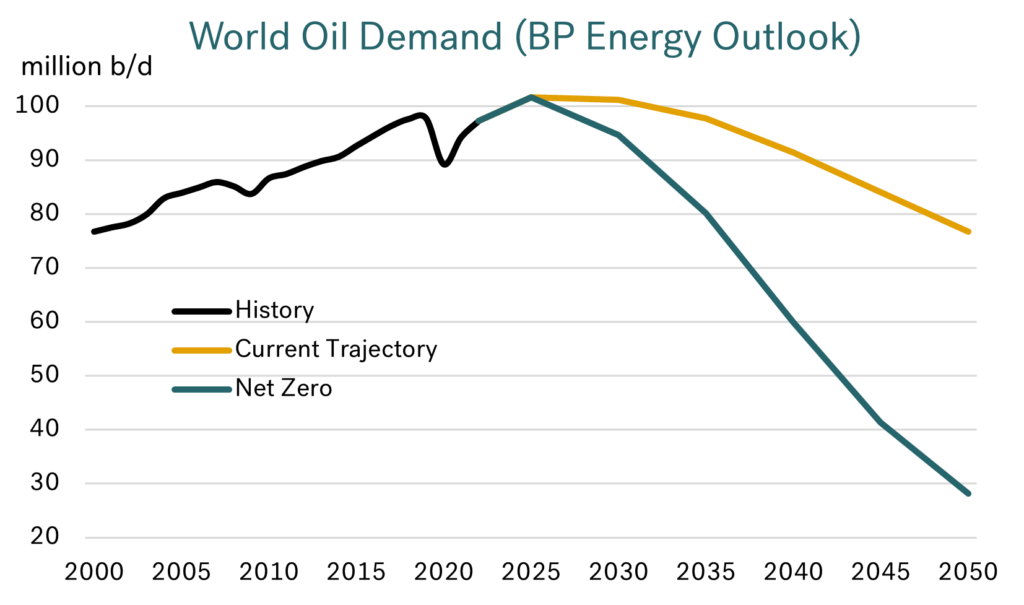
It is not surprising that the future profile for oil demand is very much aligned to the success, or not of reducing global CO2 emissions. Hitting the net zero target by 2050 (or whenever this may be) would mean a near non-existent oil industry.
 Source: BP
In contrast, BP’s ‘current trajectory’ case would mean the size of the oil industry stays more-or-less the same as it is today through the next 10 years. It is only in the 2035-50 period that oil demand declines, and then only taking it back to the same size of the market we saw in 2000.
The make up of the oil industry is going to change, whatever happens
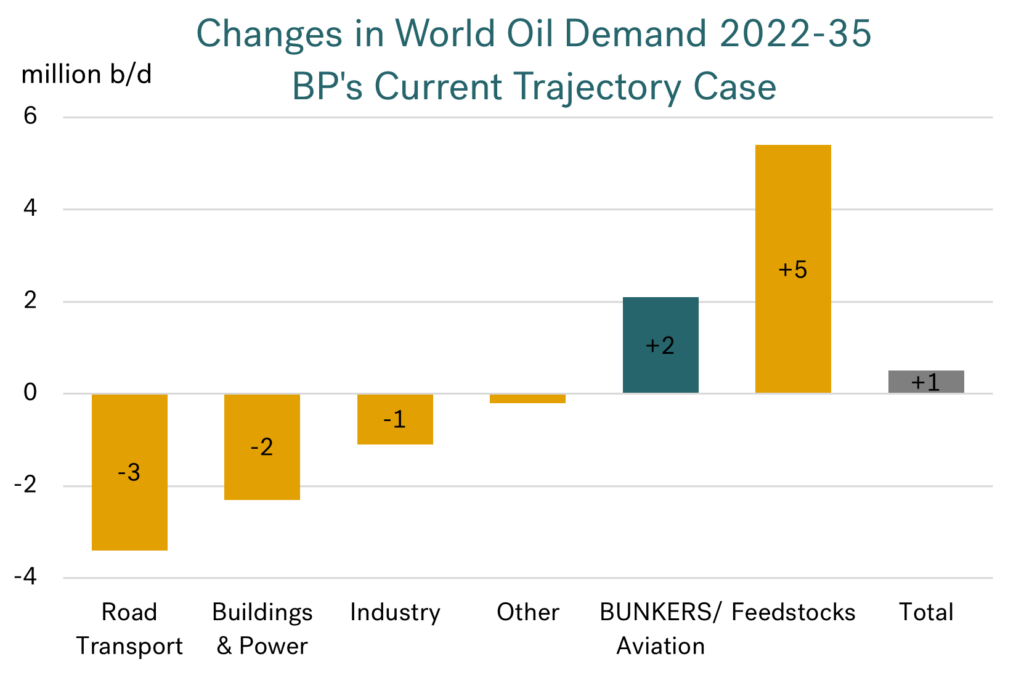
Even with very little change in the overall size of the oil market through to 2035 under the ‘current trajectory’ case, the refining industry must still adapt. The graph below highlights the shifts in demand for different sectors:
- moving away from gasoline, diesel, and gasoil; the products in decline because of electrification in road transport, buildings and industry;
- and towards the growth markets, including bunkers and aviation, but especially into lighter end products as feedstocks into the petchem industries.
 Source: BP
What about in the much longer term?
In this same BP case, the significant changes in the size of the oil industry and the balance in products takes place after 2035. The more rapid moves away from gasoline, diesel, and gasoil indicate a 20% decline in the size of the oil industry in this 2035-50 period (as opposed to the 1% gain over 2022-35).
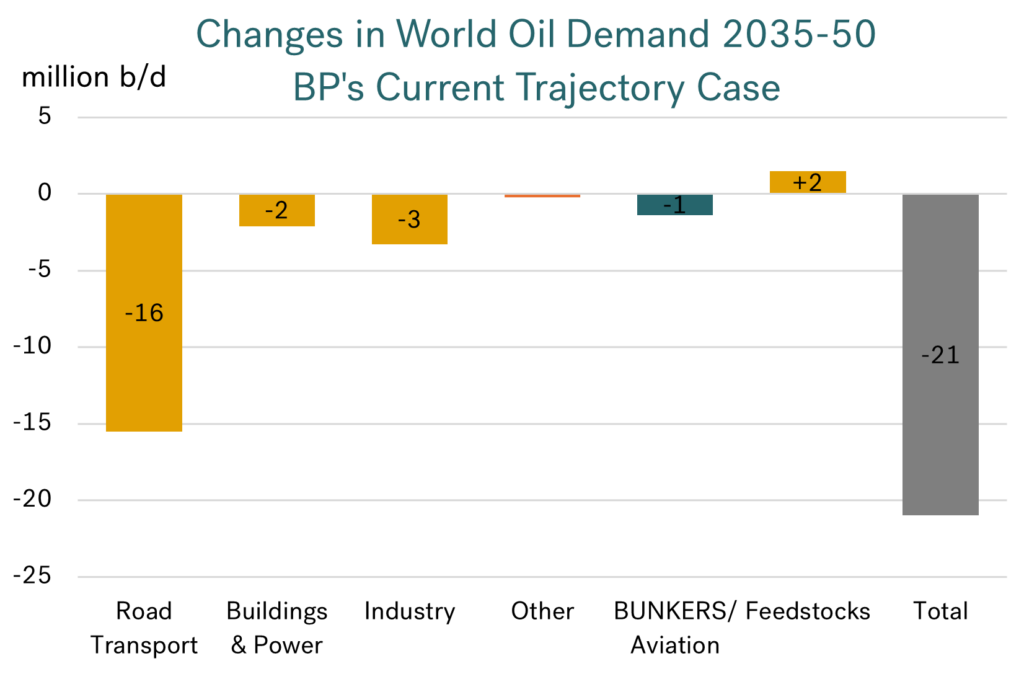
Source: BP
Although the scenario shows only a small decline in oil use in bunkers and aviation, this is against significant increases in seaborne and air travel. The pointers are we are moving more towards alternative fuels.
The drive to alternative bunker fuels must continue
The current discussions, investments, and technologies in alternative fuels for shipping are testament to the future needs for our industry.
BP comment on this and in the next 10 years highlight LNG, biofuels (bio-methanol and biodiesel) and hydrogen derived fuels (ammonia and methanol). In their current trajectory case, they see these alternative fuels accounting for around 15% of the bunker market in 2035, BUT reaching close to 40% of the market by 2050.
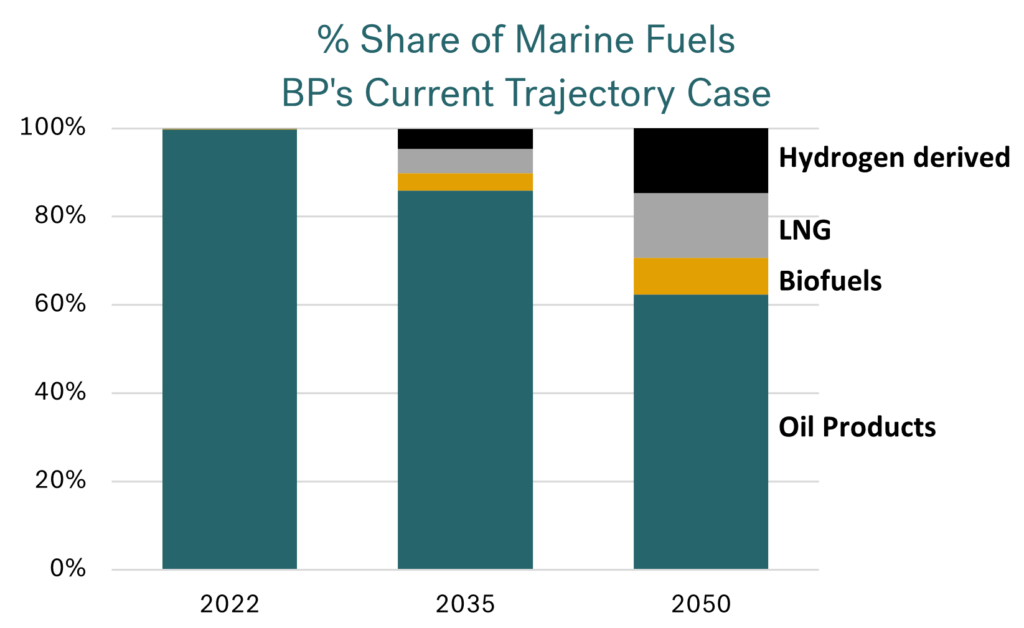 Source: BP
For a 40% share of the bunker market by 2050 an enormous amount of work has to be done in low carbon shipping, especially considering the lead times in the industry.
What about the net zero case, whenever it may happen?
An even more radical approach must be adopted if ‘net zero’ is to be met, even if the target or achievement is after 2050. In their net zero case, BP put oil products at only 10% of the bunker market. The growth in LNG is also constrained in this case, again as it is a fossil fuel.
In a decarbonised world there would have to be a strong drive into biofuels and hydrogen derived fuels to achieve the ‘net zero’ balance.
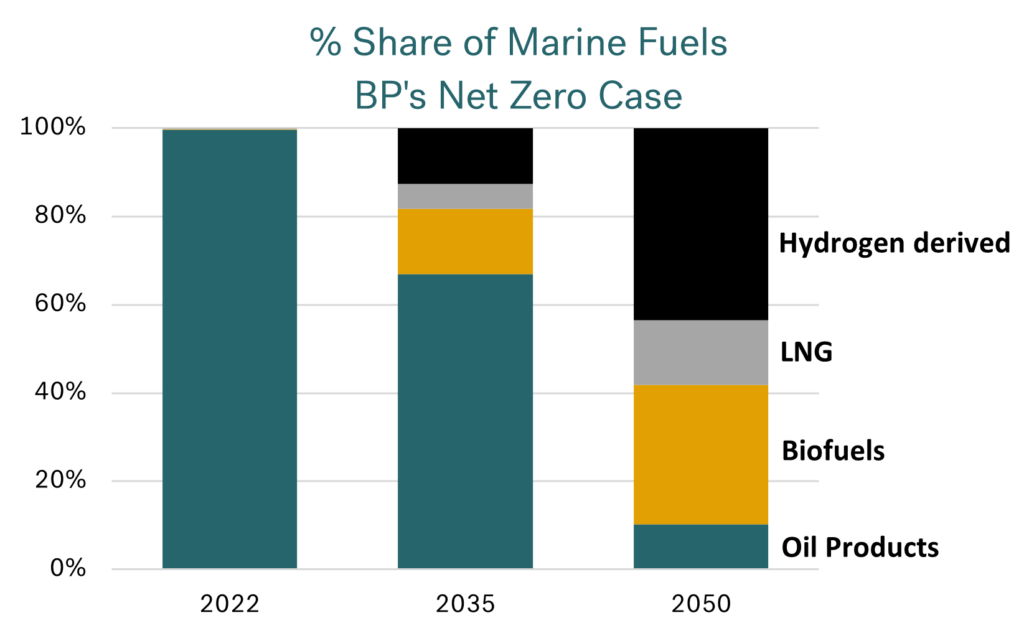 Source: BP
As we are currently seeing in the wind and solar power sectors, we need high volumes and lower costs in hydrogen derived fuels to make low carbon shipping possible.
No big changes in the bunker market in the next 10 years, but that doesn’t mean we can do nothing!
In general terms, a number of analysts are still indicating oil demand rising through the next 10 years or so, and pushing the point of peak oil demand to around the mid-2030s. In fact, Goldman Sachs Research has just put out an article along these lines, with peak demand another decade away and then plateauing around this level for another few years (i.e. not falling until the late 2030s).
So, it seems oil is going to be the key supplier to the bunker market for at least the next 10 years or so. This could instil a degree of complacency, but given political direction, public sentiment and impacts on the oil industry outside the bunker sector, it is only a question of time when ‘alternative fuels’ dominate our business, even if it is post 2050.
Given the lead times and the technological advances needed, it is clear we have to continue to drive our industry forward along a low carbon path.
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
Speculators are buying;
it looks like prices are going up!
June 26, 2024
View this article as a PDF » We are at a turning point; oil prices are rising We have highlighted some major bearish factors over the past few months, such as weak prospects for oil demand growth and the huge challenges facing OPEC+ for them to… Read More
We are at a turning point; oil prices are rising
We have highlighted some major bearish factors over the past few months, such as weak prospects for oil demand growth and the huge challenges facing OPEC+ for them to even maintain oil prices. Prices had been tracking these developments, and in early June VLSFO fell to its lowest in almost
a year.
Though, looking at the graph below, things have taken a massive change in the past couple of weeks. The market has turned, and we should look to higher prices in the near-term; momentum today is definitely bullish.
 Source: Integr8 Fuels
Look at the changes in speculative positions in the market!
The ability for money to easily flow into and out of oil futures markets means shifts in price direction and price volatility can be extreme. This often comes from inflows and outflows of ‘speculative’ money. This is now generally termed as ‘managed money’, coming from hedge funds, pension funds and trading activities etc, and the players here can be very big! For the purposes of this report, we refer to this as ‘speculative’.
We are in one of these extremes right now, with a major reversal in ‘speculative’ funds taking place.
It doesn’t take much to link oil price direction and market volatility to shifts in the net position taken by traders/hedge funds etc. Of course, there are endless discussions about what drives what, and ultimately there must be ‘good’ reasons why players take a certain position. However, once the market ‘gets going’ there can be a period of self-fulfilling prophecy!
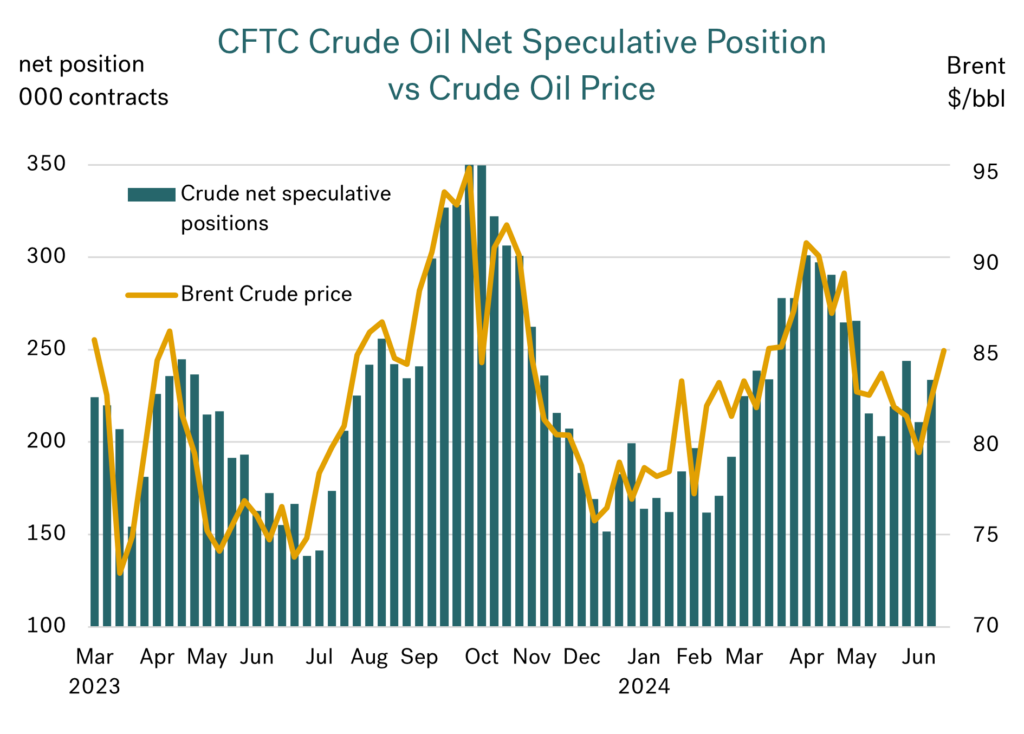
These dynamics are shown in the graph below, using data published by the US Commodity Futures Trading Commission (CFTC). It illustrates the net position taken by ‘speculators’ in US crude futures and options markets, and compares this with Brent front month futures price.
 Source: Integr8 Fuels
When speculators increase their net long positions, oil prices rise; when they reduce their net long positions, prices fall. From late April through to early June (even after the OPEC+ meeting), speculators were unloading their net long positions, and crude prices fell by more than $10/bbl. Hence the comparable $80/mt fall in VLSFO prices!
But we have now seen a reversal. Speculators are now buying back into the market and oil prices are up from their lows. Consequently, bunker prices are also moving higher.
Getting more granular on the speculators’ position
In these reports we often delve a bit deeper into the detail behind oil demand and price. In this case it is worth looking in greater detail on how the net speculative position is determined. In doing this we have to go down to the absolute number of long positions and short positions taken by these players. This will give us a greater understanding of what is driving the net position and just how
far things have changed. What it will show is that we could be at the start of a large-scale buying spree coming from ‘managed money’, and if so, this would push prices higher over the coming weeks/months.
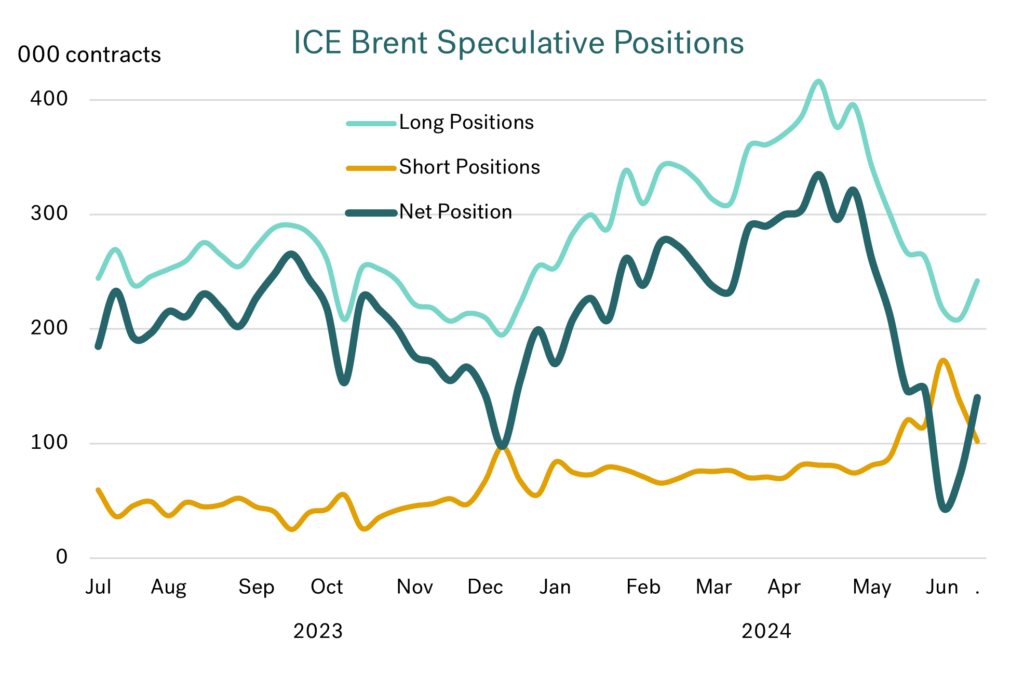
Digging into this detail, the graph below illustrates a breakdown of the ‘speculative’ positions taken in the ICE Brent crude market. It highlights the number of long positions, the number of short positions, and then the resulting net position held by speculators. From this it can be seen that outright long positions are the driving force behind this part of the speculative market. However, the recent rise and fall in short positions can cause a ‘double whammy’ in price movements.
 Source: Integr8 Fuels
Price rise to late April backed by extreme speculative length
Looking at developments this year, oil prices had been on an uptrend from the start of the year through to late April, with speculators here collectively doubling their long crude positions to a peak of over 400,000 contracts (equivalent to 400 million bbls) and its highest level since 2020. At the same time the speculative short position remained more-or-less flat, at around 75,000 contracts.
Price fall led by speculators going from one extreme to another
The price drop we have highlighted since end April was extreme and did involve a twist. Not only did the speculators unwind their extreme length, but they also collectively increased their short positions to the highest level since early 2020 and the start of the pandemic. The power of these trades could only mean a fall in oil prices.
So, by early June the net speculative position in ICE Brent crude was not only lower than at any time in the past 12 months, but it was also even lower than at the start of the pandemic, and in fact at its lowest since 2014 in this market. This shows the extremes to which the speculative position had fallen, and so just how potentially big the reversal can be!
Prices have just started to rise, but speculators could take them even higher!
So, there has been a speculative reversal over the past two weeks, moving away from the extreme low position in early June. Prices have risen with this; Brent is up $7/bbl and VLSFO up $30-40/mt. But speculators have only just started unwinding their short positions and buying back length; it looks like there is a lot more to go!
So, for the time being, any bearish talk on weak oil demand, more non-OPEC+ oil or low refinery margins is likely to be significantly outweighed by the bullish price sentiment from traders/hedge funds etc ‘re-balancing’ their exceptionally low speculative positions. In fact, there is already an impetus in some news stories backing this up. Pointers to a bullish European diesel market, stronger summer gasoil demand in the northern hemisphere and declining stock levels over the coming months are some topics being discussed.
So, perhaps forget any bearish fundamental stories for a while and hang on to the coat-tails of the trading community in a rising market?
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
Bunker Quality Trends Report June 2024
June 11, 2024
Integr8 Fuels’ fourth edition of the bi-annual report analyses data from 130 million metric tons of supply, to reveal key trends relating to fuel quality and availability. Read More
Integr8 Fuels’ Bunker Quality Trends Report June 2024
In the fourth bi-annual report from Integr8 Fuels, bunker quality and claims manager Chris Turner advises shipowners and bunker buyers on how they can improve their buying processes and performance. Tapping into the world’s biggest bunker fuel quality sample database, Turner reveals the most pressing quality issues the industry is up against.
These include:
- Red Sea closure affecting VLSFO compliance for vessels rerouting around Africa
- Global VLSFO compliance suffers as suppliers stretch barges to cash in on rising HSFO demand, driven by increasing scrubber numbers
- Two-thirds of fuels are still sold with obsolete (pre-2017) specifications. Can the new ISO specs finally shake up old school practices?
- Profit margin-motivated blenders push more HSFOs over ISO limits
- VLSFO sulphur off specs worsening in the ARA and partly driven by high- to low sulphur barge switching
- The supply landscape as it relates to availability, off-specification trends and problematic parameters
- Biofuel quality and distribution
- Geographical variances and “hot spots”
Download the report (PDF) (Recommended for mobile) >>
About the Author:
Chris Turner, Technical Manager
Chris joined Integr8 Fuels in 2017, spending several years in Singapore before relocating to Dubai. With over 35 years in oil and shipping, he has held roles in laboratory management, physical supply, broking, and trading. More recently, he has focused on technical supervision of exclusive buying and helped develop quality systems for biofuel purchasing, leading to Integr8’s ISCC certification.
An active IBIA Technical Working Group member, Chris is also a regular speaker and panellist at major bunkering conferences worldwide.
What is OPEC+ going to do in June (and the rest of this year)? It will be an important issue for us in bunkers!
May 22, 2024
View this article as a PDF » Bunker prices are at their lowest for three months Although VLSFO has been in a relatively narrow price range, prices are now at their lowest for more than 3 months. The sharp drop in oil prices at the… Read More
Bunker prices are at their lowest for three months
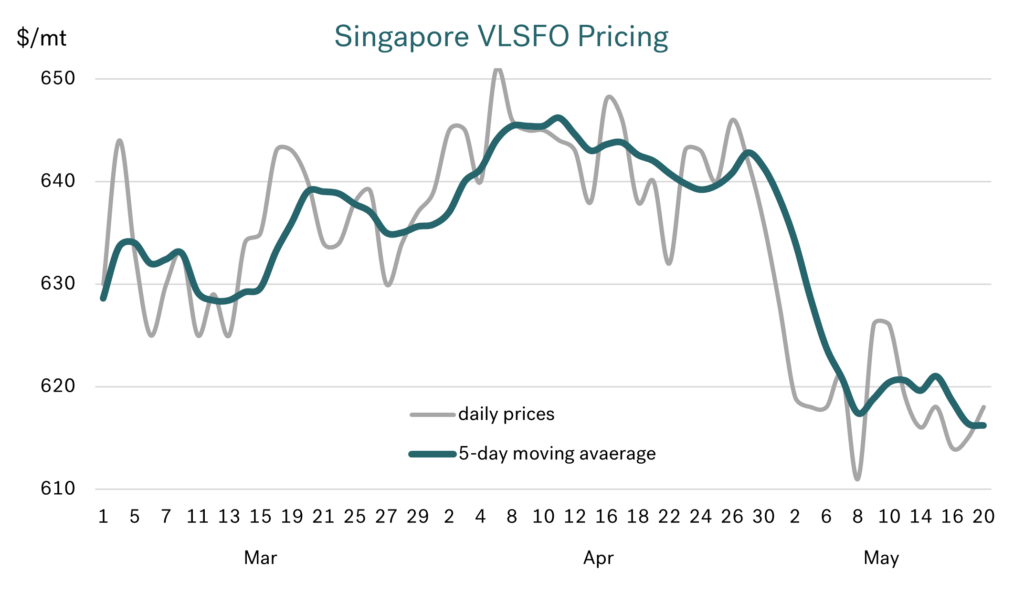
Although VLSFO has been in a relatively narrow price range, prices are now at their lowest for more than 3 months. The sharp drop in oil prices at the start of this month has meant Singapore and Fujairah VLSFO prices are down by $20/mt since end April, with Rotterdam VLSFO down by $30/mt.
General concerns about future economic growth, a perceived greater chance of a truce in the Israel/Gaza conflict, weaker oil demand (especially in Europe) and rising oil stock levels have all contributed to this bearish sentiment and led prices down.
 Source: Integr8 Fuels
Lower crude prices mean OPEC+ has tough decisions to take
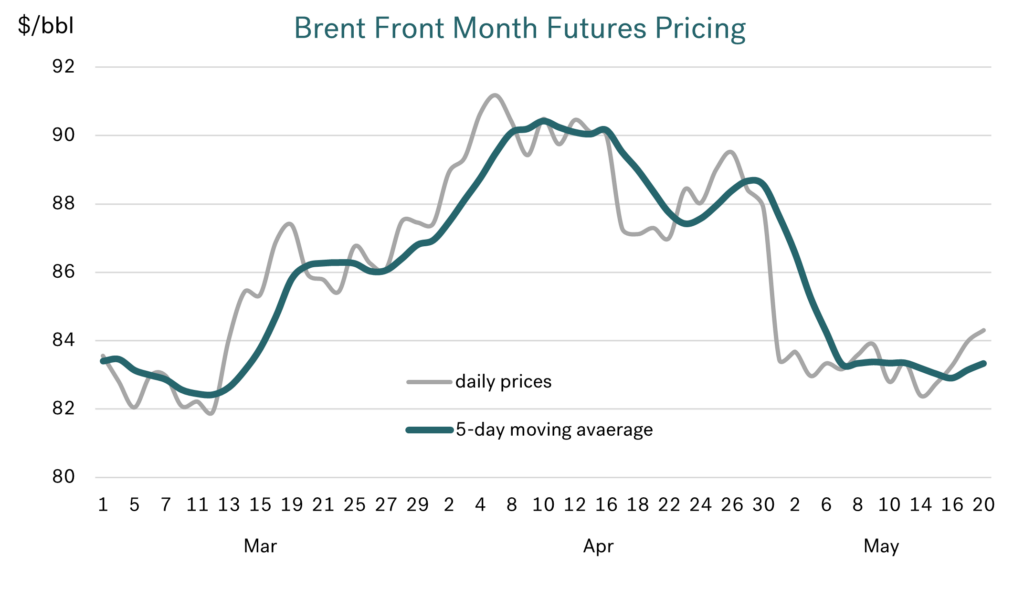
The drop in crude prices has meant Brent has fallen from $90+ levels, back down to the low $80s, and is why OPEC+ is facing a significant dilemma at their upcoming June 1st meeting.
 Source: Integr8 Fuels
The big questions for OPEC+ surround their production cutbacks, where there are three key aspects:
- First, the main cutbacks from all OPEC+ countries that amount to around 3.7 million b/d. These have been extended a number of times and are now scheduled to run until the end of this year, and so perhaps will not be a primary focus just yet.
- The main issue now surrounds a limited number of OPEC+ countries that have made additional voluntary cutbacks totalling 2.2 million b/d. These were implemented in July 2023 and have been extended through to the end of the second quarter this year.
- Finally, the extent of continued over-production by some countries. In April, the main ‘over-producers’ were Iraq (at 0.24 million b/d), UAE (0.24 million b/d), Kazakhstan (0.13 million b/d) and Russia (0.20 million b/d)
The immediate dilemma for OPEC+ is: what do those countries making the additional voluntary cutbacks do? The quote from OPEC in early March was that from end June “these voluntary cuts will be returned gradually subject to market conditions”. Will they do this?
Which countries are we talking about?
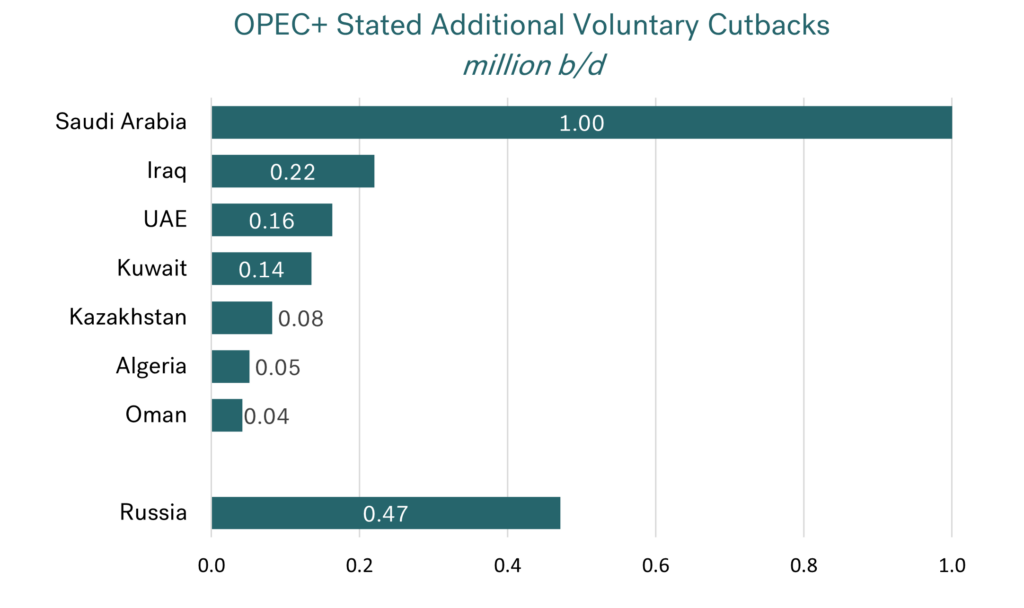
Of the eight countries involved in the additional 2.2 million b/d cutbacks, Saudi Arabia is by far the biggest, and most likely to drive the decision to extend or unwind this part of the agreement.
 Source: Integr8 Fuels
On paper, Russia also has a significant role, but this is ‘clouded’ by the fact that the crude cutbacks are split between production for the domestic market and those for export. It is only the export volumes that matter to the fundamentals and sentiment in international oil markets.
Not all eight countries will have an impact
Outside of Saudi Arabia, and possibly Russia, there may be little impact from the unwinding this ‘additional’ agreement. Even if it does go ahead, it is possible that there will be very little (if any) change in production from six of the eight member countries involved.
The reasoning here is that in the broader OPEC+ agreement covering all countries, the four members that are producing substantially more than their allocation (Iraq, UAE, Kazakhstan, and Russia) are also included in the eight members that make up this additional 2.2 million b/d cutback.
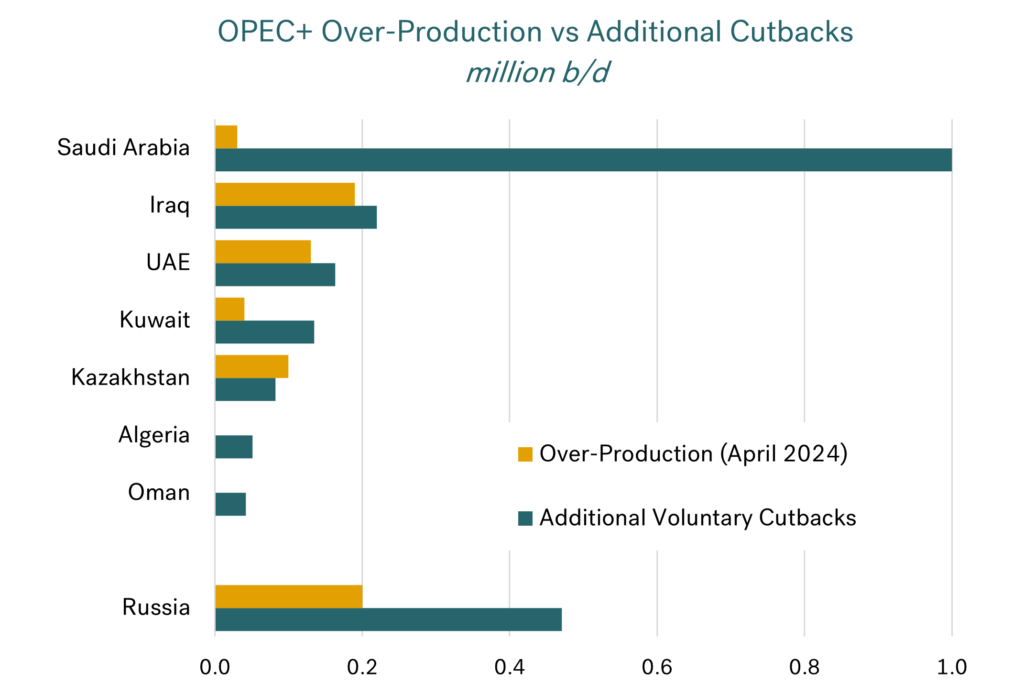
The graph below illustrates the extent of over-production versus the agreed additional cutbacks made by each of the eight countries involved.
 Source: Integr8 Fuels
For instance, Iraq is currently producing around 0.19 million b/d more than its 4.00 million b/d allocation. If the additional cutbacks are removed, then Iraq’s new allocation will rise to 4.22 million b/d. This is virtually in-line with their current production. So, for Iraq, it could be that they just maintain current production levels as the additional cutbacks are unwound. This would mean they automatically fall into line as a ‘good’ member, adhering to their new, higher allocation; AND there will be no increases in world oil supply!
It is exactly the same for UAE and Kazakhstan; their output levels can just continue at current levels, and they will also ‘fall into line’ with their new allocation as the additional cutbacks are unwound.
After this, Algeria and Oman are relatively small players in volume terms, and so will have limited impact. It does mean that Saudi Arabia and Russia will be the main protagonists.
So, what will happen if the additional cutbacks are unwound in Q3?
Based on the scenario above, which is credible, if the additional cuts are removed then Saudi Arabia is highly likely to ramp up production by 1 million b/d, and Kuwait potentially by 0.1 million b/d.
That then leaves Russia, which is highly uncertain given it may not have capacity to raise output, and if it has, whether this would go to their domestic market, or into the international market.
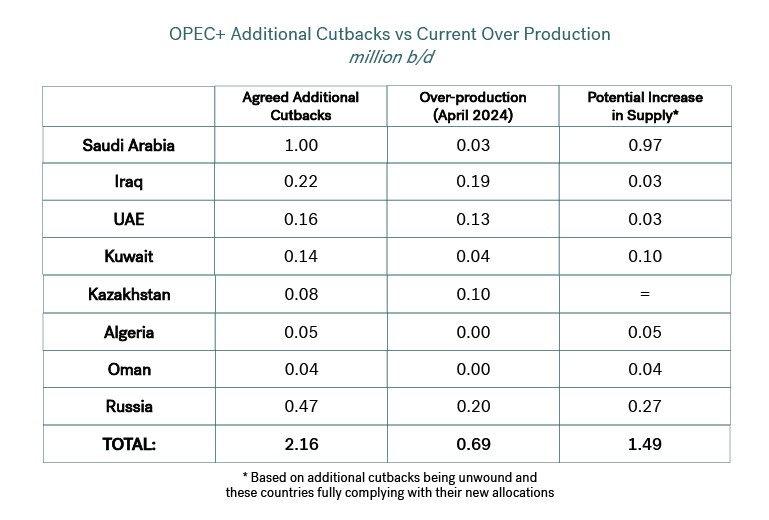
The table below indicates what the agreed additional cutbacks are, compared with the latest levels of over-production. Assuming the agreement is unwound and each country abides by its new production allocation, the final column shows the potential gain in oil supply.
Source: Integr8 Fuels
Either way, it looks like a removal of the additional OPEC+ cuts would result in an extra 1.0-1.2 million b/d to world oil supply (outside of Russia), and not the full 2.2 million b/d headline figure.
What signal would an ‘unwinding’ send to the market?
The IEA and the US EIA put the call on OPEC+ remaining more-or less flat through the rest of this year, and also flat to a potential slight decline next year (highlighted in our report April 24th). This implies any unwinding of the OPEC+ additional cuts would be a bearish signal to the market this year (and even in 2025!).
However, market analysis by OPEC contradicts this, and shows a much stronger growth in oil demand for 2024 and 2025 than other organisations. In their latest report, OPEC indicates the call on OPEC+ increasing by around 0.8 million b/d over the remainder of this year, and another 0.9 million b/d between end 2024 and end 2025. On their basis there is room for OPEC+ to start unwinding the additional cutbacks from end June and there would be only a small material change to the fundamental oil balance.
It is likely to come down to Saudi policy
Although an announcement could be made at any time, the market focus will be on the run-up to the June 1st OPEC+ meeting.
If the group decides to extend the additional cuts again, then this is more likely to be seen ‘price neutral’.
For most, an unwinding is likely to be seen as a bearish signal. In this case, bunker prices would fall. There are also further implications for us in bunkers, as almost all the crude supply gains would be heavy/sour grades from the Middle East, and so have a potential impact on the VLSFO/HSFO spread.
Is there a ‘curved ball’, where OPEC+ make more cuts? We can only keep an eye on OPEC+ and Saudi Arabia ahead of the June meeting (and for the rest of this year and next!).
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
Is it time to worry when all the analysts are in agreement?
April 24, 2024
View this article as a PDF » Brent can’t stay above $90/bbl for very long! For a number of months, we have pointed towards ‘weak’ fundamentals in the oil market and the counter effects of high geopolitical risks, with a net outcome of only limited movements… Read More
Brent can’t stay above $90/bbl for very long!
For a number of months, we have pointed towards ‘weak’ fundamentals in the oil market and the counter effects of high geopolitical risks, with a net outcome of only limited movements in price.
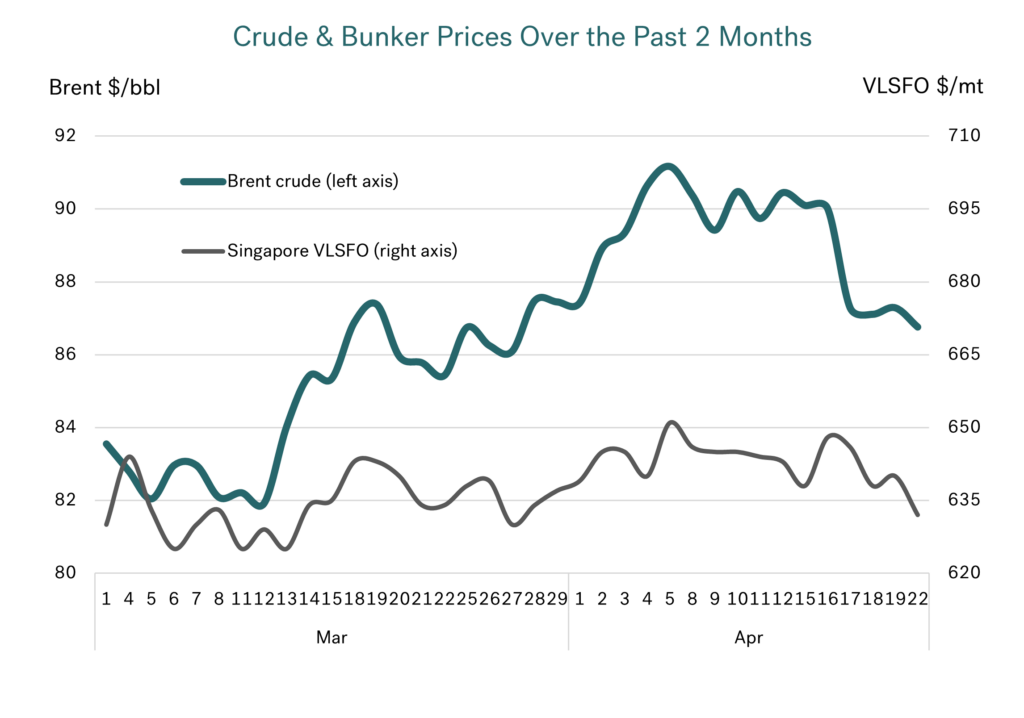
In the past month we have seen the geopolitical risks escalate again, with Iran now also involved in military operations. Brent futures did move up in response, from around $86/bbl to just above $91/bbl (it’s highest for 6 months). But this is only a gain of some $5/bbl, which doesn’t seem very much given military actions between Israel and Iran. To emphasise the limited ‘price concerns’ in these conditions, Brent futures have now fallen back to their earlier levels!
 Source: Integr8 Fuels
If, given the circumstances, crude price movements over the past month can be considered ‘muted’, then shifts in bunker prices have been ‘non-existent’ The graph above shows daily Brent futures prices alongside Singapore VLSFO, on comparable scales. In bunkers we haven’t seen the full extent of movements in crude futures prices, and looking at the daily Singapore VLSFO quotes, we haven’t seen a major uptick, and current prices are actually $2/mt lower than a month ago!
More for OPEC+ to do?
It is clear the market is currently ‘relaxed’ on oil supply; crude oil prices did move up on these actions and tensions, but they didn’t ‘want’ to go much higher, and they ‘wanted’ to come down pretty quickly. Looking further ahead, through to the end of next year, all the supply pointers suggest there will be more than enough oil to satisfy world needs. In fact, now it looks like the OPEC+ group will need to continue to extend their agreed and voluntary production cutbacks beyond June, and well into next year, to try to maintain prices around current levels.
Gains in non-OPEC+ production give confidence to the market and concerns to OPEC+
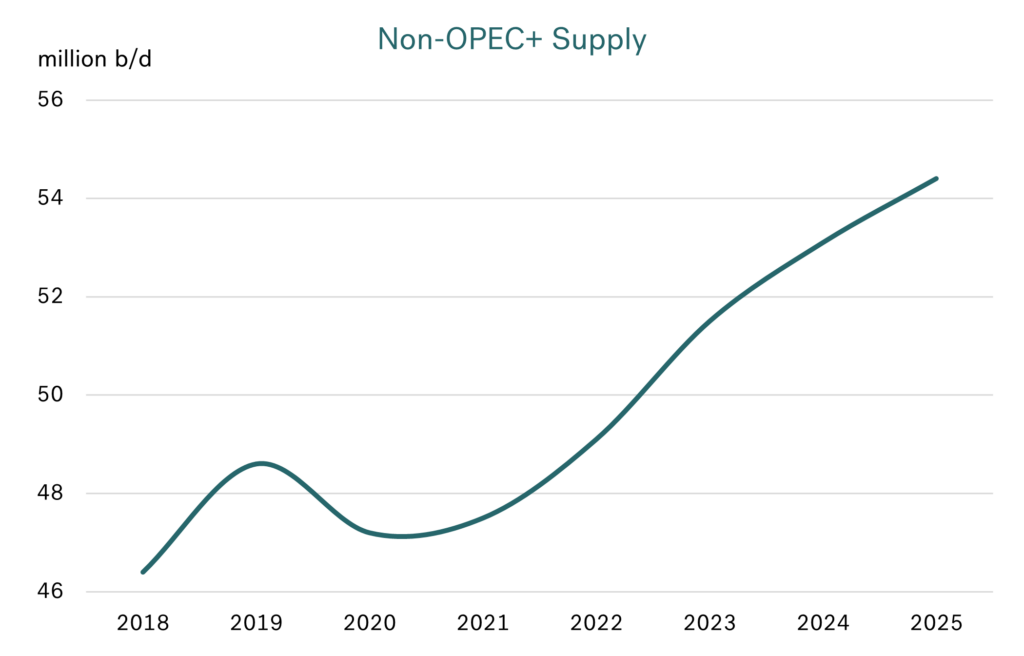
Work and investment in non-OPEC+ production certainly waned during covid, meaning depletion rates at existing fields were higher and new oil developments lower. Hence non-OPEC+ supply fell during 2020/21, then only showed a modest gain in 2022, and started to pick up in 2023.
But that has now all changed. Renewed capital commitments to existing oil and new projects suggest non-OPEC+ output will rise from 51.5 million b/d last year 54.5 million b/d by 2025. The ‘big hitters’ in this gain will be the US (shale and Gulf of Mexico oil), Brazil, Guyana, Canada, and Norway.
 Source: Integr8 Fuels
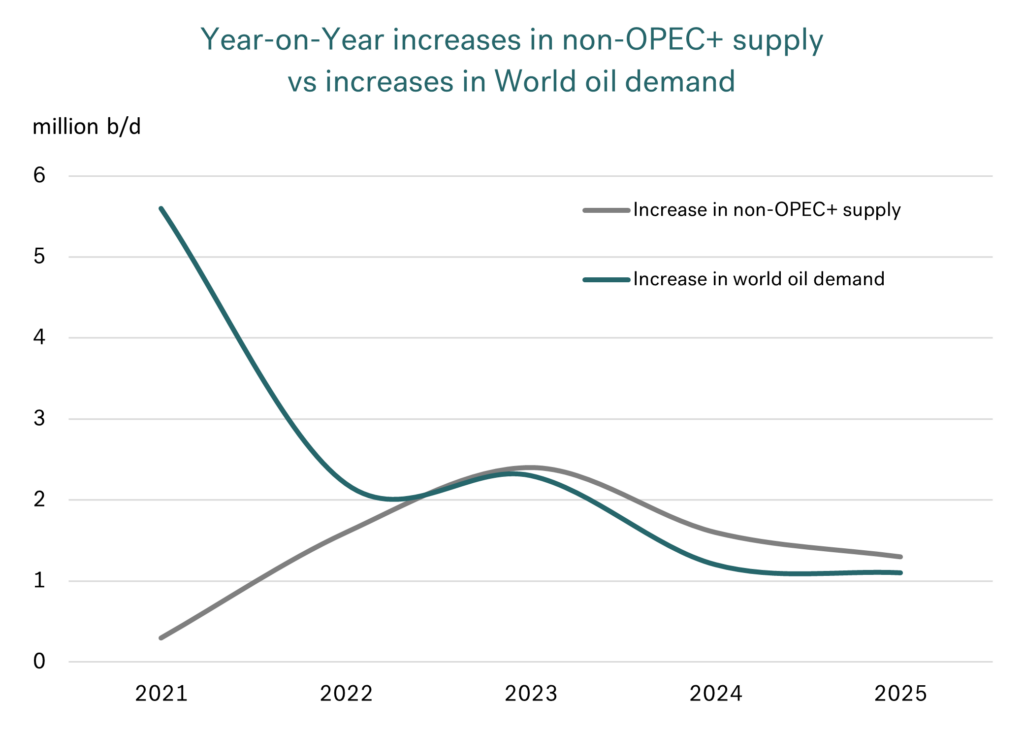
This 3 million b/d supply gain in non-OPEC+ over the 2 years to 2025 is expected to be in line with, or even slightly greater than increases in World oil demand. This means the world has shifted dramatically from 2021/22, when we were coming out of COVID and heavily reliant on OPEC+ raising output to meet the post-pandemic rebound in oil demand.
 Source: Integr8 Fuels
Last year was the turning point, where non-OPEC+ output started to ramp up and OPEC+ made agreed and voluntary production cutbacks to support oil prices (with Brent in the $80s).
These OPEC+ cutbacks have been reviewed and extended a number of times. Also, a few OPEC+ countries are producing above their target levels, and there is pressure on these to cutback. However, given the expansion in non-OPEC+ supply, if the OPEC+ cartel want to keep prices anywhere close to current levels it looks like they will have to keep rolling over the current cutbacks well into next year (the next OPEC+ meeting is scheduled for early June).
OPEC+ restraint means more spare production capacity in the world
With the cutbacks and restraint in OPEC+ production, it means there is a close to 6 million b/d spare oil production capacity in the system. Apart from the covid period, this is historically, a high level. Almost all of this spare capacity lies in four countries in the Middle East; Saudi Arabia holding 3.2 million b/d, the UAE 1.1 million b/d, with Kuwait and Iran each reportedly at around 0.5 million b/d. Russia also has reported spare capacity of around 0.4 million b/d, but in current circumstances this is likely to be seen as more-or-less irrelevant.
There is a very modest gain in OPEC+ production capacity expected next year, and so spare capacity could be even higher in 2025. Given the expansion of non-OPEC+ production and the large-scale spare capacity in the Middle East, plus how recent disruptions have been overcome, it is no surprise the market is ‘comfortable’ on supply.
Analysts converging on their price forecasts.
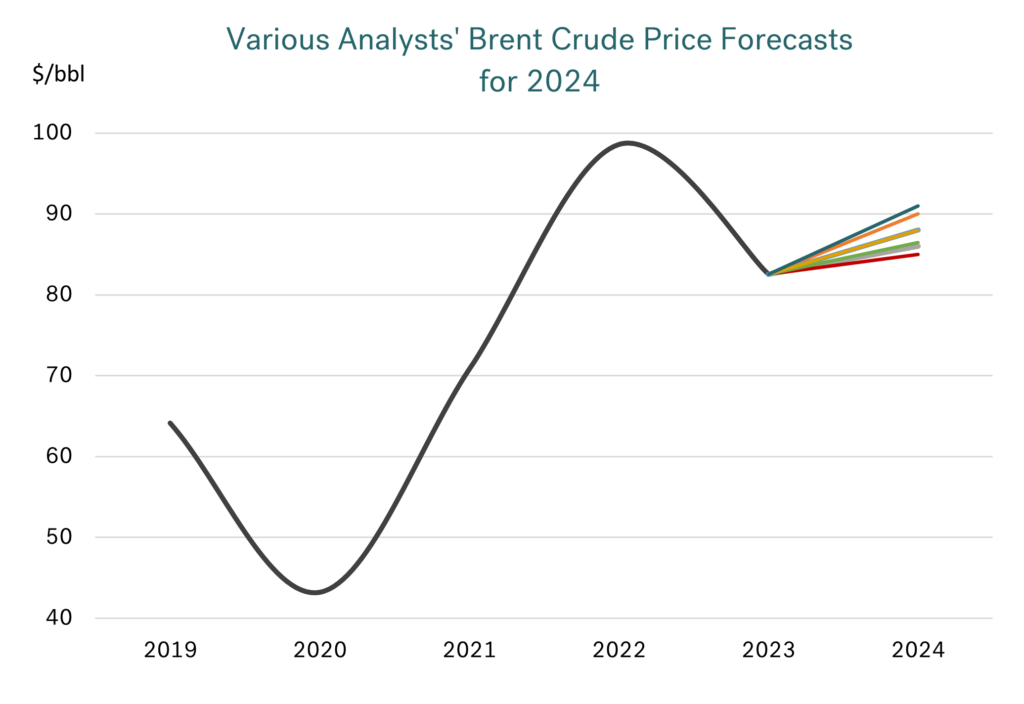
Given how the market has responded over the last year to what in the past would have been considered extreme ‘high risk’ geopolitical and military events, it is not surprising that analysts have ‘put a lid’ on their oil price forecasts for this year, typically at $90/bbl for Brent. The range of forecasts is now very narrow, with almost everyone in the $85-90/bbl as an average for Brent this year. A few have put a slightly higher number of up to $94/bbl for the third quarter average, based on some more positive economic indicators coming out. But in comparison to other times, there is not that much of a difference between analysts’ price views.
 Source: Integr8 Fuels
Is it time to be worried when everyone is in agreement?
Going forward, IF the geopolitical risks are even greater than we have seen (and they have already been extreme!), OR OPEC+ is prepared to make even further production cutbacks, then prices would likely rise and stay well above $90/bbl. BUT, if the situation in the Middle East becomes more settled, then, given the fundamentals, prices are more likely to fall.
So far this year, Brent front month futures has averaged $83.30/bbl. From a perspective here and what we have seen so far this year, it is surprising that none of these analysts looking at average 2024 Brent prices have put a figure lower than last year’s average of $82.50/bbl.
Steve Christy
Research Contributor
E: steve.christy@integr8fuels.com
Dual-fuel vessels owners should consider e-LNG to make the most of emissions compliance
April 11, 2024
Dual-fuel vessel owners should look to liquefied e-methane as a drop-in bunker fuel to make the most out of emission compliance, argue Jonathan Gaylor of Integr8 Fuels and Maximilian Matheis of TURN2X. Read More
Dual-fuel vessel owners should look to liquefied e-methane as a drop-in bunker fuel to make the most out of emission compliance, argue Jonathan Gaylor of Integr8 Fuels and Maximilian Matheis of TURN2X.
We already know that fossil LNG-fuelled vessels will pay less to comply with the EU’s Emissions Trading System (EU ETS) than vessels fuelled with conventional high sulphur fuel oil (HSFO), very low sulphur fuel (VLSFO) and low sulphur marine gasoil (LSMGO) because LNG has a lower carbon factor. Many of these LNG-fuelled vessels will also be compliant with FuelEU Maritime (FEUM) greenhouse gas (GHG) intensity reduction targets until 2030, 2035 and 2040, depending on their engine type and methane slip. Dual-fuel vessels have recently benefitted from low fossil LNG prices, which have rendered it a more attractively priced bunker fuel option to VLSFO, LSMGO (Rotterdam and Singapore) and HSFO (Rotterdam).
Liquefied e-methane, or e-LNG, is almost five times more expensive than fossil LNG, but because you need so little of it per vessel to meet FEUM targets for 2030-2039, it will not add much to the total price of a blend of fossil LNG and e-LNG. Any compliance surplus from extra e-LNG consumption will be added on top of a neutral compliance balance and averaged out across your fleet or pool, or it can be banked for future years.
Incoming LNG Glut
After the LNG bunker market was shaken by Russia’s invasion of Ukraine and skyward prices, it now faces a period of oversupply, low prices and soon a doubling of the global LNG-fuelled fleet. Massive fossil LNG production and export growth from the US and Qatar is set to put LNG in a prime position to continue to trade at discounts to conventional VLSFO and LSMGO prices. Fresh output boosts from Malaysia, Australia and others also form part of a wave of new supply. So, if fossil LNG prices keep at sustained discounts to conventional fuels going forward, these discounts can be used to cover a higher price paid for e-LNG, which can be used to meet more and more stringent GHG reduction targets.
Mass Balancing and Virtual Liquefaction
And you do not necessarily need to blend e-LNG into fossil LNG physically. The LNG industry is increasingly becoming familiar with mass balancing and virtual liquefaction – accounting techniques that remove the need to move physical e-LNG molecules out to every ship and other end-users. A shipowner can order a certain amount of e-LNG in its LNG blend but will actually receive pure fossil LNG in its ship’s fuel tank. The shipowner will pay for, say 1% e-LNG, which will be produced and distributed to another end user that has paid for fossil LNG and would otherwise have consumed only fossil LNG. More e-LNG will be consumed on the balance as a result and costs can be cut in its distribution and liquefaction, which can be done virtually and boost the competitiveness of e-LNG.
Price Edge on Liquid Bunker Fuel Blends
Integr8 Fuels estimates that 2% used cooking oil methyl ester (UCOME) blended with 98% VLSFO is priced around $610/mt with current price levels in the ARA. If you blend e-LNG into the fossil LNG, the e-part will count twice towards FEUM targets towards 2033 because it qualifies as a renewable fuel of non-biological origin (RFNBO) if it has GHG savings of more than 70%. Say you blend in 1% e-LNG with 99% fossil LNG, then that e-LNG component would count as 2% RFNBO and be priced around $480/mt. These prices have been adjusted for calorific contents to make them VLSFO-equivalents in terms of energy. In other words, e-LNG blends are about $130/mt more cost efficient than biofuel blends when you compare energy for energy with 1-2% shares of renewables.
Taking the RFNBO argument a bit further, running just one vessel on 100% e-LNG can cover the FEUM compliance of 44 other similar vessels running on VLSFO between 2025-2029, according to a recent report by the Mærsk Mc-Kinney Møller Center for Zero Carbon Shipping. This is because the e-LNG vessel generates a massive compliance surplus that can be averaged out across a fleet of conventionally fuelled vessels or a pool of vessels. Your compliance surplus can therefore be sold to other shipowners through pooling with them. It can also allow you to lower your EU ETS exposure and help improve your Carbon Intensity Indicator (CII).
FEUM Here to Stay
When we consider not just e-LNG on its own, but in blends with attractively priced fossil LNG, it becomes a more attractive proposition to dual-fuel vessel owners. This will lead to further investments into this space and continue to reduce costs. It is important to note that FEUM is a long-term regulation that can enable shipowners to be confident about signing the long-term agreements that are necessary for e-LNG projects to get through the final investment decision stage. Since these projects will have strong commercial underpinnings, they are more robust. As an e-LNG supplier or project developer, you need long term contracts to underwrite power purchasing agreements for these types of fuels. FEUM creates predictability through being an offtake enabler. This long-term focus does not generally align with the nature of the bunker market – which tends to favour spot deals – but FEUM is poised to help bridge that gap.
How It’s Made
E-LNG is an electricity-based fuel where green hydrogen is one of its two major components. The process of splitting water into hydrogen and oxygen through electrolysis is dependent on renewable electricity generation, so access to competitively priced electricity is key. E-methane is e-LNG in gas form and has no upstream emissions because it is synthesised at plants that combine green hydrogen from renewable electricity with biogenic CO2. The green hydrogen allows renewable electricity to be stored off the grid and without a need for batteries. This green hydrogen is subsequently reacted with captured biogenic CO2 and liquefied into e-LNG.
All of these processes are comparatively CAPEX- and OPEX-intense, but e-methane start-up TURN2X is actively working on lowering the levelised costs for e-LNG to become an even more competitive drop-in fuel. A shared characteristic of all electricity based
fuels (i.e. e-LNG, e-ammonia and e-methanol) are the conversion losses, especially within the electrolysis. The conversion loss from methanation – which TURN2X uses to produce e-methane – is significantly smaller. Further increasing the efficiency of electrolysis will therefore become an important lever to reduce the energy conversion losses going forward.
The Case For E-LNG
It is almost impossible to electrify largescale ocean-going ships and there is not yet technological readiness for hydrogen fuelled vessels – which is why we need to move one step further with the molecules toward hydrogen derivatives such as e-LNG.
TURN2X recently launched its first commercial e-methane plant in Spain’s Miajadas. The location was chosen for its abundant solar energy potential, and because the electricity grid in this region in Spain is already suffering from congestion at certain times during the day, it has become harder for renewable electricity projects to come online. The company is creating an off-grid opportunity to bring in renewables projects while finding another way of transporting it out of Spain – and sees the pan-European gas grid as the largest battery that we currently have.
Munich-based TURN2X is now looking to the maritime sector for long-term contract customers, and because FEUM does not have an end date, it can help underpin growing renewables demand in decades to come. This can, in turn, enable TURN2X to develop even more competitive and scalable solar PV projects on-site for affordable green electricity and further reduce the price of critical CAPEX components such as the electrolyser stacks and the proprietary methanation technology. Maritime is one outlet for TURN2X, which has teamed up with Integr8 Fuels to reach a wide network of fossil LNG-fuelled vessels with e-LNG. Existing bunker infrastructure used to deliver fossil LNG can just as well be used to deliver e-LNG.
Jonathan Gaylor
Integr8 Fuels
jonathan.g@integr8fuels.com
Maximilian Matheis
TURN2X
max@turn2x.com
For more information about Integr8’s energy procurement offering, visit our bunker trading services page.